The S&P 500 fell 2.0% this week, and Information Technology (MW) took the biggest hit. The sector fell 6.4%, the worst of the 11 sectors (chart). The iShares Semiconductor ETF (SOXX) fell 11.8%. Credit worries spread to AI infrastructure. CoreWeave fell 25% last week. Its worst day was Wednesday, when it sank 15% as its bond yields soared. It was the IT sector's second straight losing week. Industrials (OW) also fell for a second week. On a ytd basis, Energy is up 52.7%, the best of the 11 sectors. IT is second at 21.6% (chart).
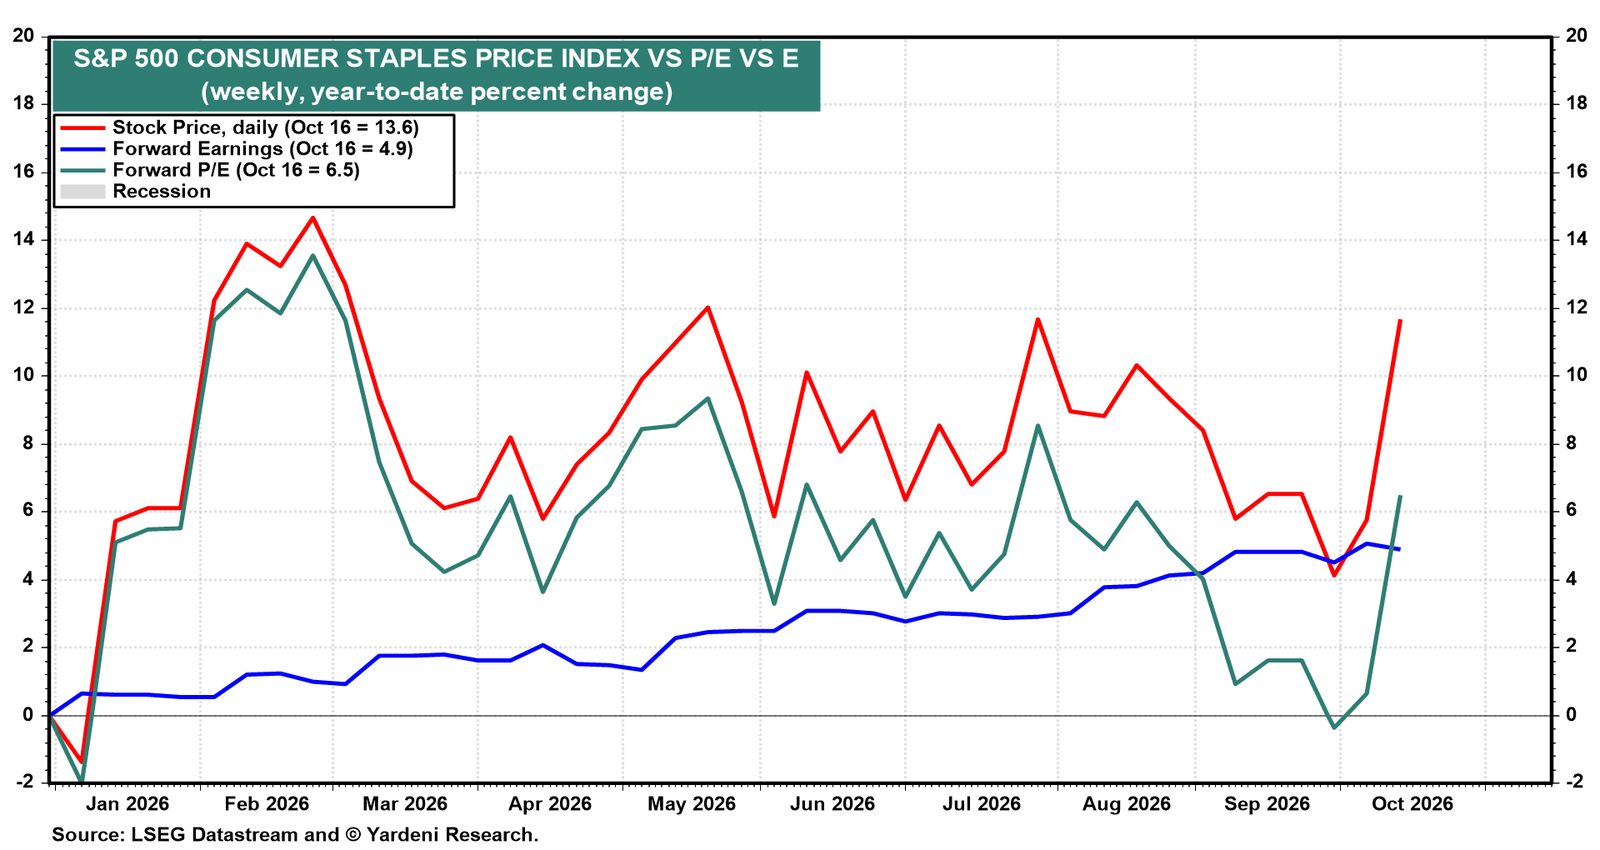
Consumer Staples (UW) and Energy (OW) led the 11 sectors, each up 5.0%. Health Care (OW) rose 3.4%. Every defensive sector gained, with Utilities (MW) up 2.0% and Real Estate (UW) up 1.2%. Health Care and Staples rallied for different reasons. Earnings drove Health Care's gains. Staples' gains have been driven by its multiple.
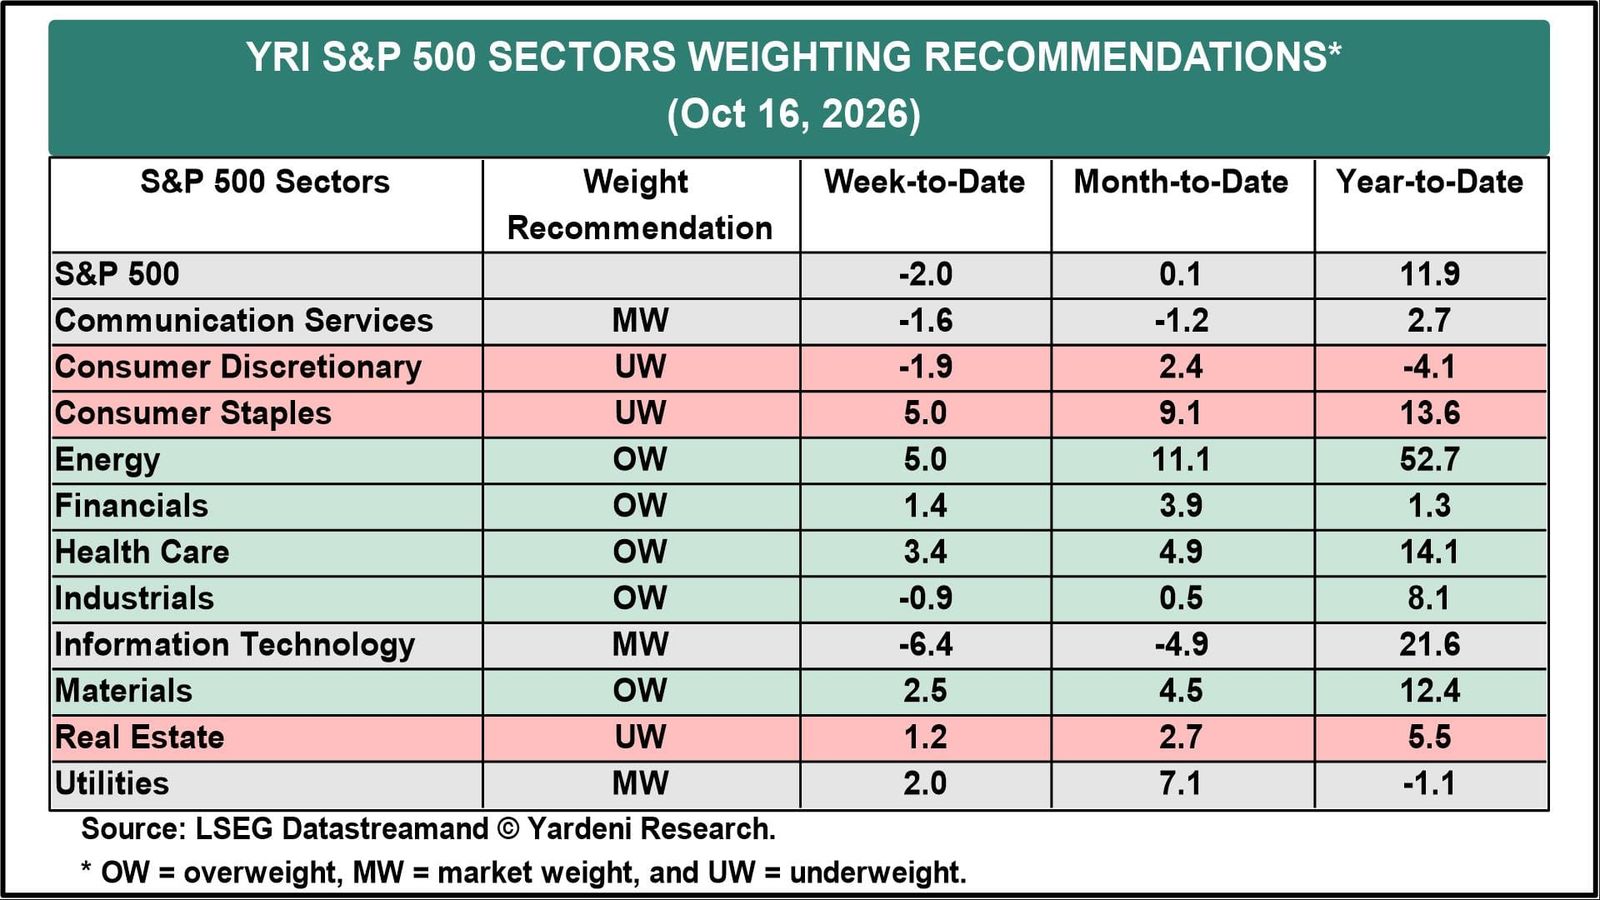
Here's more on Information Technology, Health Care, and Consumer Staples:
(1) Information Technology. The tech selloff last week was led by Semiconductor Equipment (down 17.4%) and Communication Equipment (down 13.3%) (chart). IT Consulting & Other Services rose 5.6%, and Technology Hardware slipped only 1.5%.
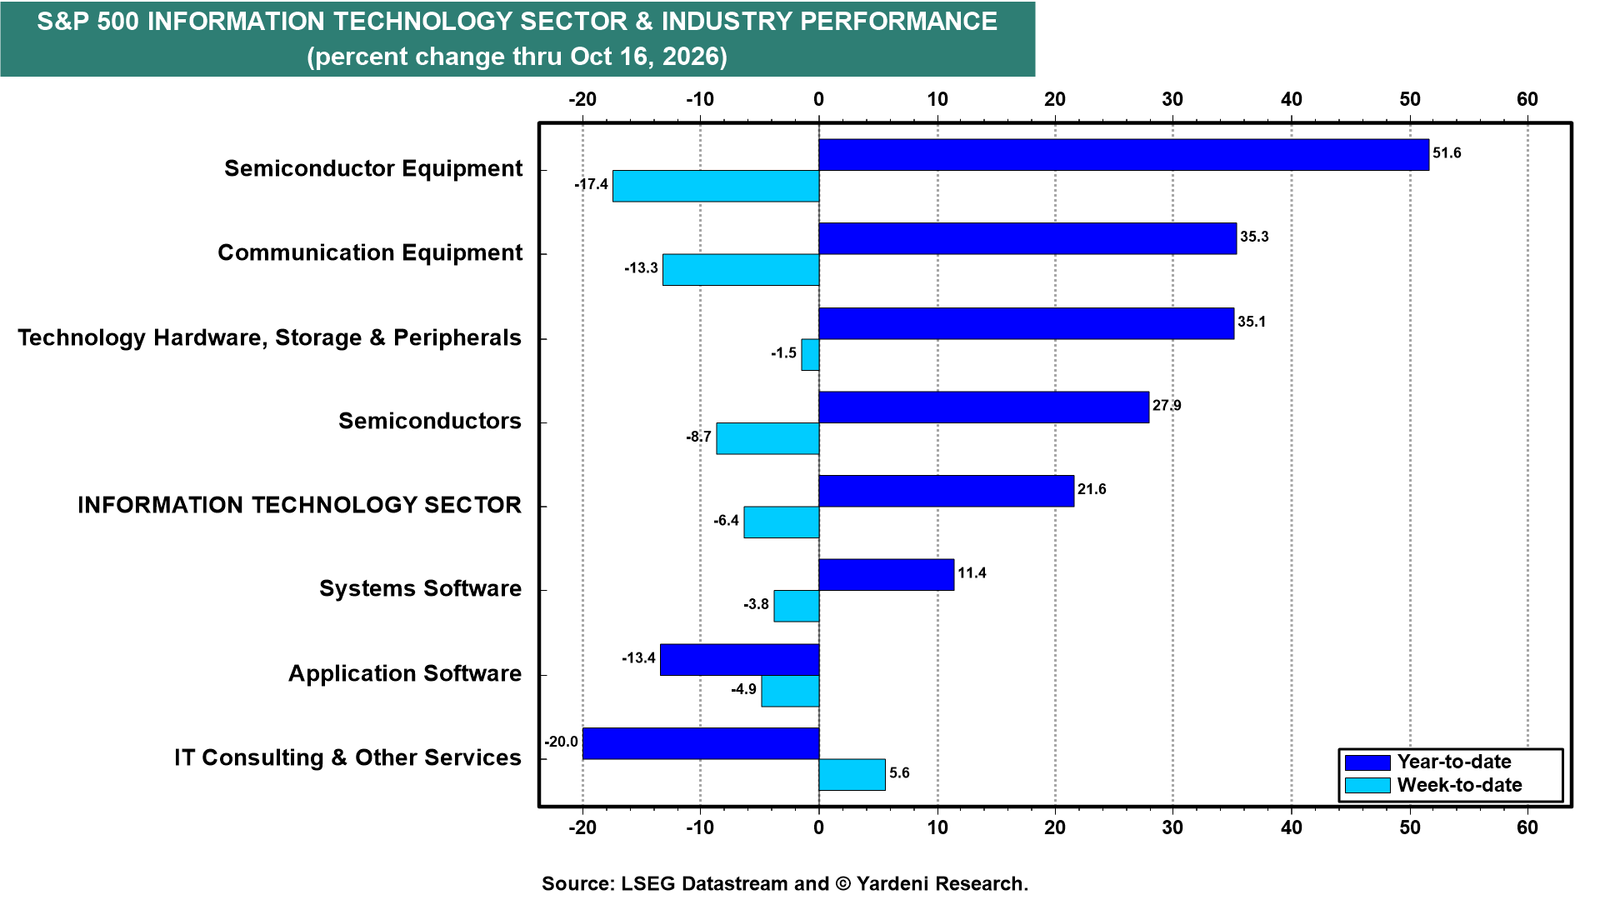
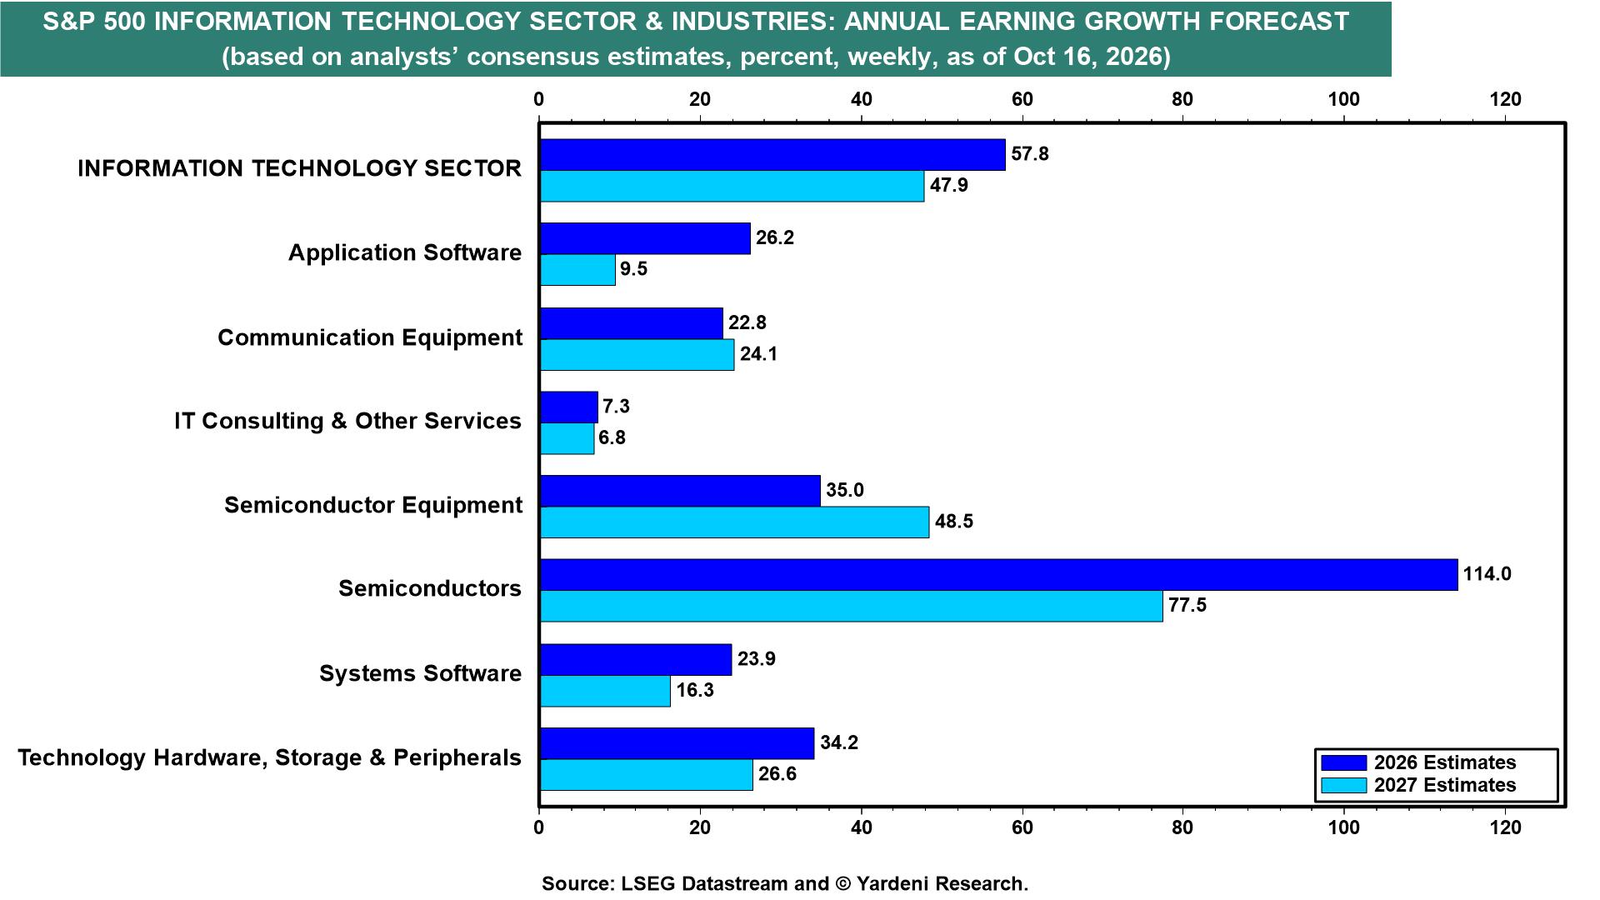
Two weeks ago, Semiconductor Equipment was the best-performing IT industry, up 97.3% ytd. It is now up 51.6%. Its forward P/E has fallen to 27.0 from 31.1. Its earnings outlook hasn't changed. Analysts still expect growth of 35.0% this year and 48.5% next year (chart).
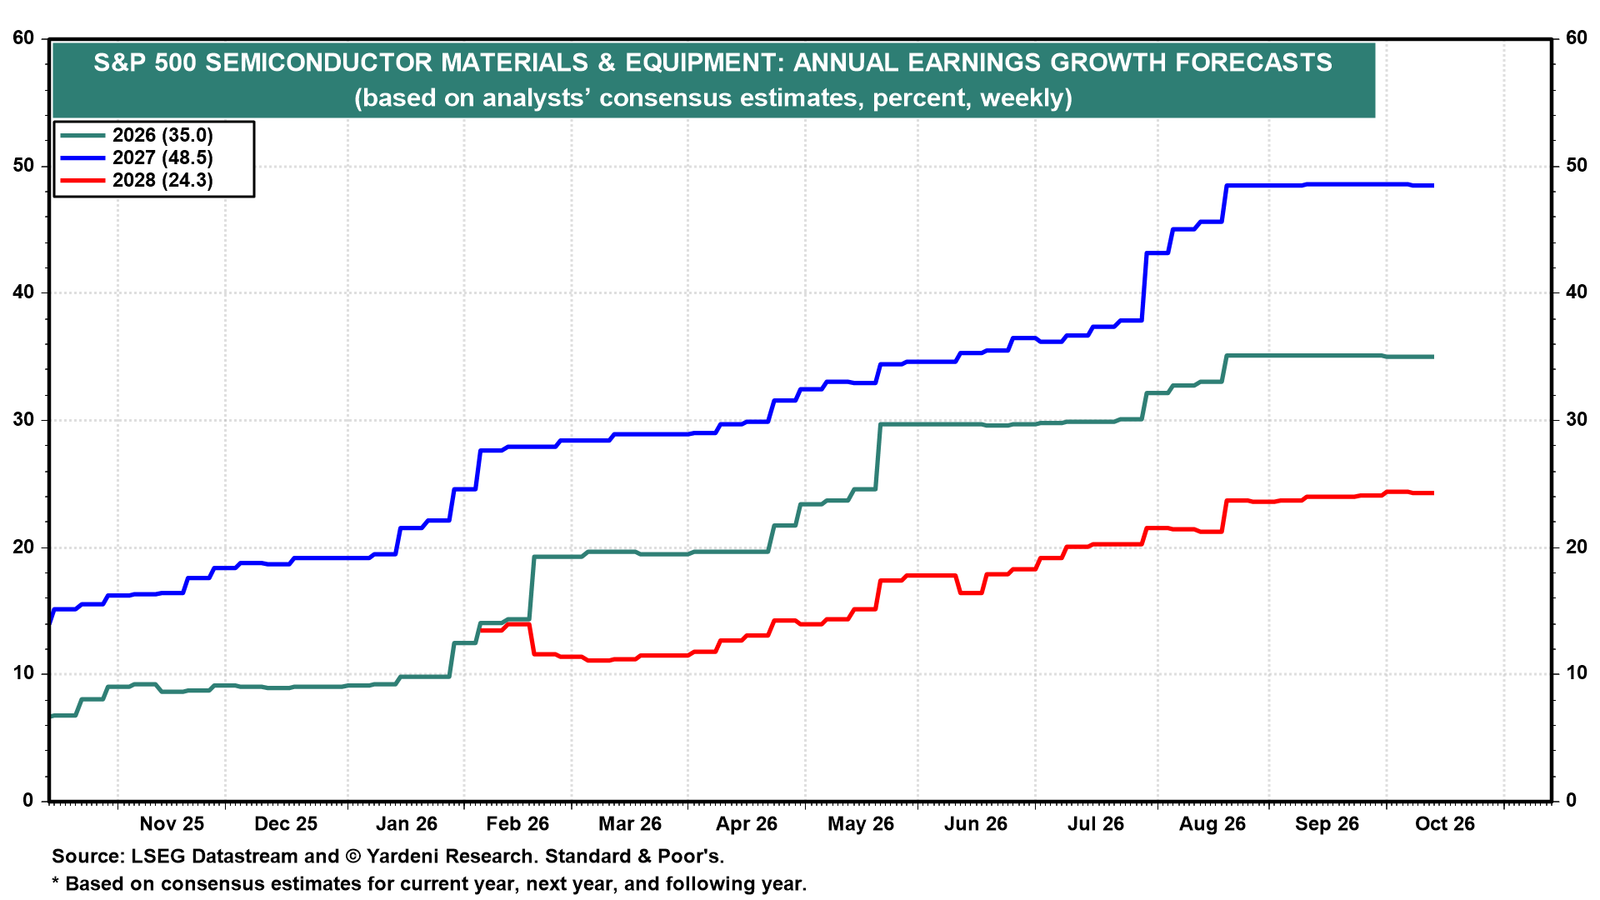
Semiconductor Equipment and Communication Equipment are the only IT industries for which analysts expect faster growth next year (chart).
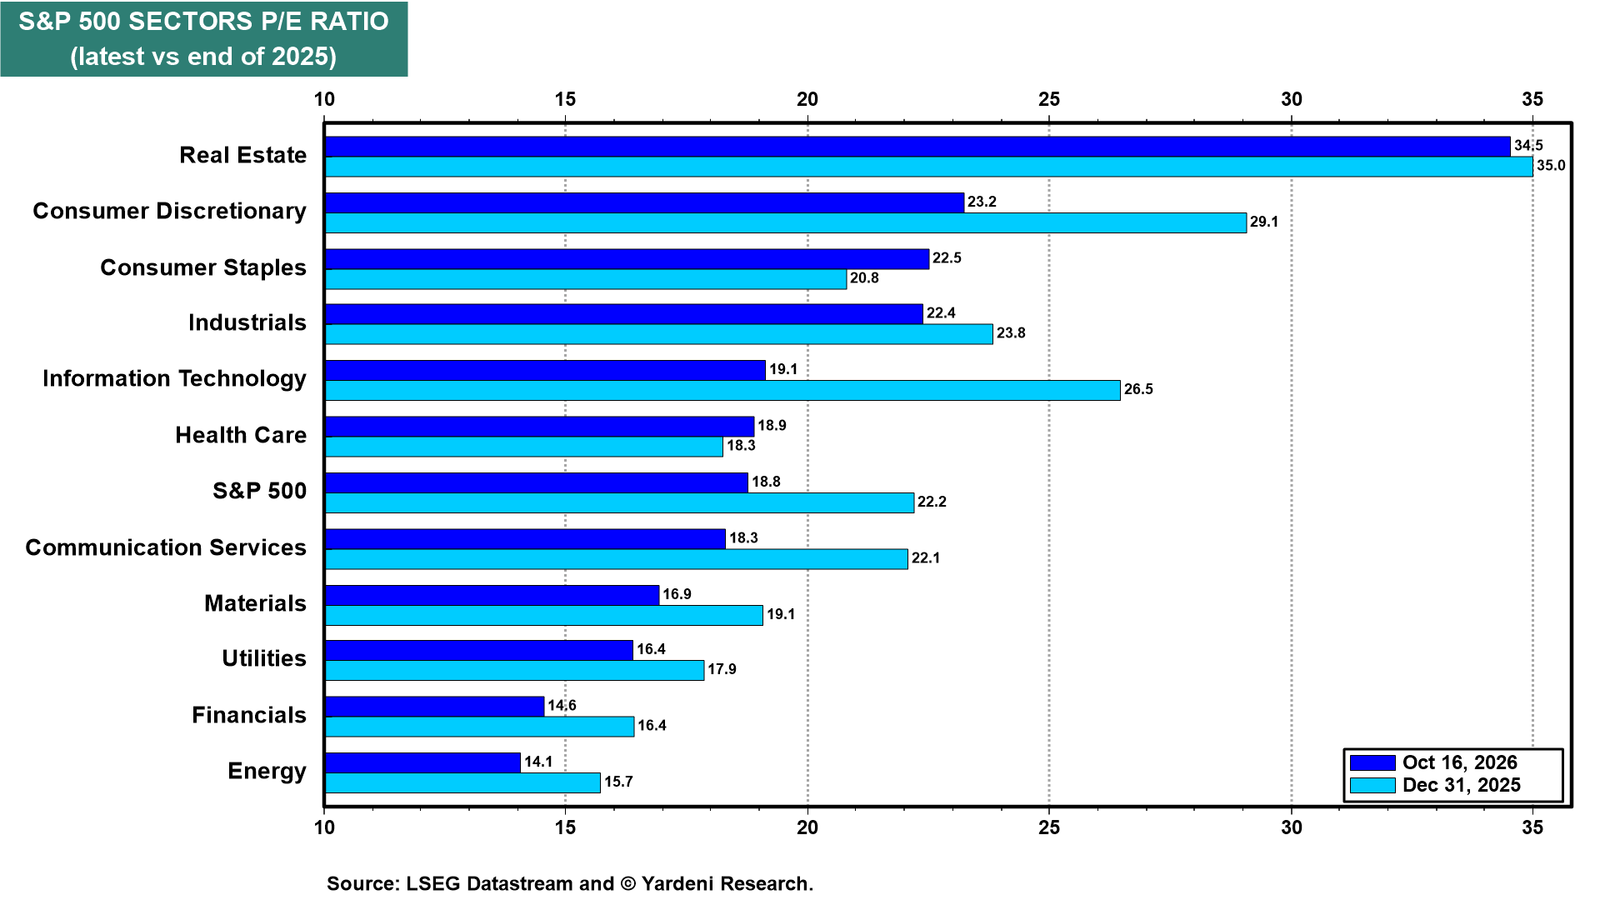
The selling hit the expensive industries. Semiconductor Equipment trades at 27.0 times forward earnings and Communication Equipment at 25.2. Semiconductors, the biggest contributor to IT's earnings, trades at a 14.7 multiple, below the S&P 500's 18.9 (chart). That is less than half its June 2024 peak of 35.5.
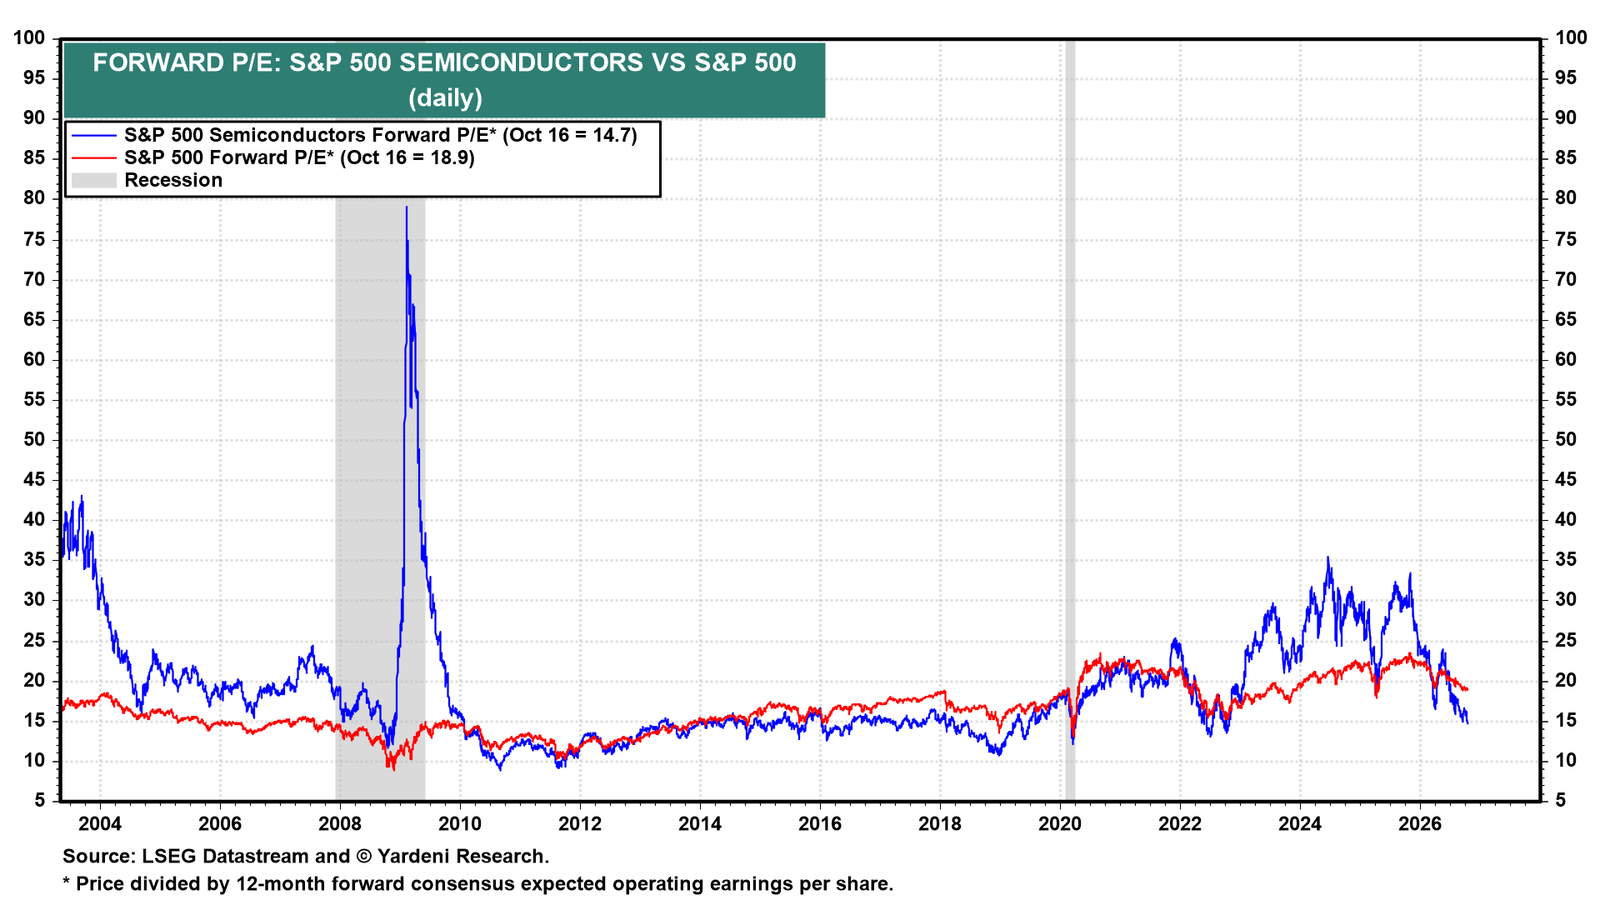
A low multiple can be a warning signal for a cyclical industry. Investors tend to pay the least when earnings are peaking and the most when they bottom. The industry's forward P/E reached 79.1 in February 2009, as earnings collapsed. So far, analysts are still raising their estimates. They expect earnings to grow 114.0% this year and 77.5% next year. As long as estimates keep rising, we see this week's semiconductor selloff as a buying opportunity. We retain our market weight rating on Information Technology.
(2) Health Care. Health Care rose 3.4% this week, and every industry gained. Health Care Distributors rose 16.1%. Even Health Care Equipment, down 16.3% ytd, rose 4.4%.
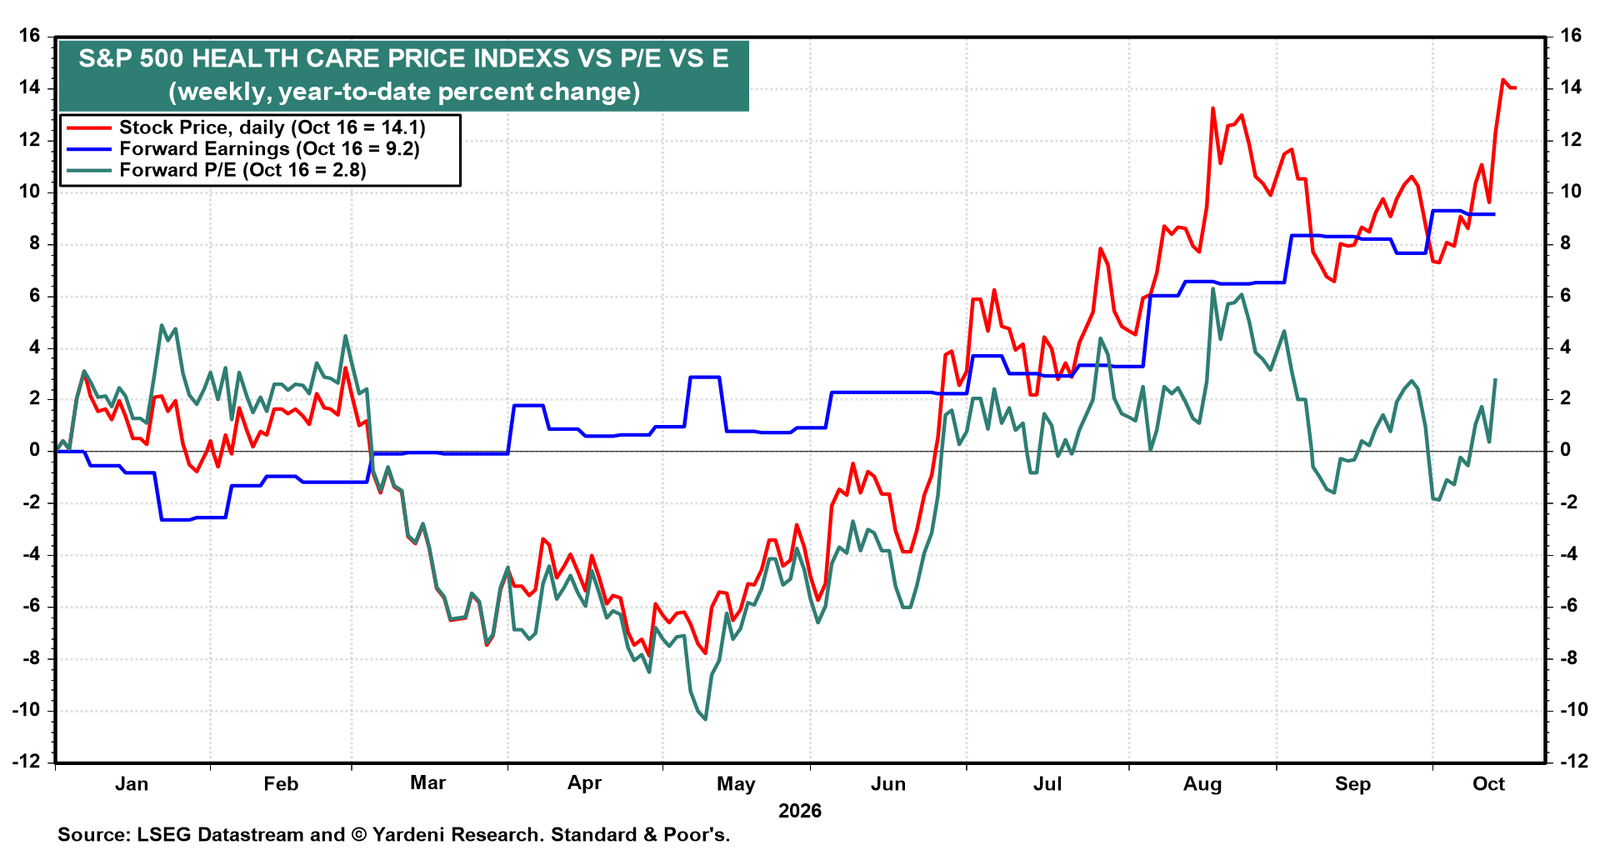
Earnings are doing the heavy lifting. In August, forward earnings and the forward P/E contributed about equally to the sector's ytd gain, at 6.6% and 6.3%, respectively. Forward earnings is up 9.2% ytd, while the forward P/E is up only 2.8%. The price index is up 14.1% (chart).
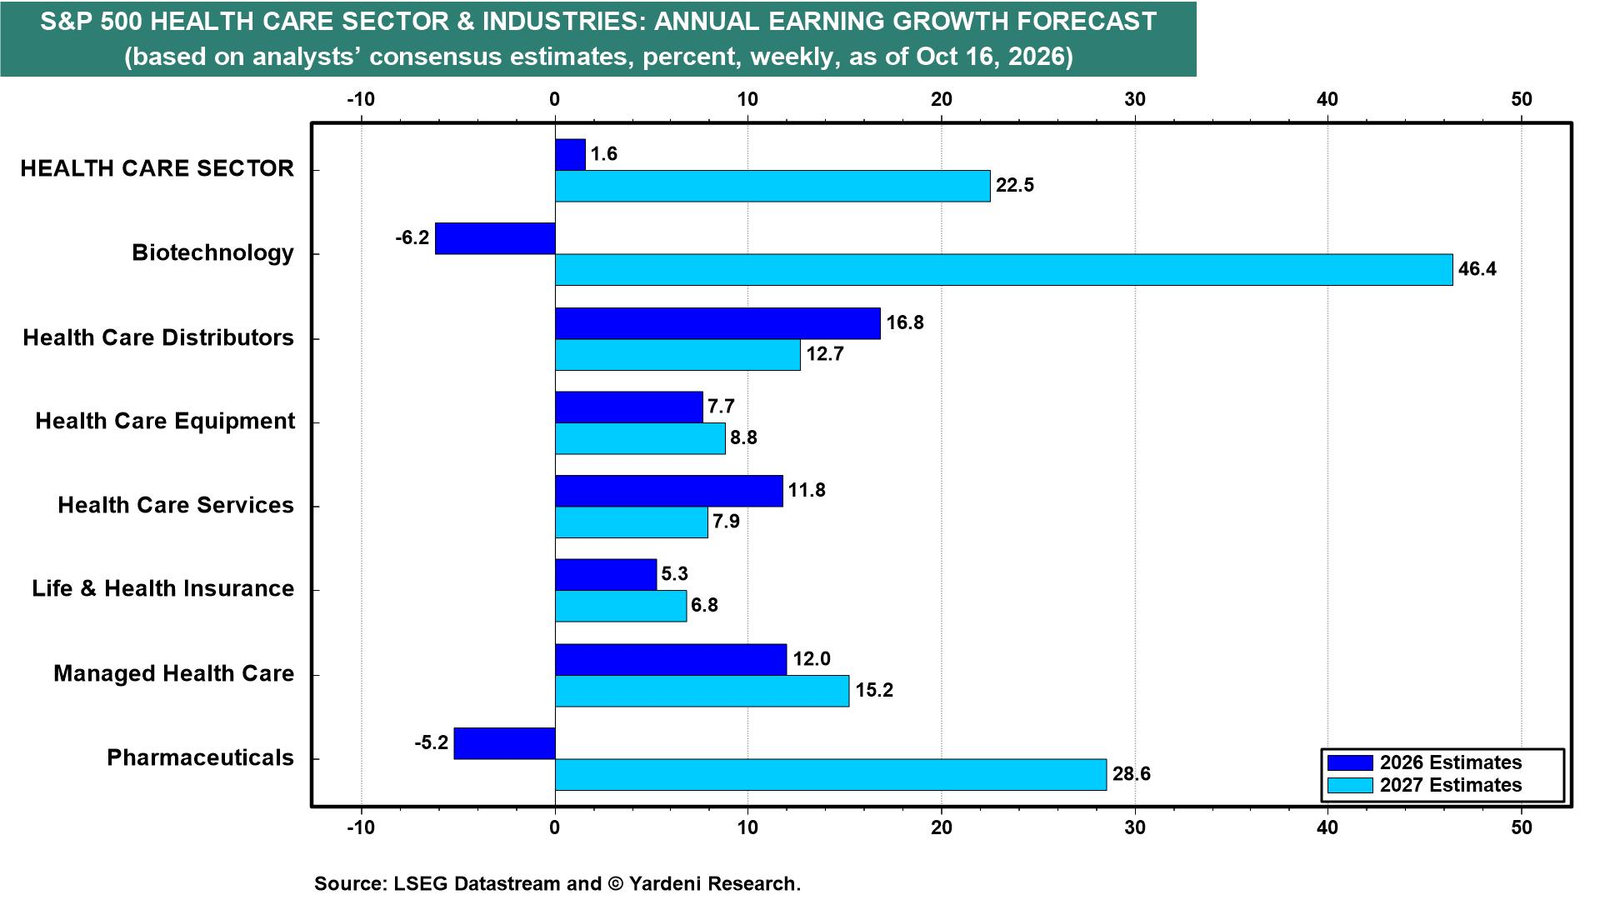
The best is ahead. Analysts expect the sector’s earnings to grow 1.6% this year and 22.5% next year. Pharmaceuticals' earnings are forecast to fall 5.2% this year and rise 28.6% next year (chart). Biotech is estimated to grow earnings 46.4% next year after falling 6.2% this year.
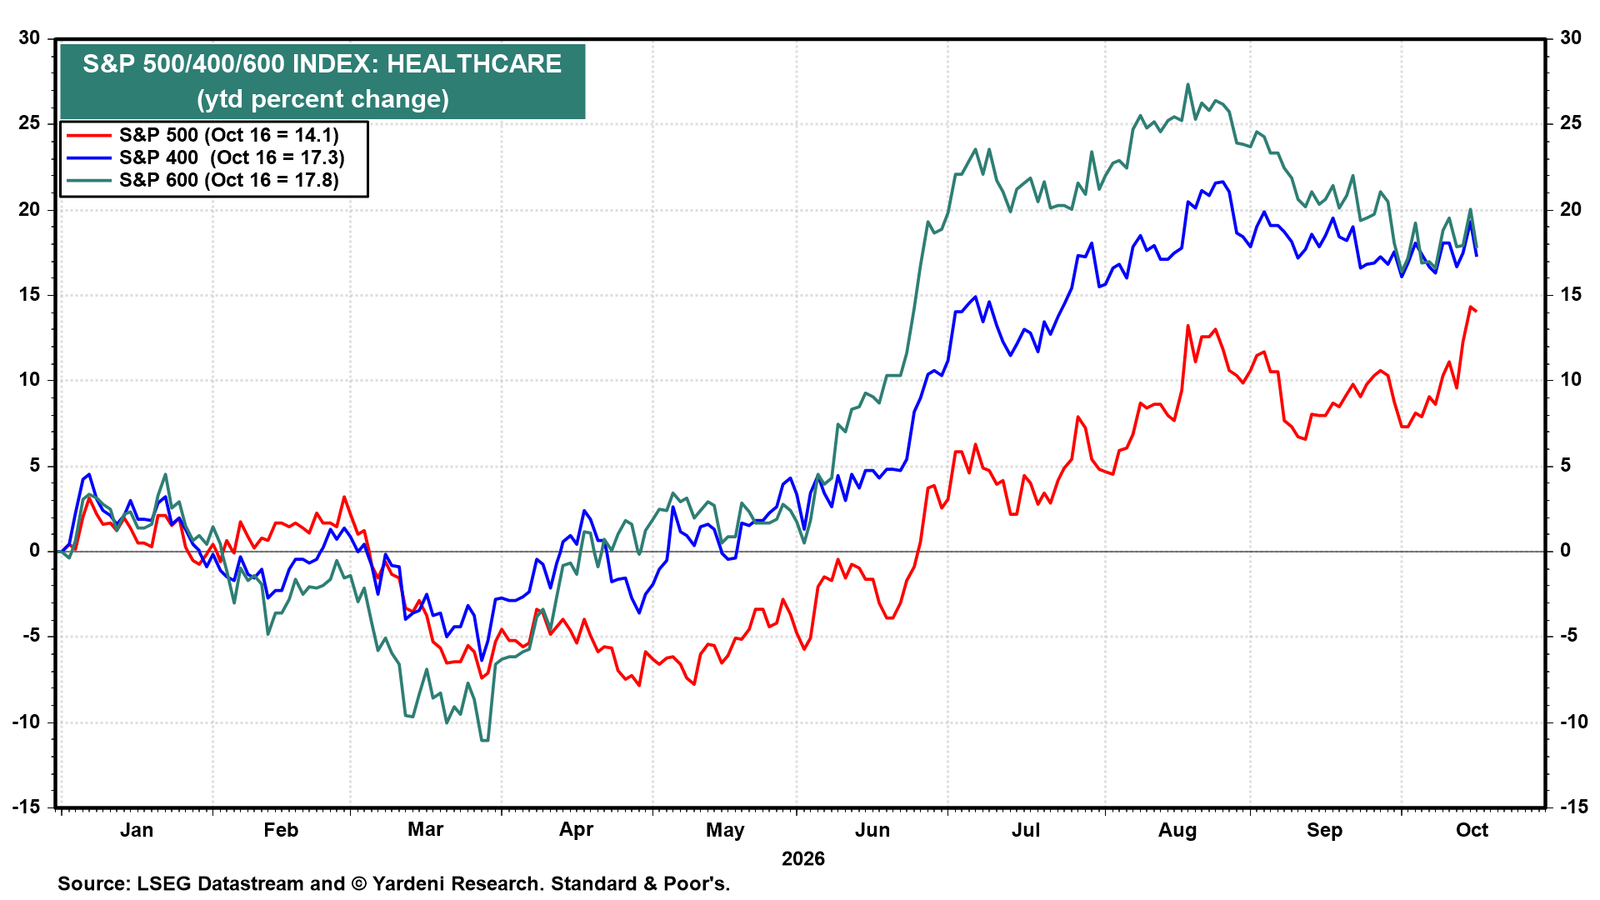
The large caps are catching up. On September 10, the S&P 500 Health Care index was up 6.7% ytd, against 20.6% for the S&P 600 and 17.2% for the S&P 400. The S&P 500 sector is now up 14.1%, versus 17.8% and 17.3% (chart). The sector trades at 18.9 times forward earnings, equal to the market multiple of 18.9. We retain our overweight rating on Health Care.
(3) Consumer Staples. Two weeks ago, we argued that earnings didn't justify Staples' valuation premium. Investors have since paid even more for the sector. Its forward P/E has risen to 22.5 from 20.7 on October 1. That is above both the S&P 500's 18.8 and IT's 19.1 (chart).
The multiple is doing the work again. Staples' forward P/E was down 0.3% ytd at the end of September. Two weeks later, it is up 6.5% ytd. Forward earnings is up 4.9% ytd and has barely moved since September (chart).
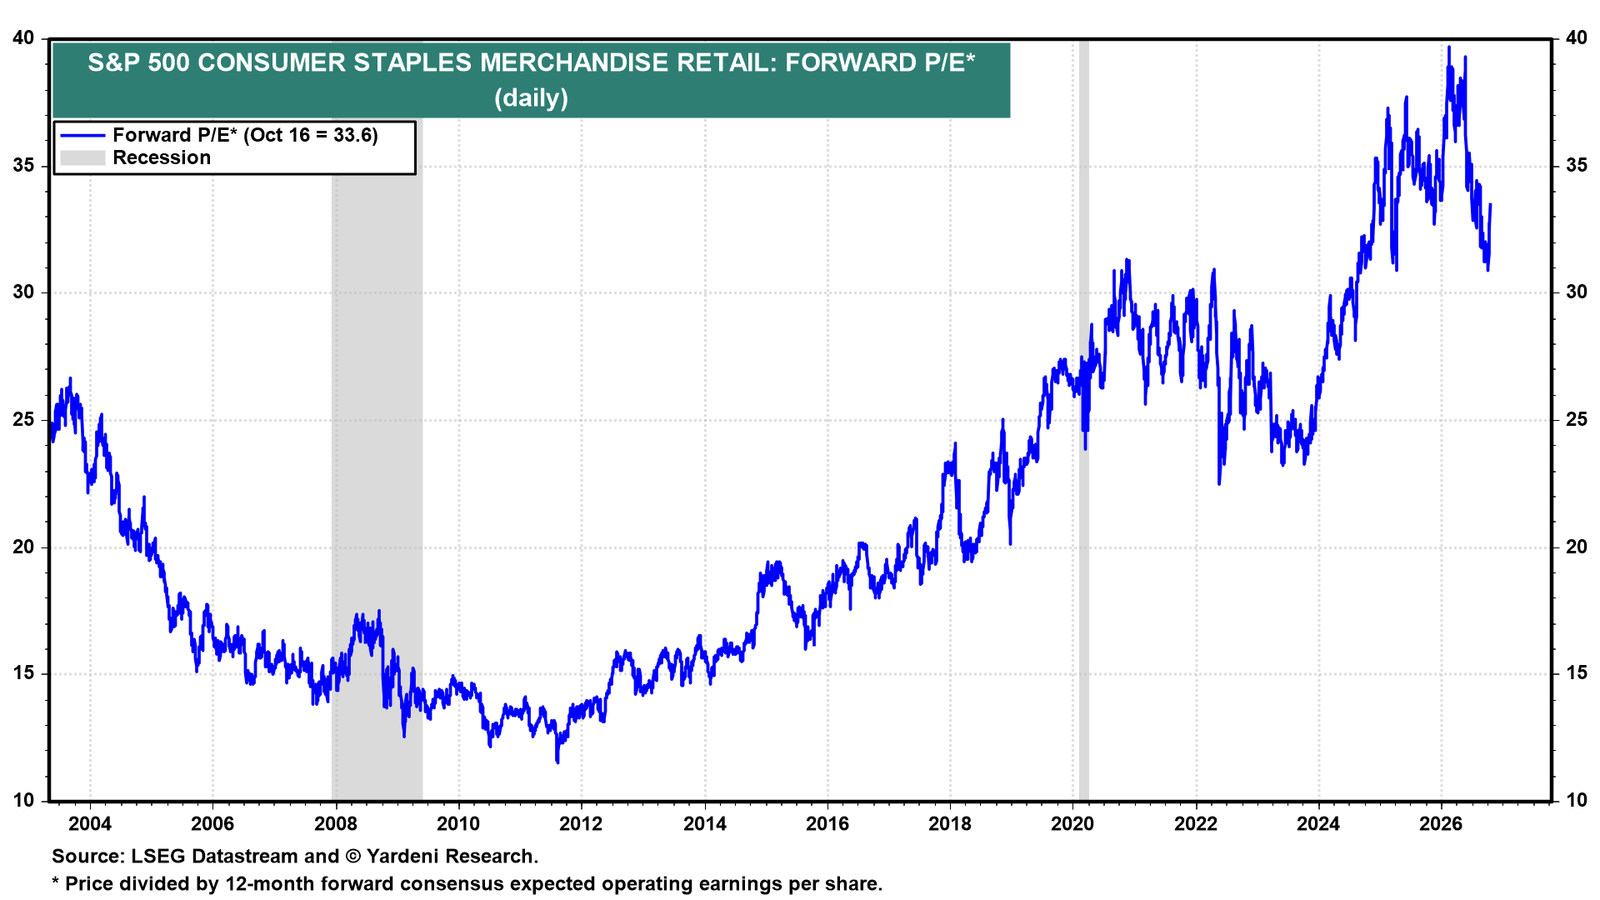
The priciest industry got pricier. Merchandise Retail's forward P/E rose to 33.6 from 31.0 two weeks ago, though its earnings growth is forecast to slow to 7.1% in 2027 (chart). This is a defensive bid, not an earnings story. We retain our underweight rating on Consumer Staples.