There was lots worrying investors last week, and there still is. But the stock market has a habit of climbing a wall of worry. It seems to be doing so now.
Investors have been watching analysts raising their earnings expectations faster than stock prices have been rising (chart). As a result, stocks have gotten cheaper, assuming that analysts' exuberant earnings expectations are rational. Investors may be coming around, gaining more confidence in FEMO (i.e., fabulous earnings momentum).
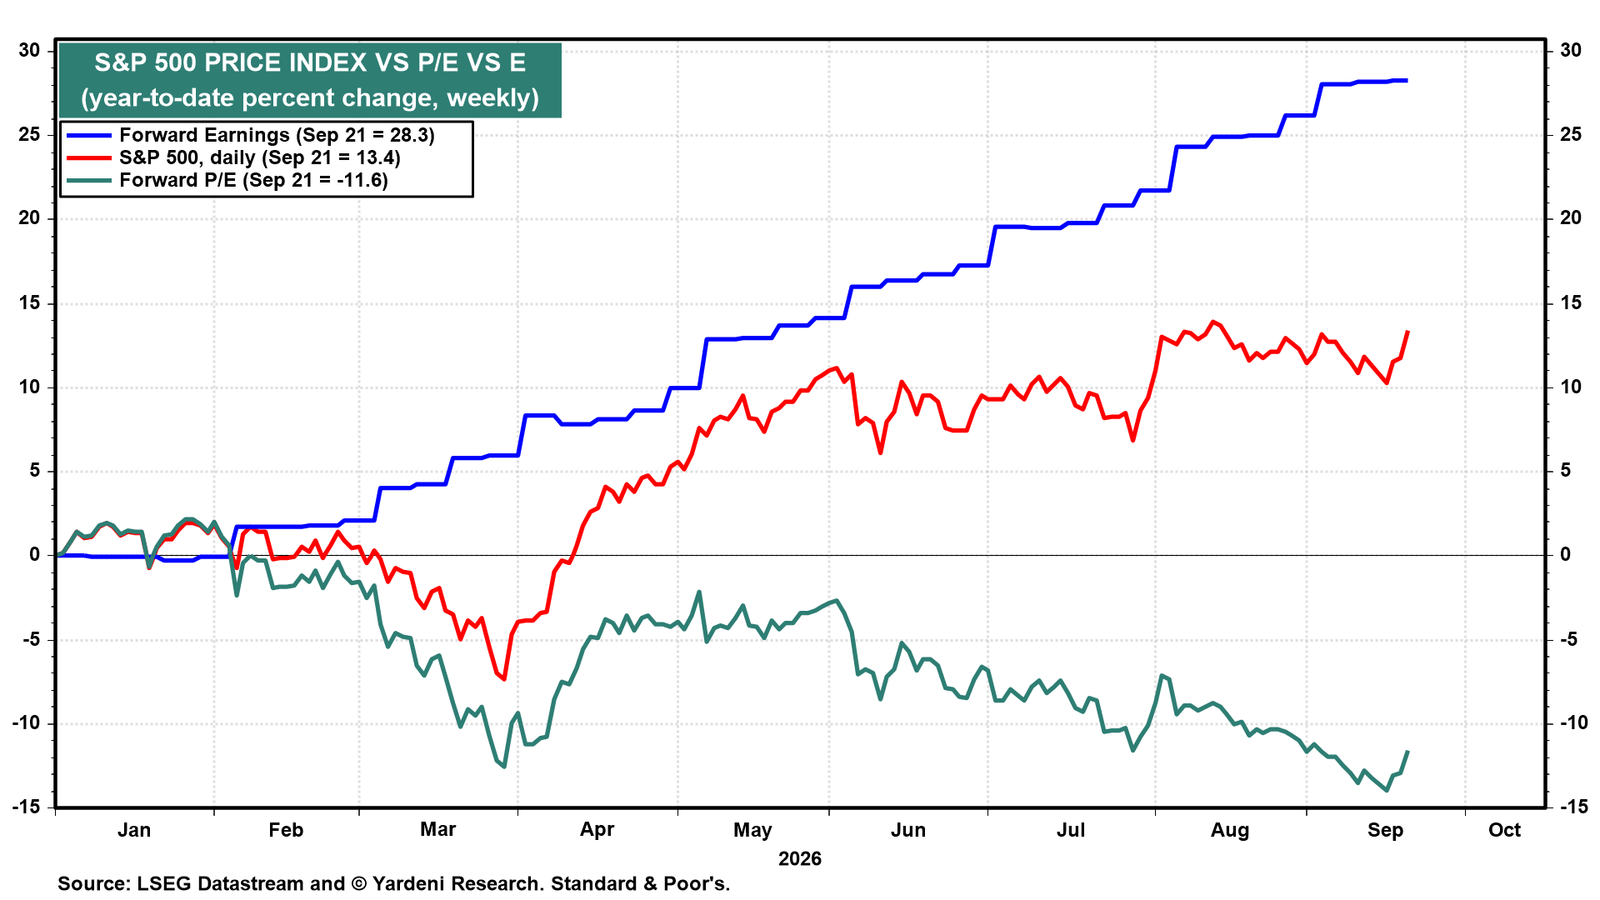
If the forward P/E of the S&P 500 has bottomed and starts moving higher again, it will be because the price index is rising faster than forward earnings.
In particular, investors may be rethinking the valuation of the S&P 500 Information Technology and Communication Services sectors, especially the Magnificent-7 and the S&P 500 Semiconductor industry. They've all gotten cheaper on a forward P/E basis, as analysts' earnings expectations have outpaced their stock prices (charts).
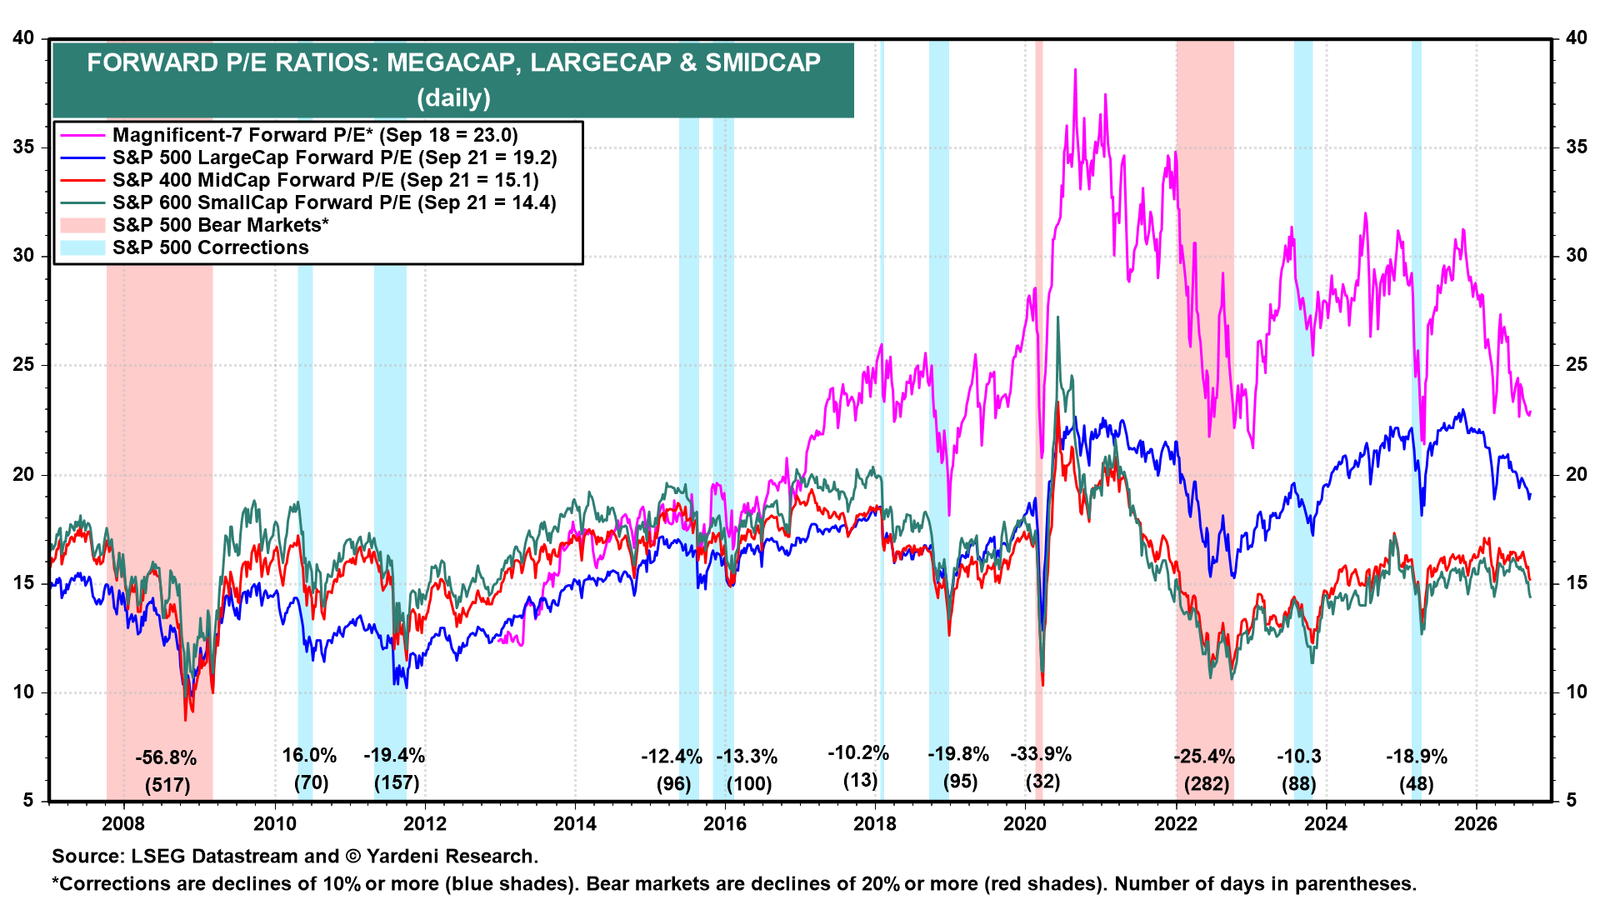
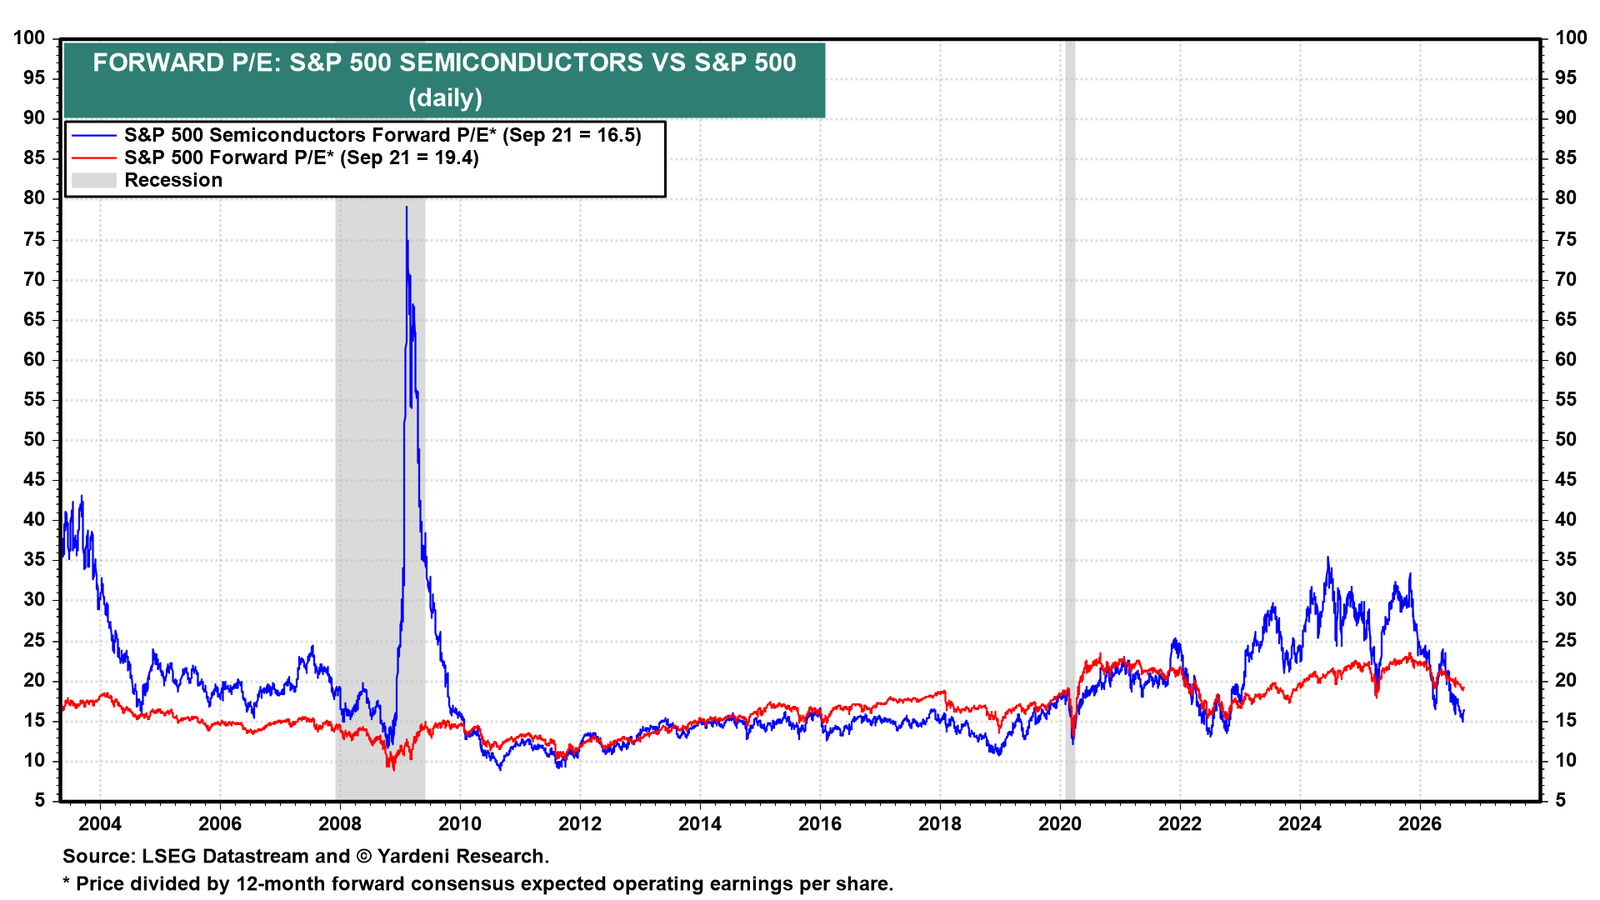
Let's have a closer look at related recent developments:
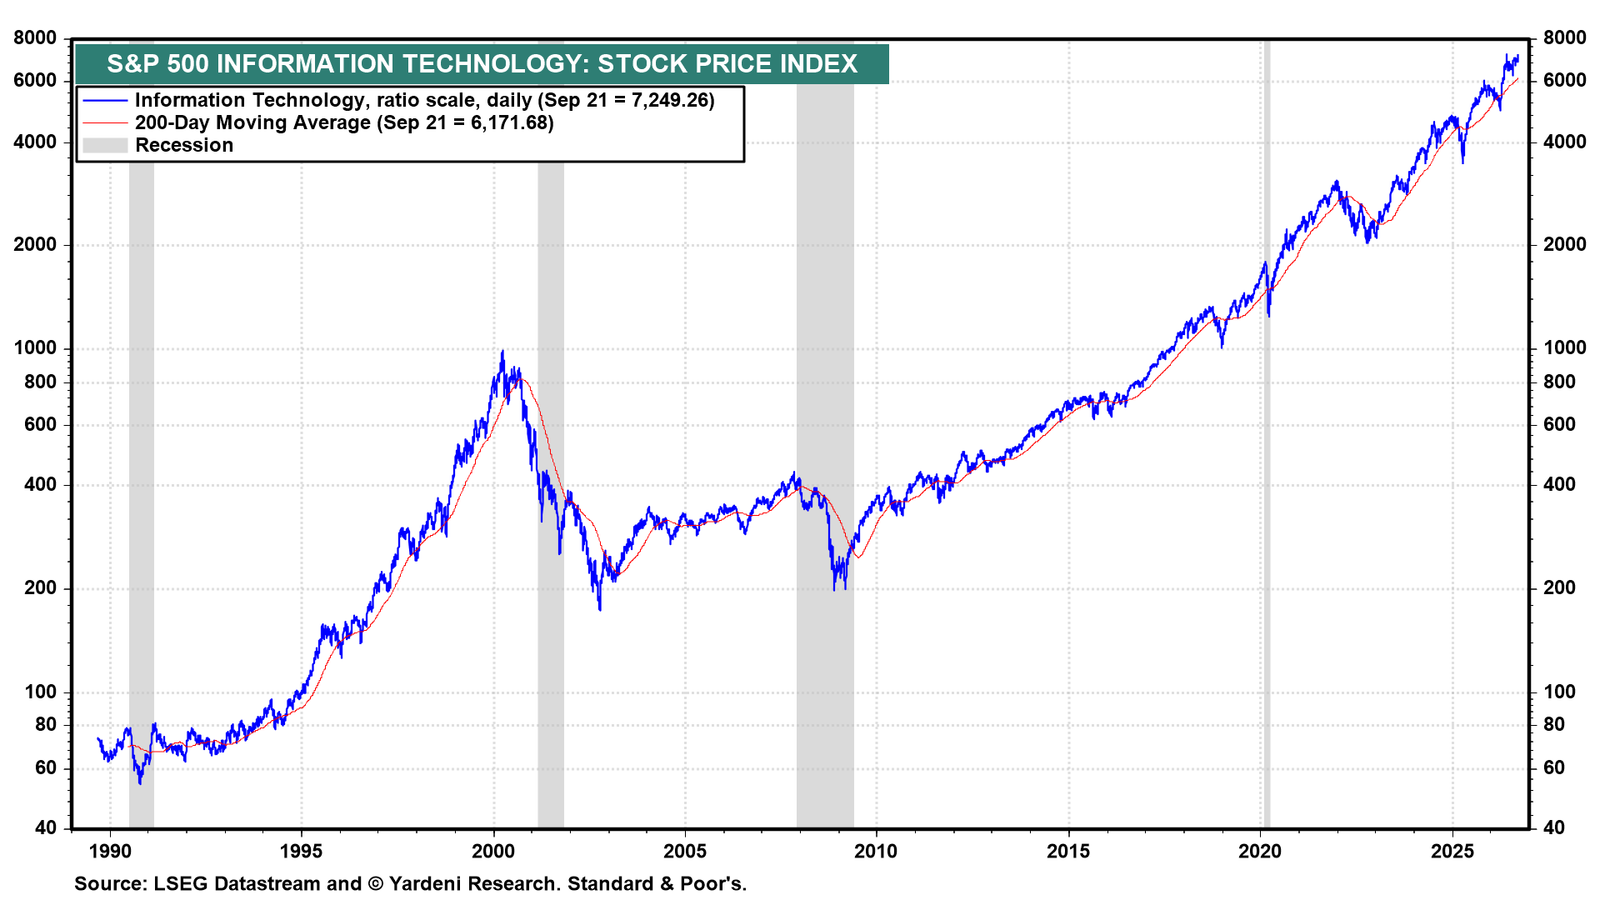
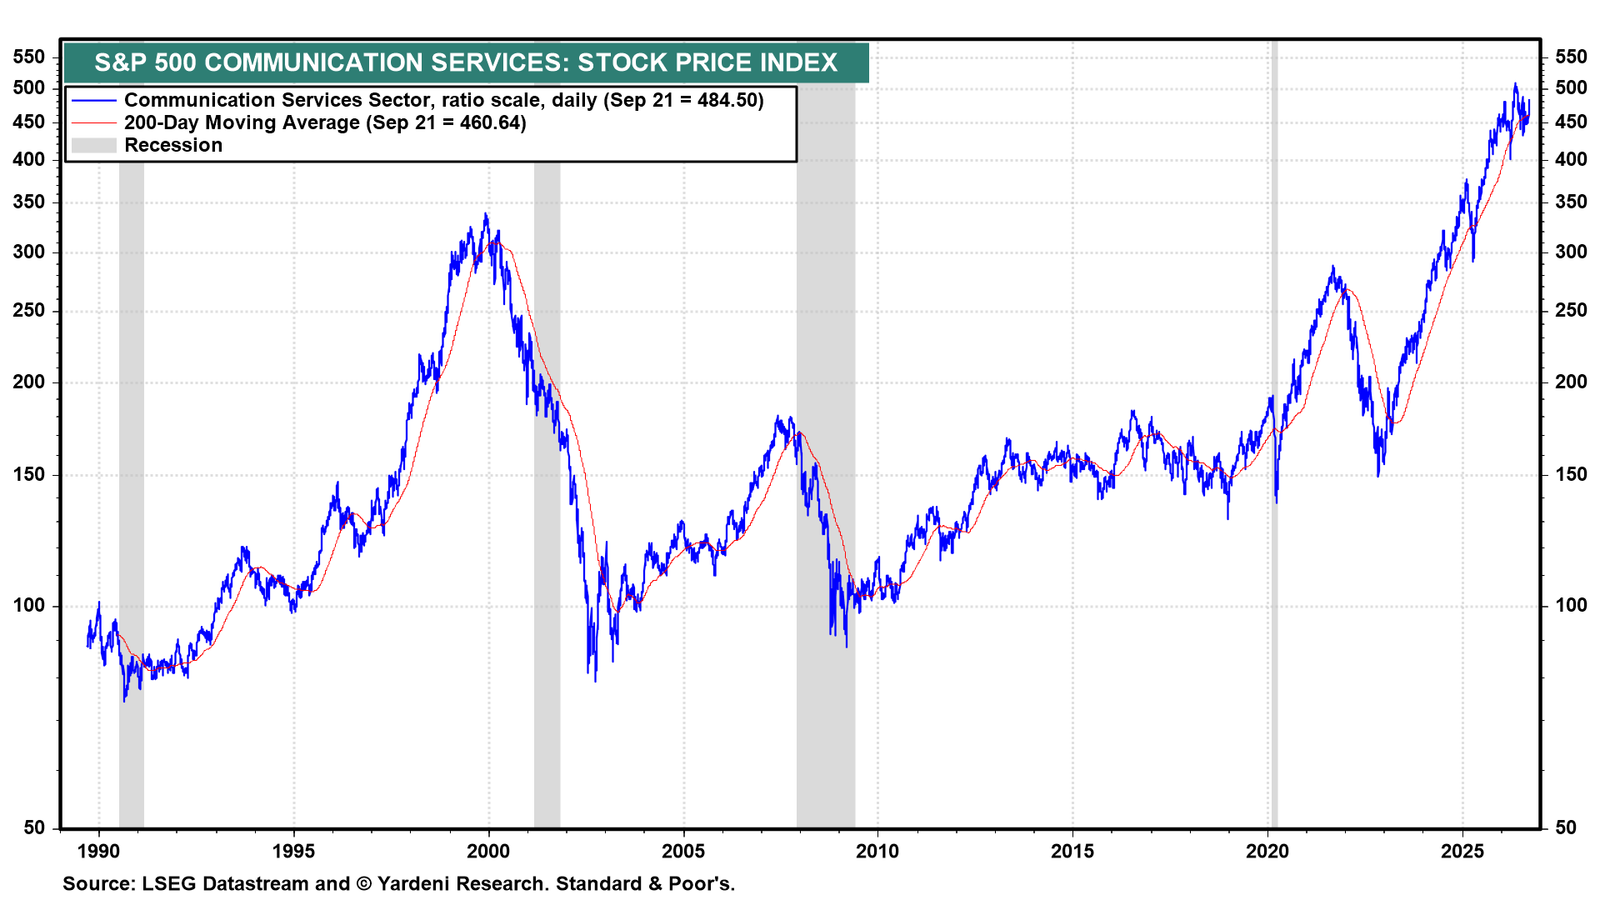
(1) The price of Brent crude oil fell below $100 a barrel today. The 10-year Treasury bond yield stabilized just below 5.00%. So the path of least resistance was higher for the S&P 500, which closed at 7,764.70, just 0.4% below its record high of 7,798.99 on August 13. The Information Technology and Communication Services sectors led the S&P 500 higher today (charts). The Nasdaq rose to a record high.
The Magnificent-7 ETF was down ytd through late July (chart). It has rebounded to a record high and is up 10.6% ytd.
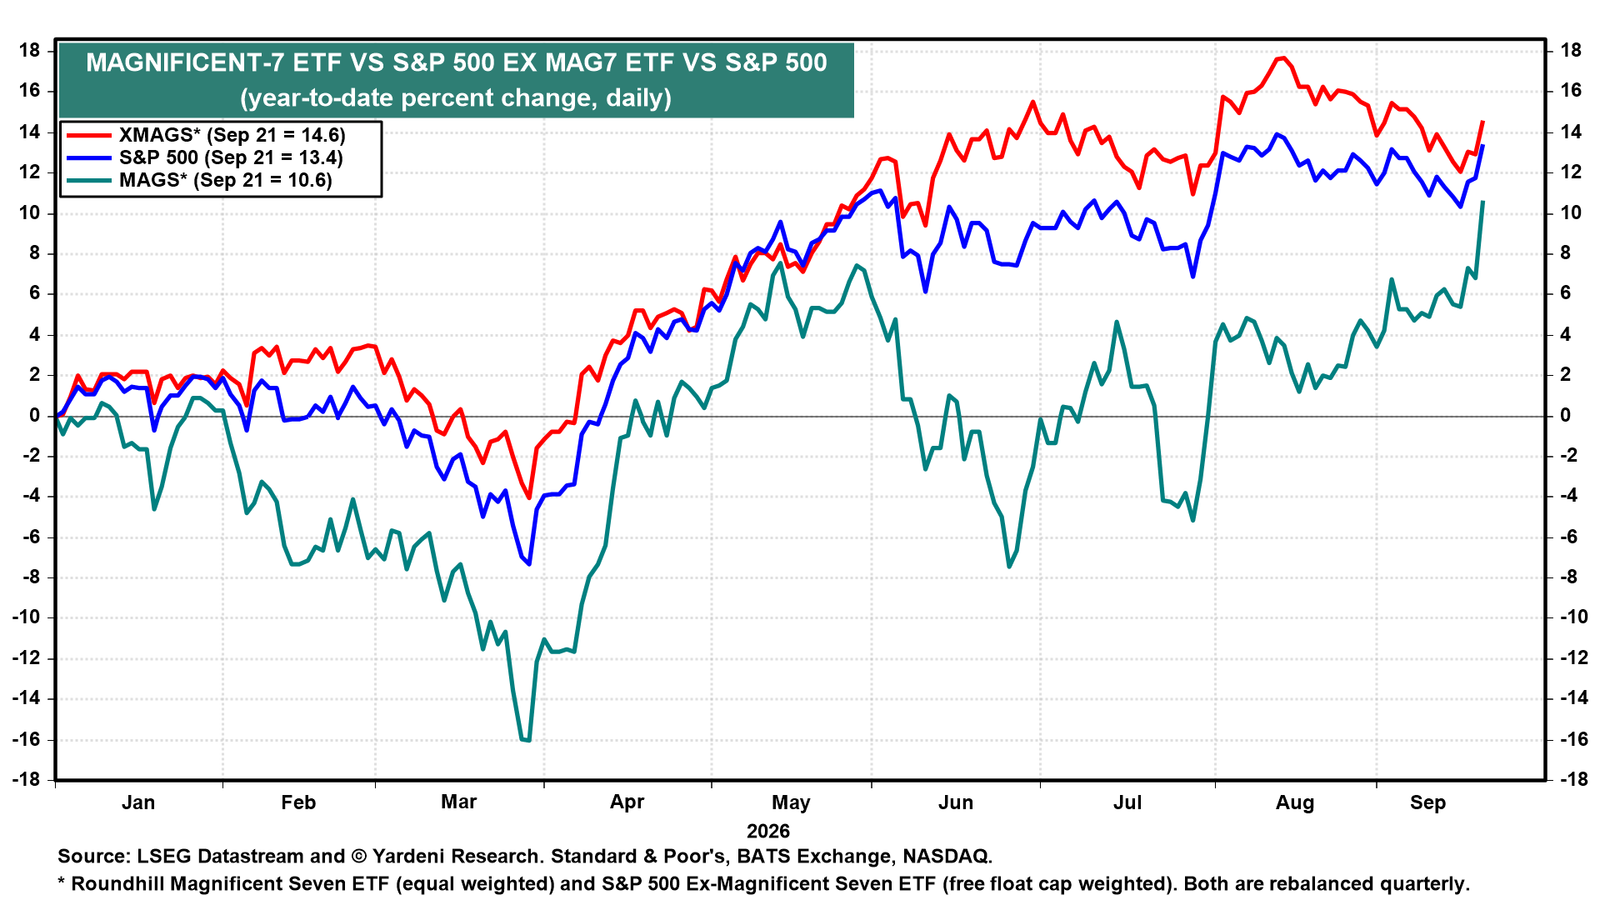
(2) That's impressive given all the recent commotion about AI, with plenty of bad press about how AI will kill humans. Investors clearly are betting that AI is here to stay, that it will be a very profitable business, and that it won't kill them. Rather than trying to pick the winners and losers in the AI race, investors are probably buying ETFs that offer diversified portfolios of companies exposed to the AI business.
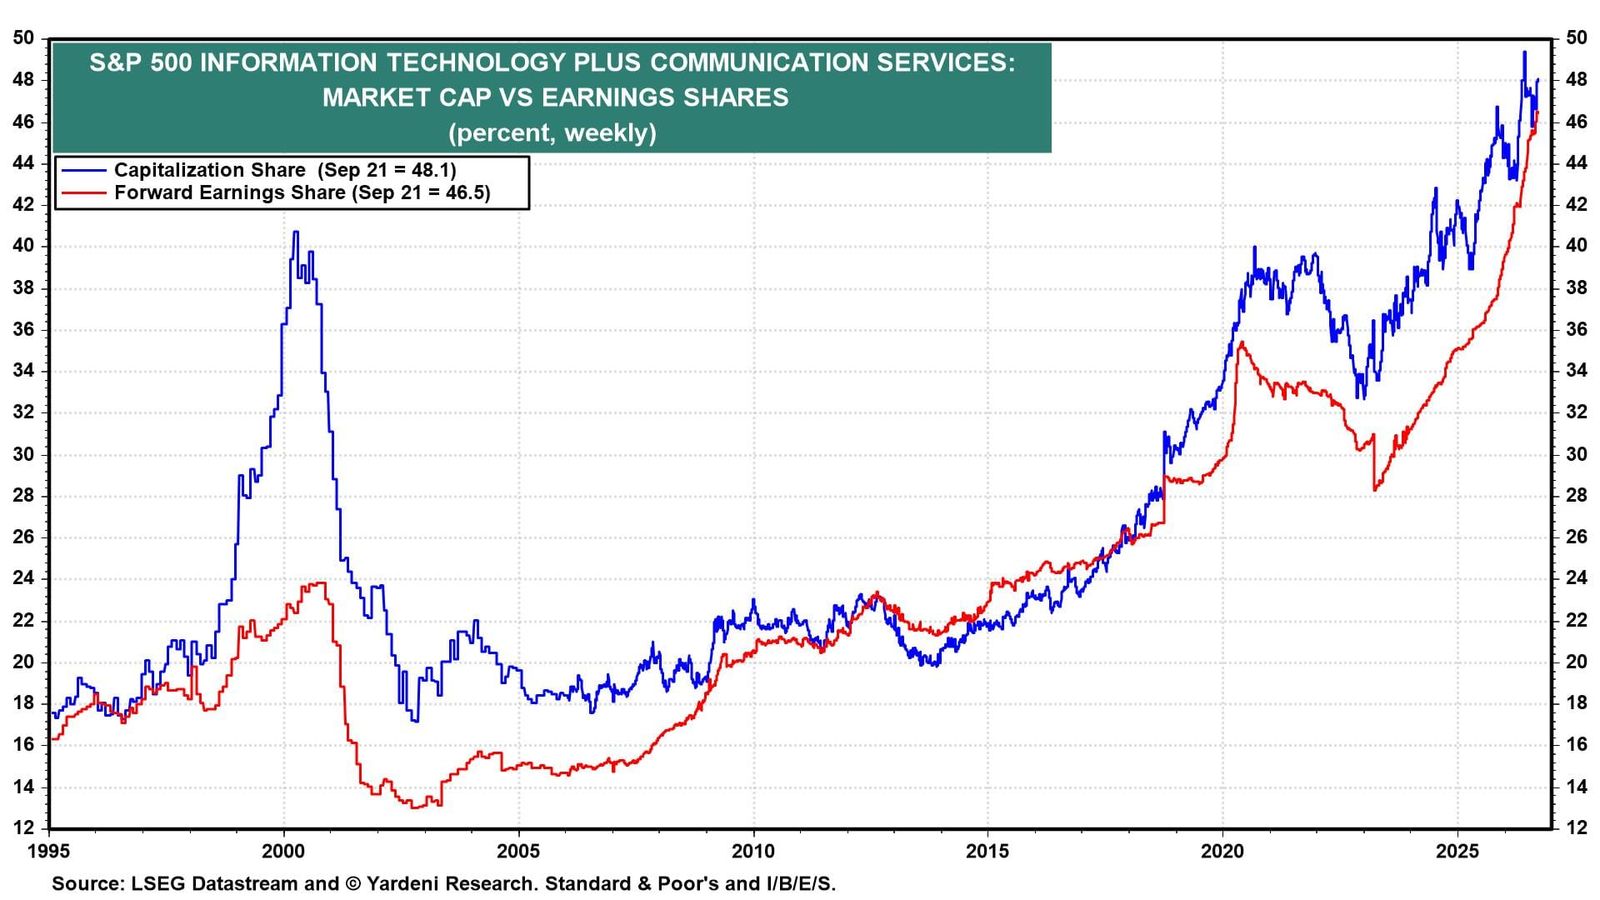
(3) Information Technology and Communications Services together account for a near-record 48.1% of the S&P 500's market capitalization (chart). And they account for nearly as great a share of the S&P 500’s forward earnings, at a record 46.5%!
Their aggregate forward earnings rose to a record $1.6 trillion during the week of September 18 (chart).
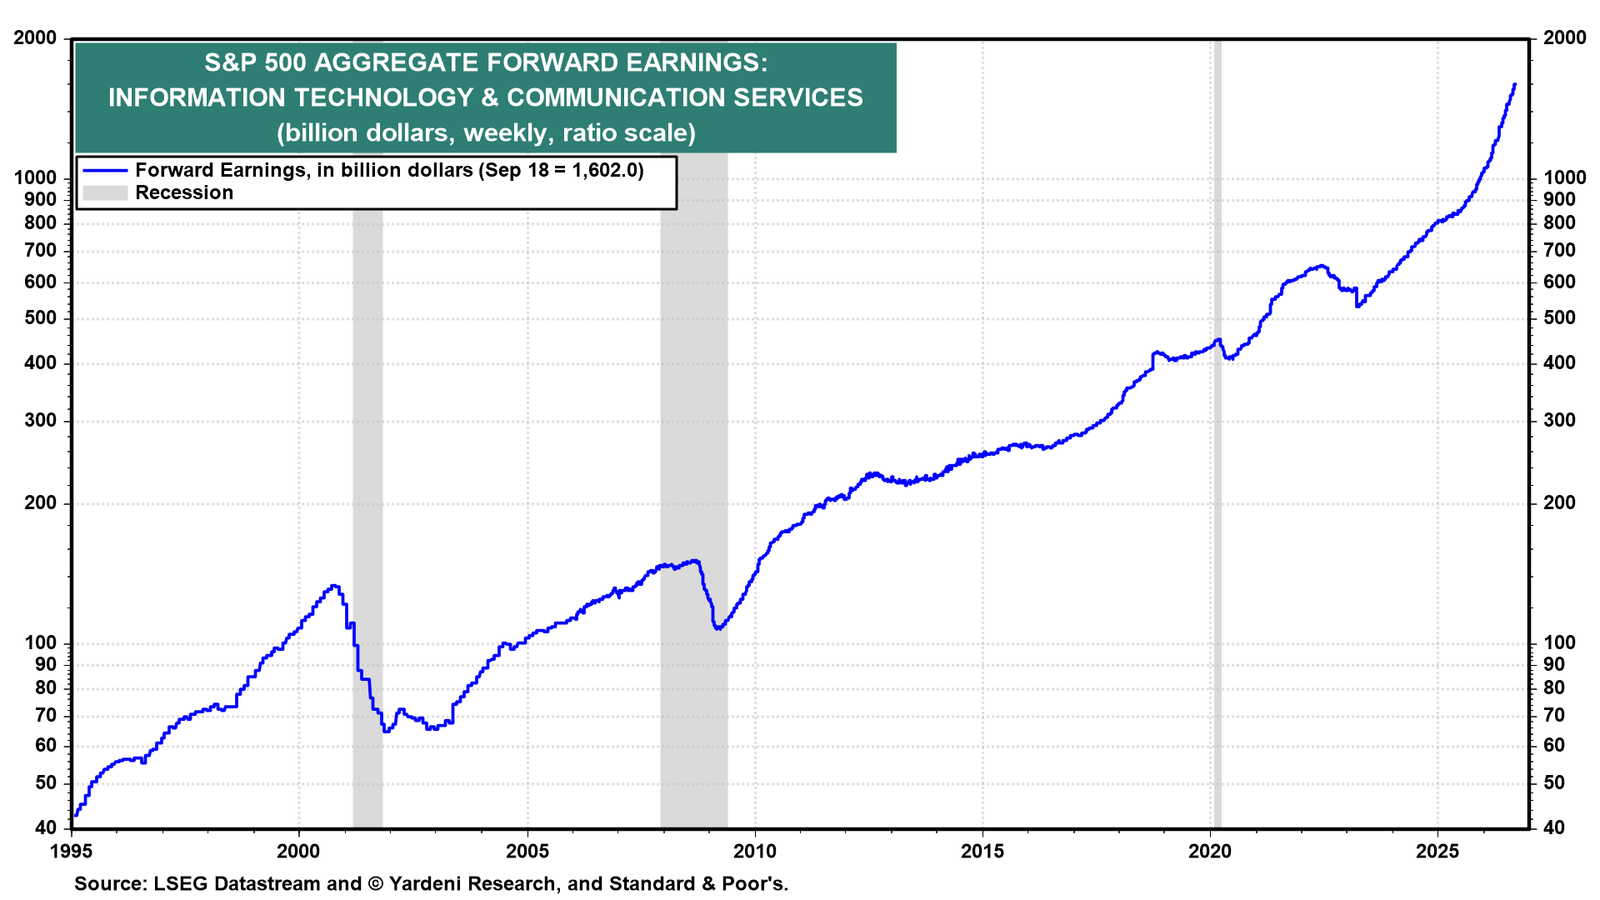
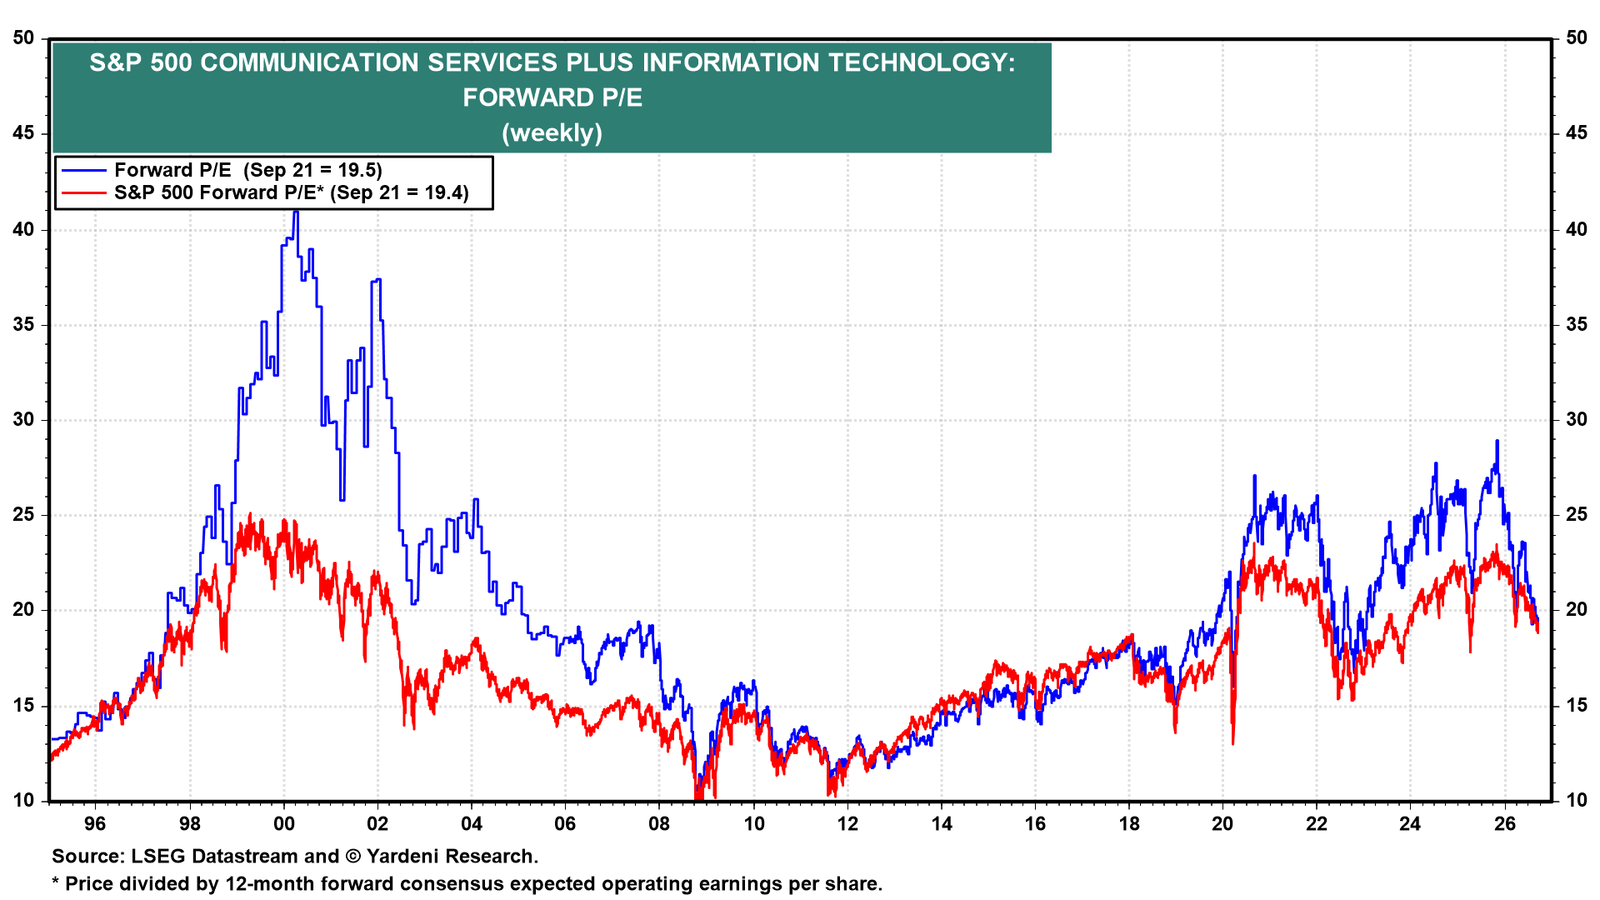
Fears of another 1999 Tech Bubble followed by a Tech Wreck have been blown away by the drop in the two sectors' combined forward P/E from 29.0 late last year to 19.5 currently, as earnings expectations rose faster than the sectors' stock price index (third chart above). In other words, the sectors are relatively cheap, especially given their rapid earnings growth.
(4) We are sticking with our recommendation to market-weight the two sectors simply because they already account for almost half of the S&P 500's market cap and earnings.
(5) What about our new year-end targets of 7,900 by the end of the year and 8,400 by the middle of next year? We will stick with them for now. Our message hasn’t changed: It's a bull market. Our Roaring 2020s target of 10,000 by the end of 2029 remains intact. It could arrive ahead of schedule if investors decide to pay higher valuation multiples for FEMO. Nevertheless, we will continue to update our worry list, as we did last week.