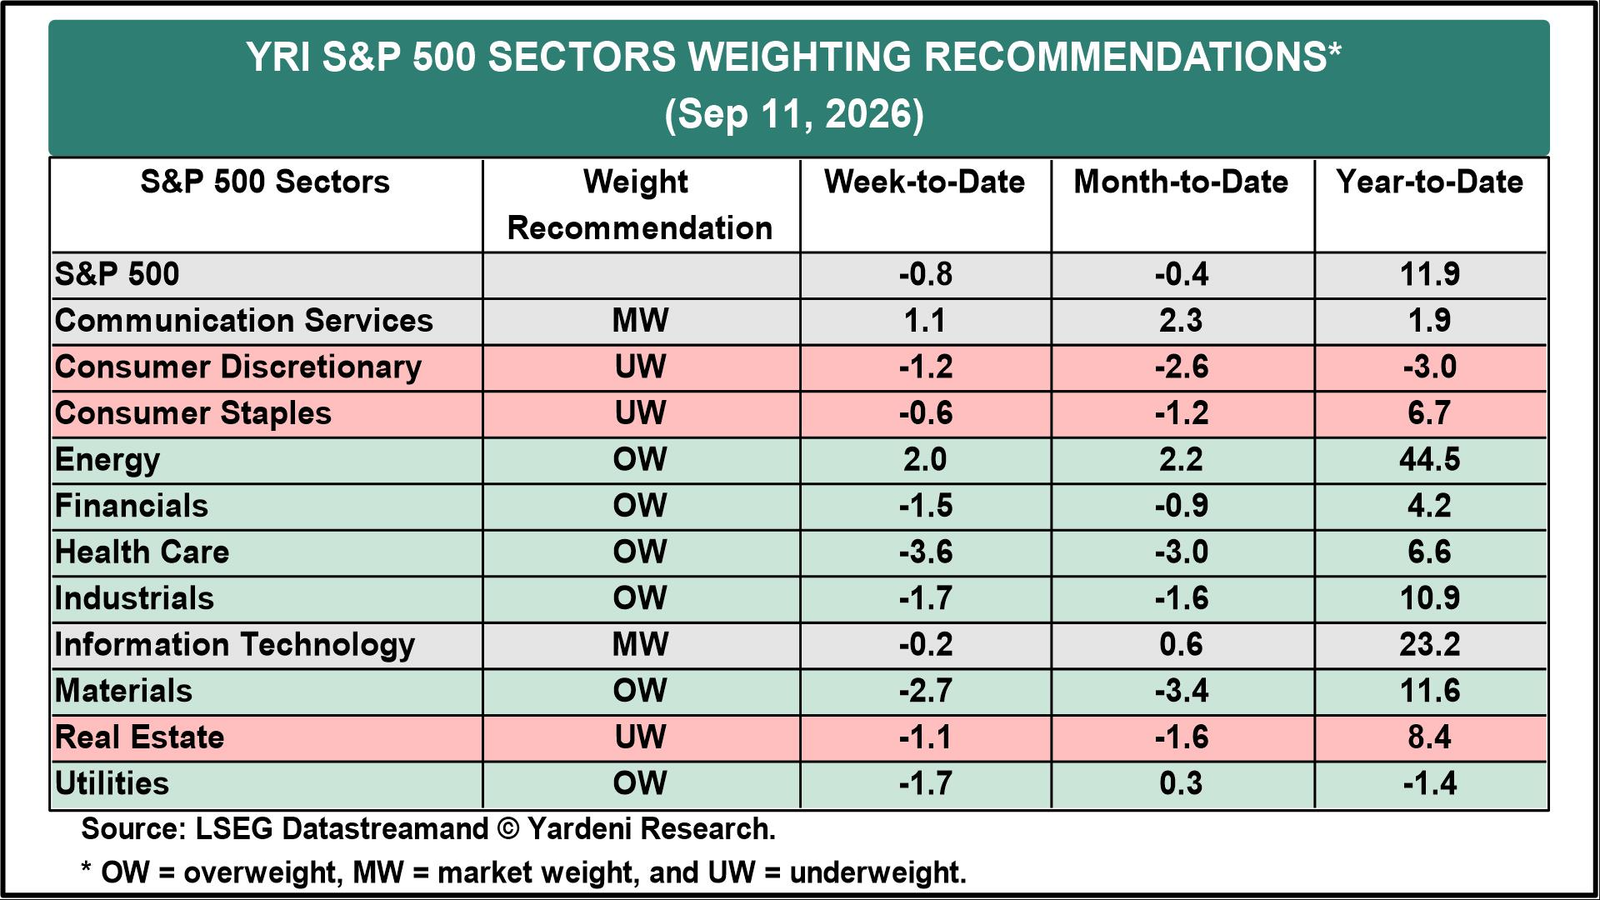
Rising bond yields and oil prices weighed on stocks last week, though a mostly in-line CPI report on Friday sparked a rebound. The S&P 500 still fell 0.8%, with nine of the 11 sectors declining. Energy (OW) led, rising 2.0%, and it tops the sector derby at 44.5% ytd. Communication Services (MW) was the only other gainer, up 1.1%. Health Care (OW) fell the most at 3.6%. Information Technology (MW) was nearly flat at -0.2% and is up 23.2% ytd, with fundamentals that continue to improve.
Let's take a closer look at Energy, Information Technology, and Health Care:
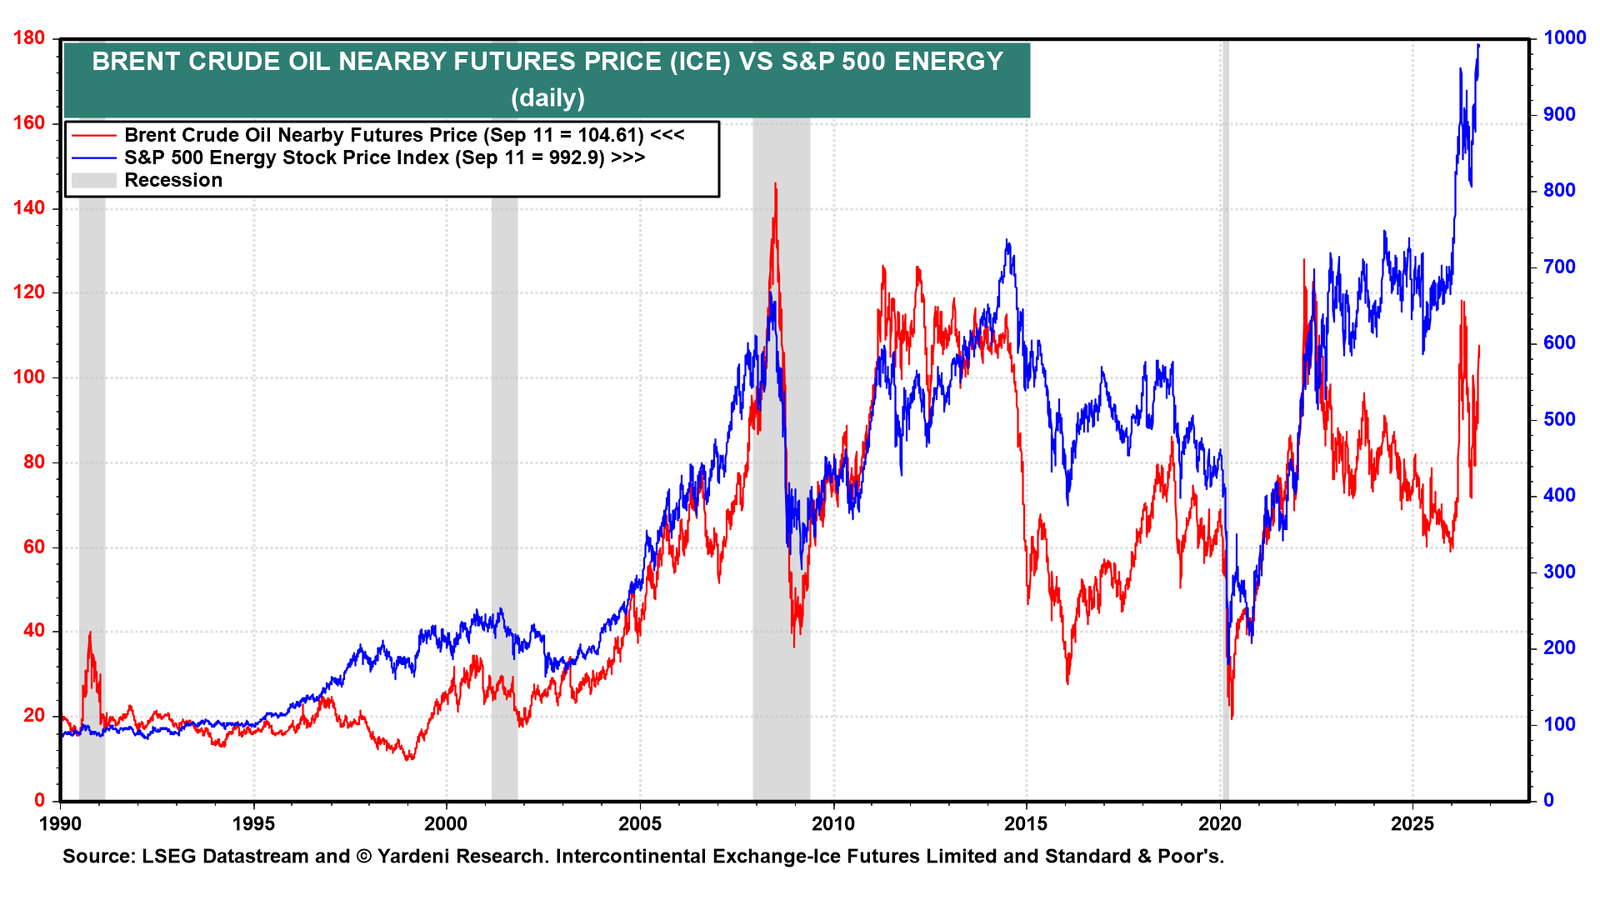
(1) Energy. We have recommended overweighting Energy as a hedge against geopolitical risk. Brent fell below $90 a barrel in late August as diplomacy briefly eased tensions in the Persian Gulf. Last week, the US and Iran exchanged strikes, and Houthi attacks set Saudi oil facilities on fire. Brent futures rose to $104.61 on Friday (chart). The S&P 500 Energy index is at a record high.
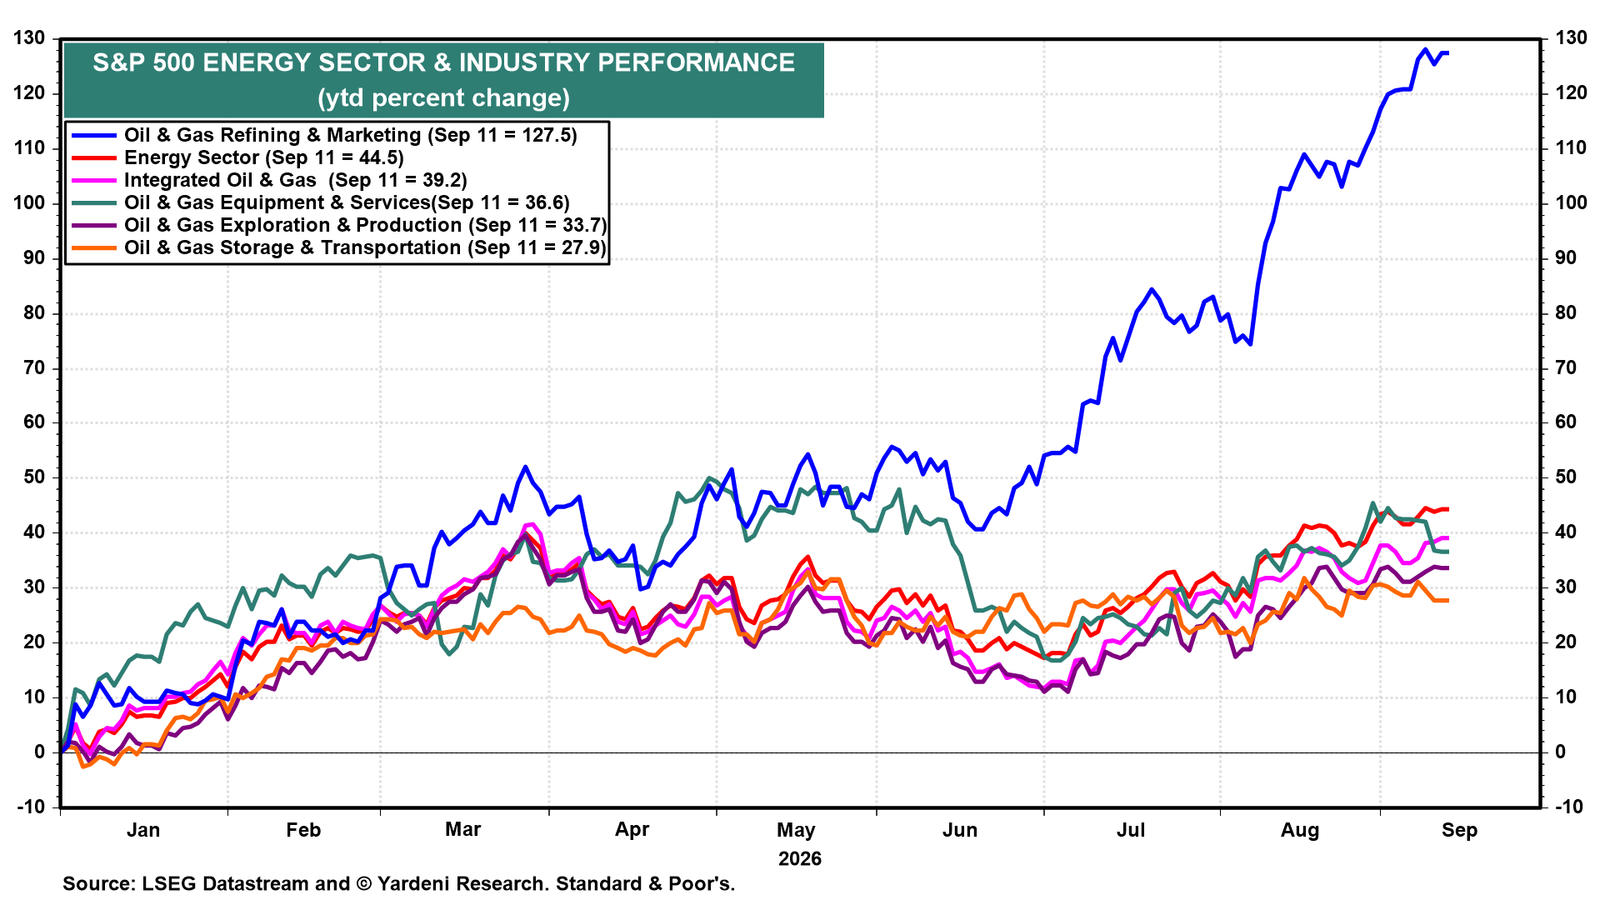
Leading the S&P 500 Energy sector's 44.5% gain so far this year is the Oil & Gas Refining & Marketing industry, up 127.5% (chart).
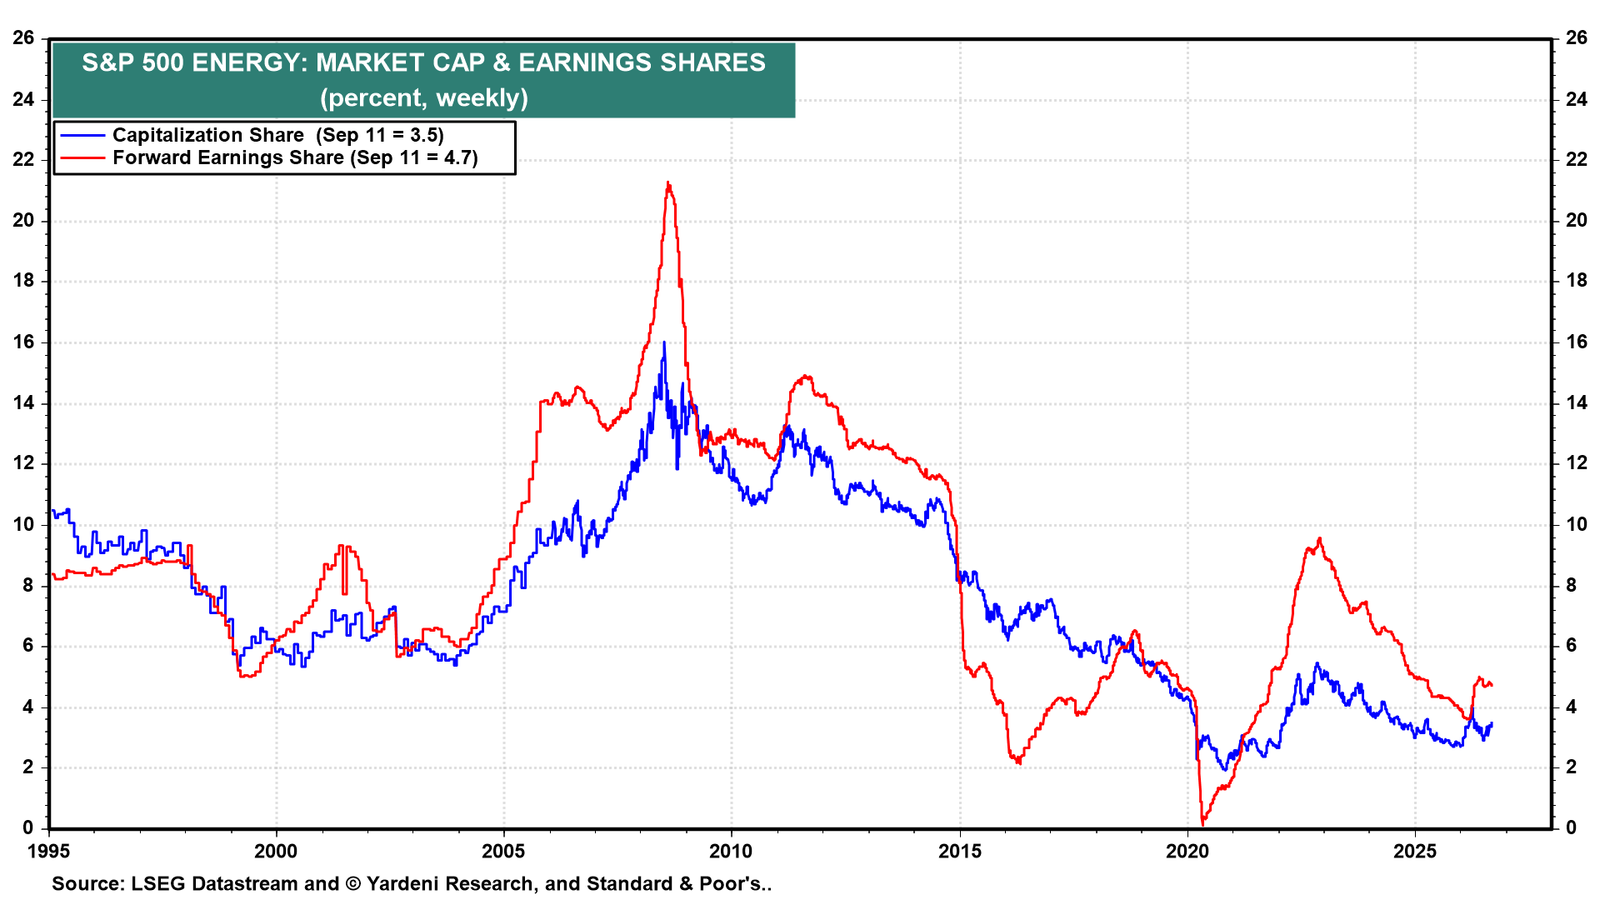
The S&P 500 Energy sector remains cheap and under-owned. It currently accounts for just 3.5% of the S&P 500 market capitalization and 4.7% of the index's forward earnings share (chart). It's easy to overweight it.
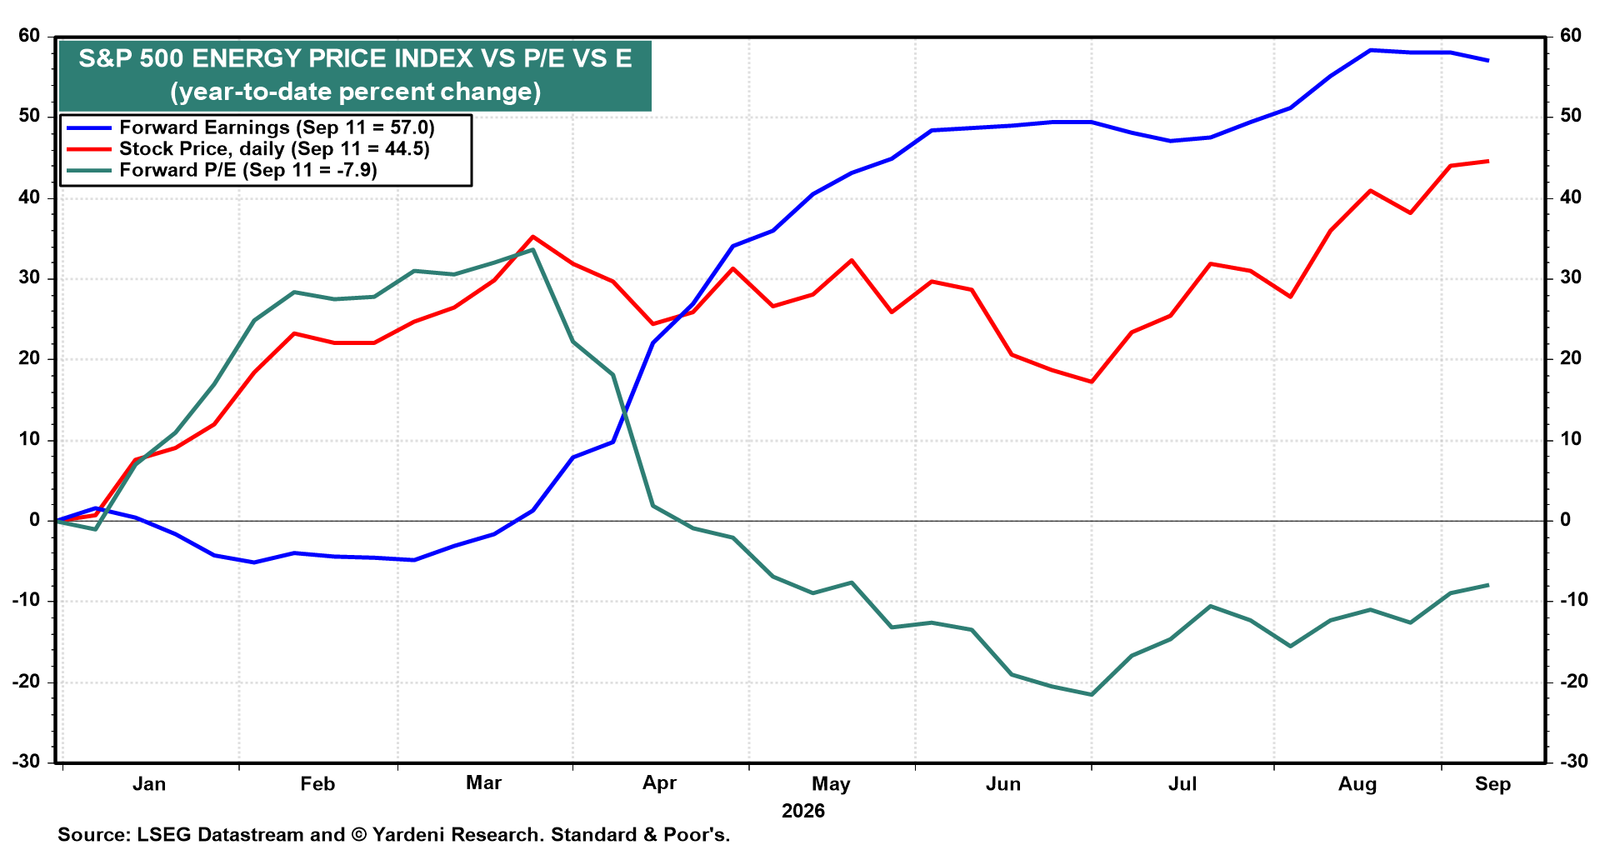
Earnings have driven the Energy sector's rally. Forward earnings is up 57.0% ytd, while the forward P/E is down 7.9%.
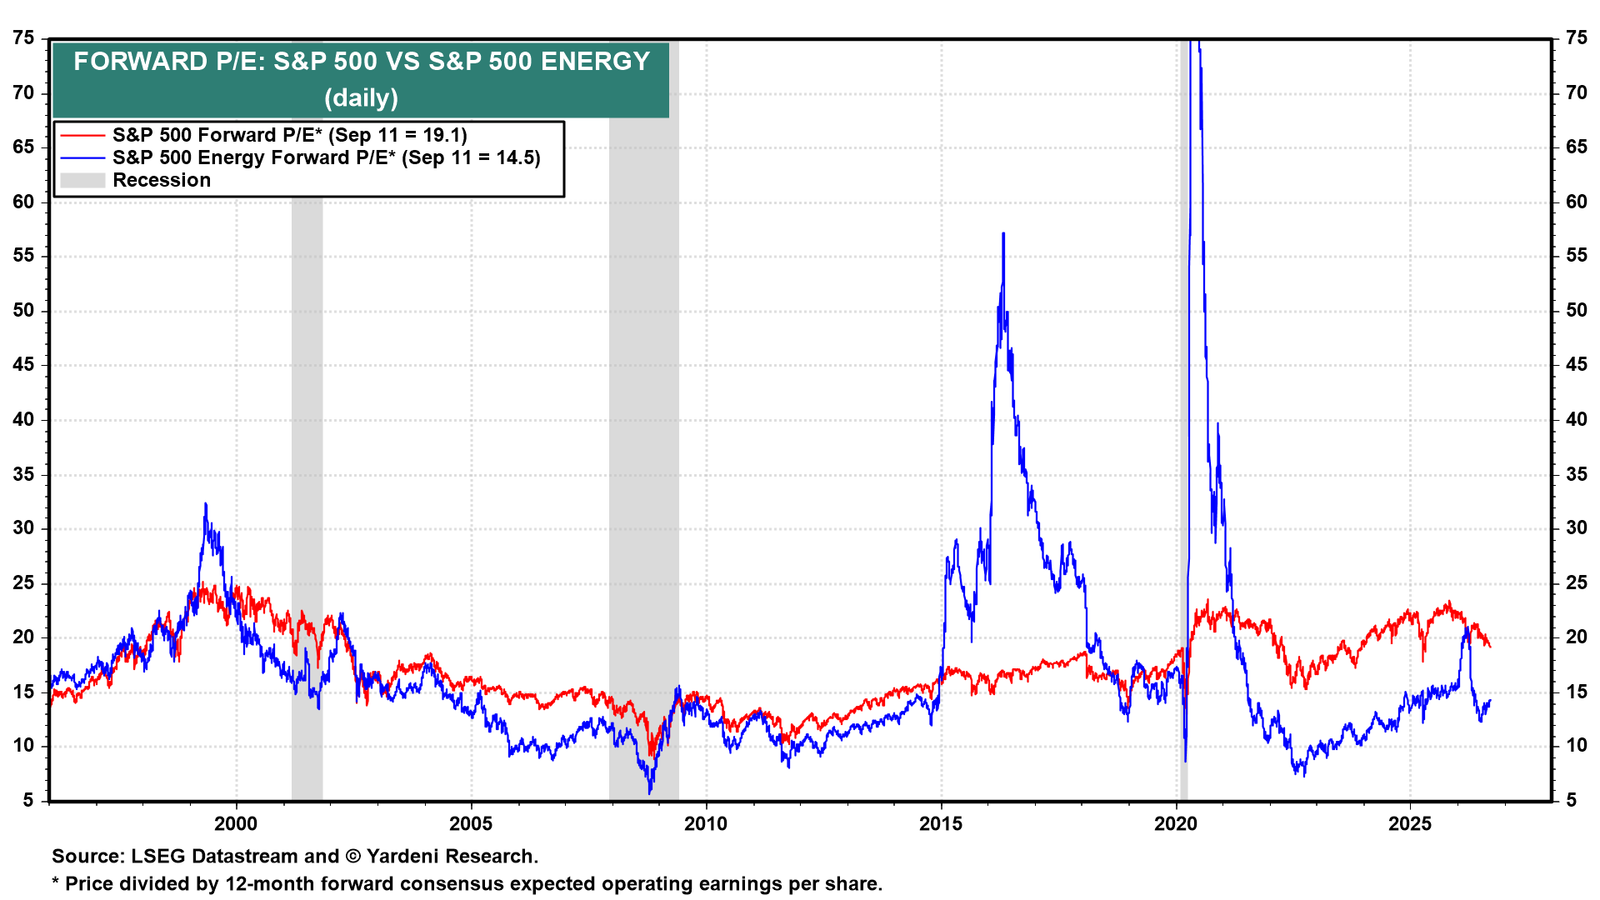
The sector trades at 14.5 times forward earnings against 19.1 for the S&P 500 (chart). If the war continues into the November midterm elections, as President Trump said on Wednesday, Energy should continue to outperform. We are retaining our overweight rating on Energy.
(2) Information Technology. The AI spending boom is showing up in revenues, not just backlogs. Oracle beat estimates on Thursday. Total revenues rose 30% y/y, up from 21% last quarter, as the company's backlog boosts revenue. Cloud infrastructure revenue rose 121% to $7.4 billion. The stock opened 7.3% higher on Friday, then gave it all back to close down 1.7%. Investors initially liked the revenue numbers. They are still deciding what to pay for them.
The Information Technology sector's revenue outlook continues to improve. Estimates call for IT revenues to grow 33.1% this year and 31.1% next year. Yet the sector trades at 20.2 times forward earnings, down from 26.5 at the end of 2025.
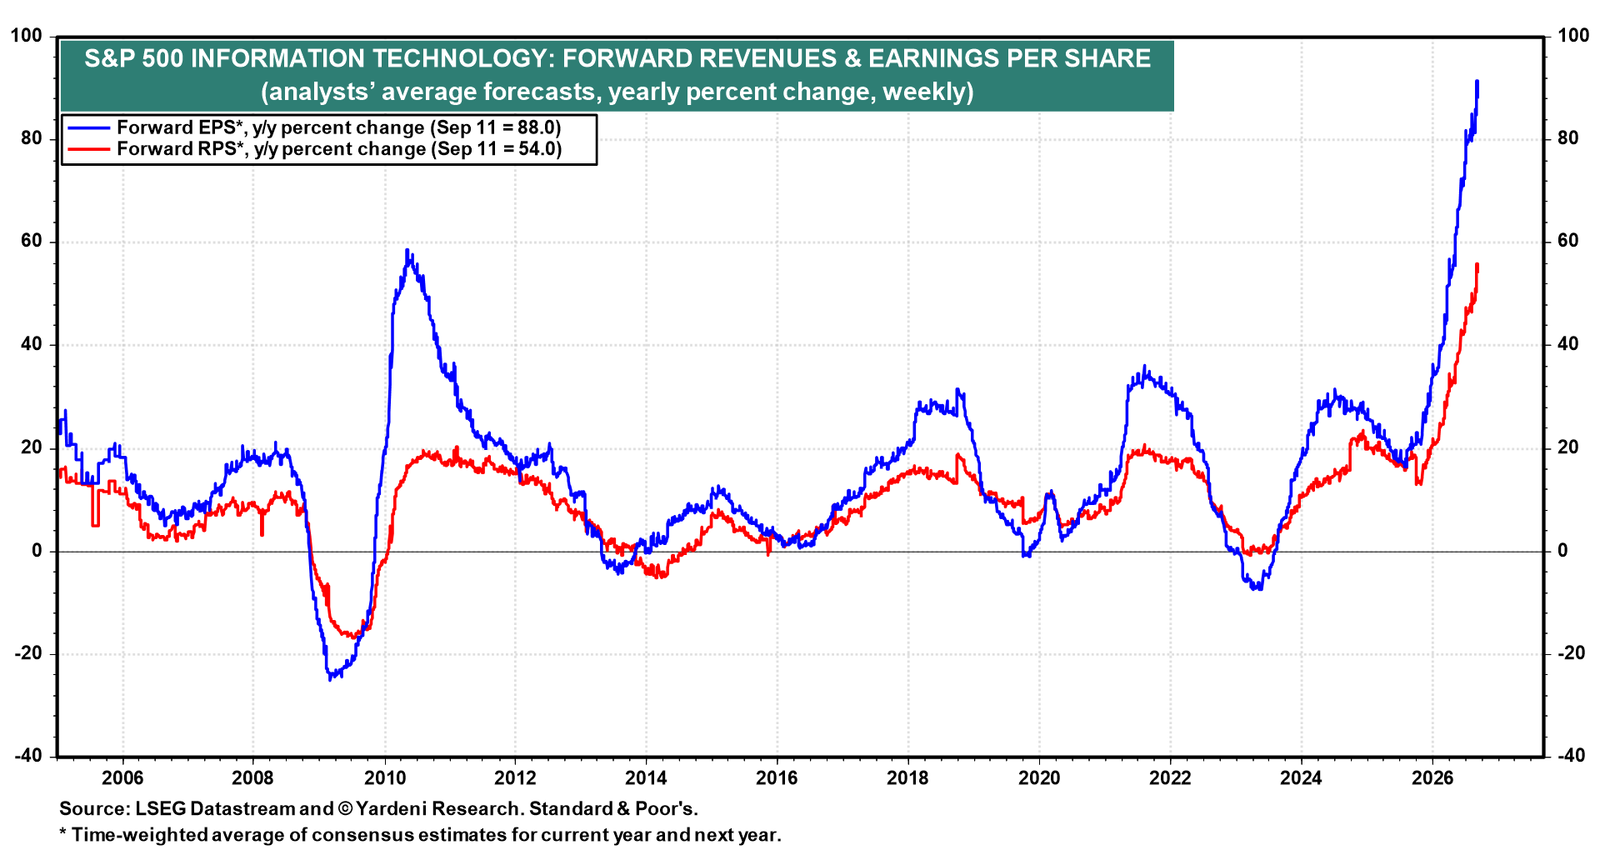
As of last week, the sector's forward revenues and forward earnings were up 88.0% and 54.0% y/y, respectively.
The AI buildout needs more than chips. It needs hardware and equipment to process and store information and also to build more capacity. Technology Hardware, Storage & Peripherals led the IT sector this week, rising 3.3%, and is up 35.5% ytd (chart).
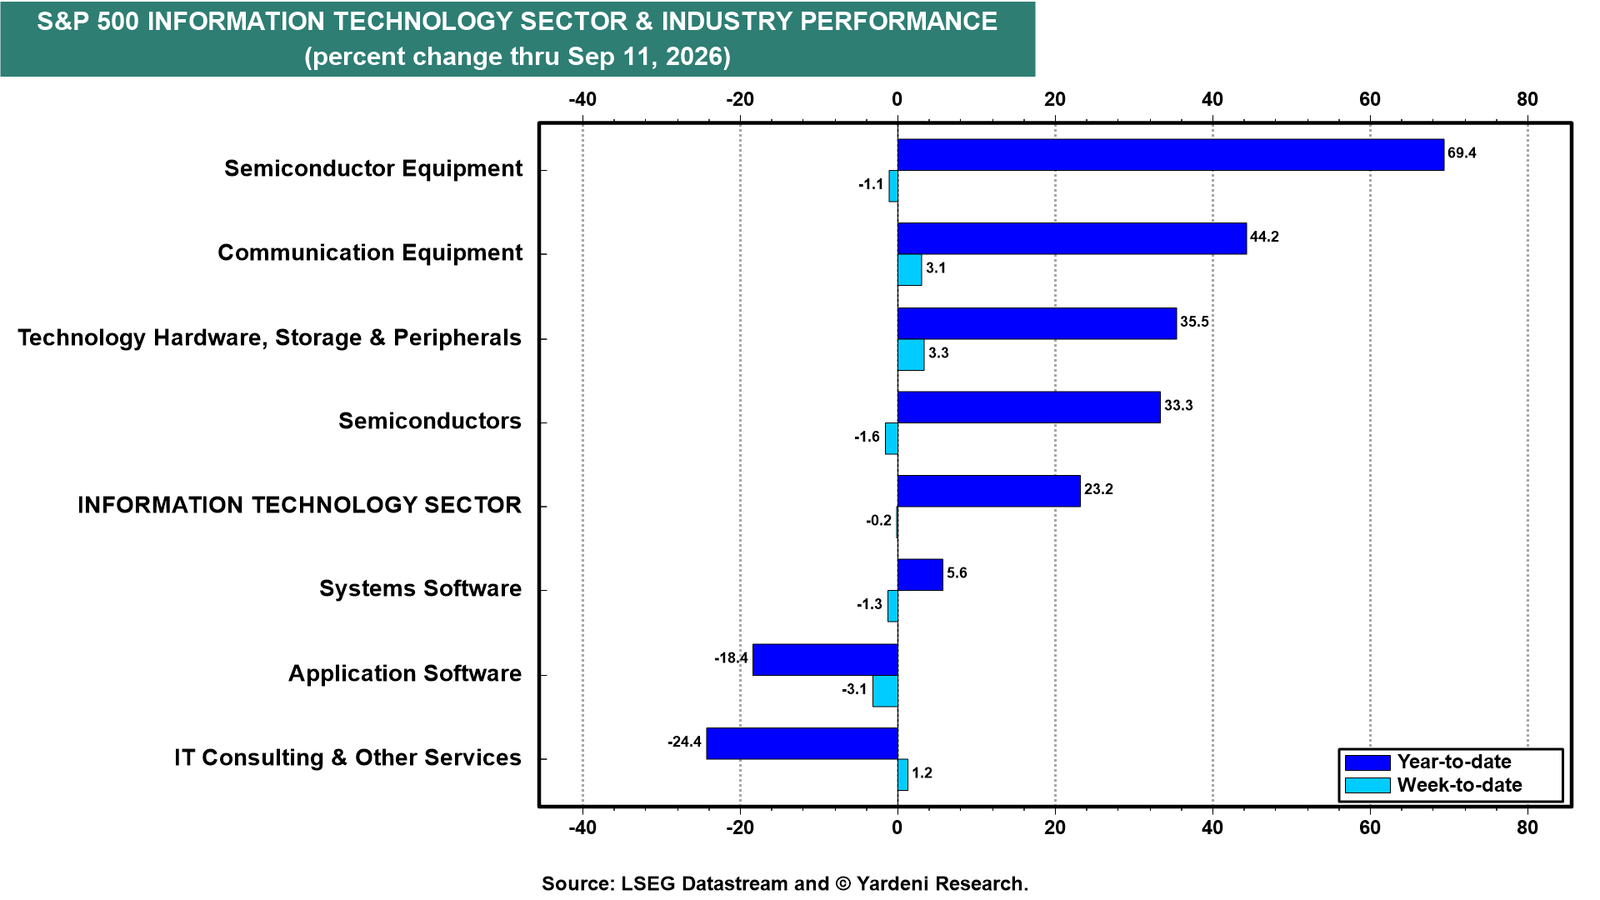
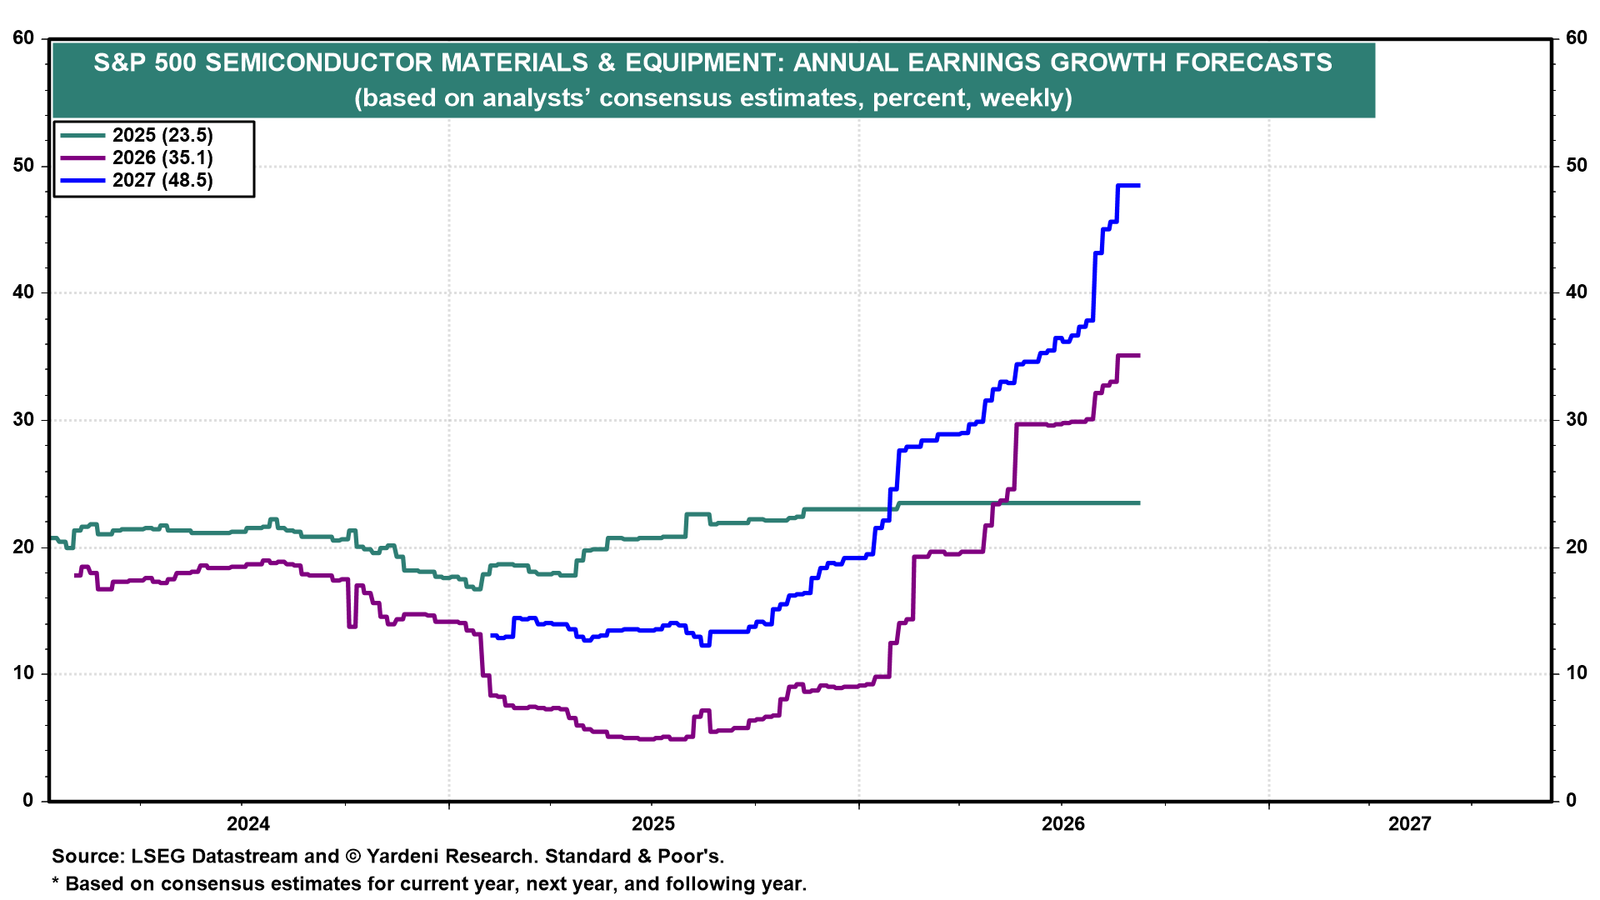
Samsung said in July that the memory shortage should run into 2028. Chipmakers can close that gap only by building capacity, and that means buying equipment. Consensus estimates call for revenue growth of 22.4% this year and 36.6% in 2027. Earnings growth follows, from 35.1% to 48.5% (chart). The industry is the sector's best performer ytd, up 69.4%, yet its forward P/E has fallen to 29.4 from 52.3 on June 30. Earnings are rising faster than stock prices in this industry.
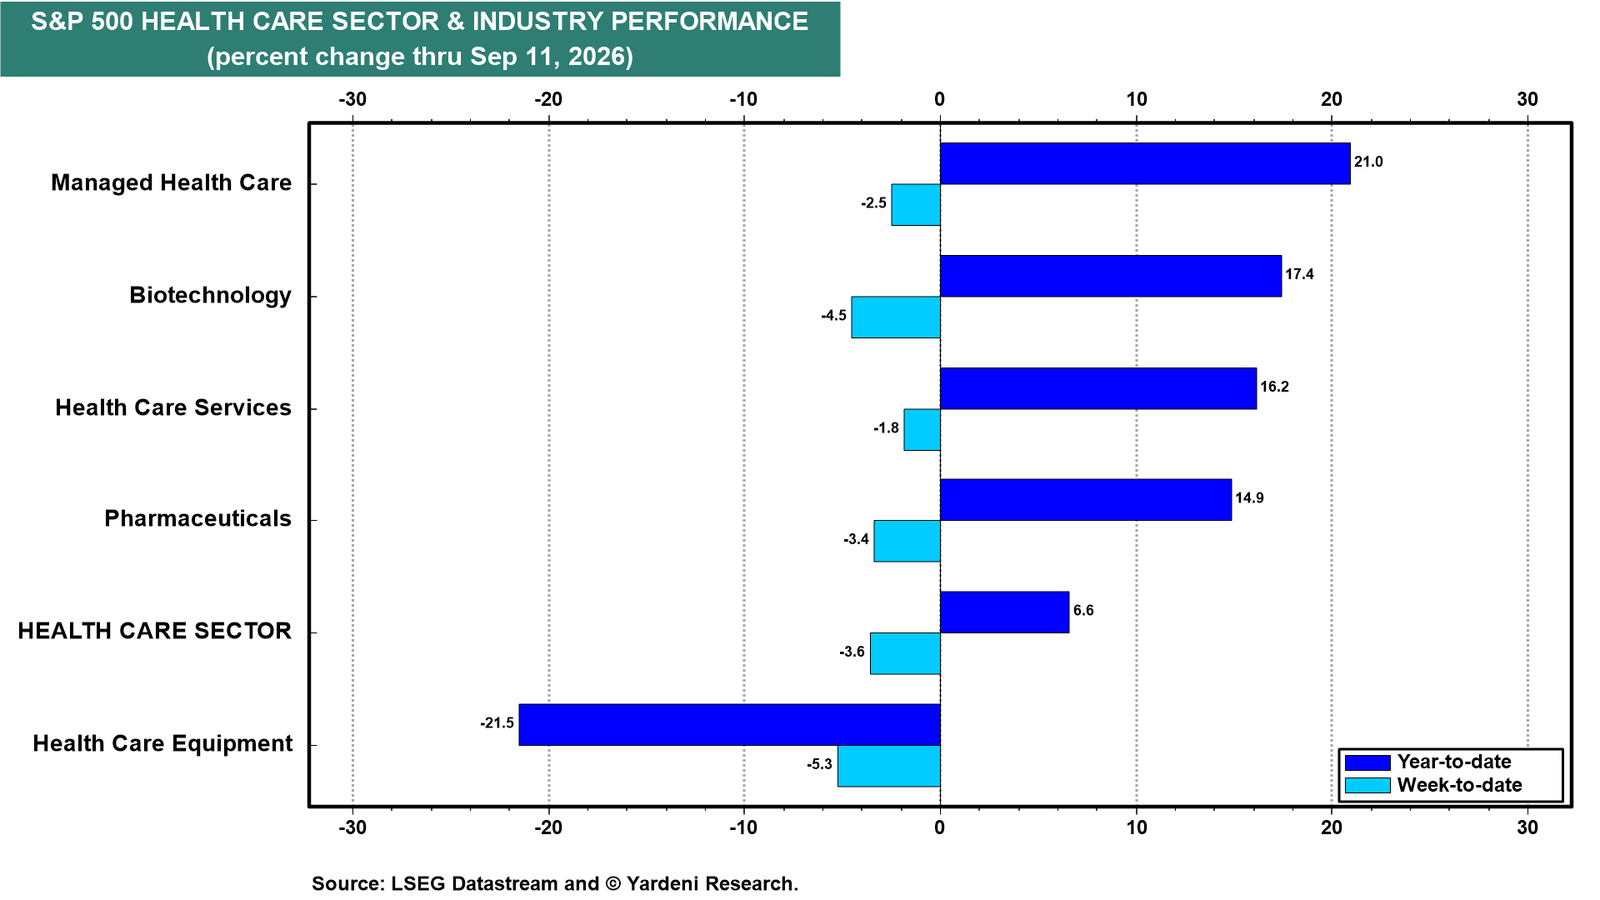
(3) Health Care. Health Care was the worst-performing sector last week, falling 3.6%. Every industry declined. Equipment dropped 5.3%, Biotechnology 4.5%, Pharmaceuticals 3.4%, and Managed Health Care 2.5%. Health Care Services held up best, down 1.8% (chart).
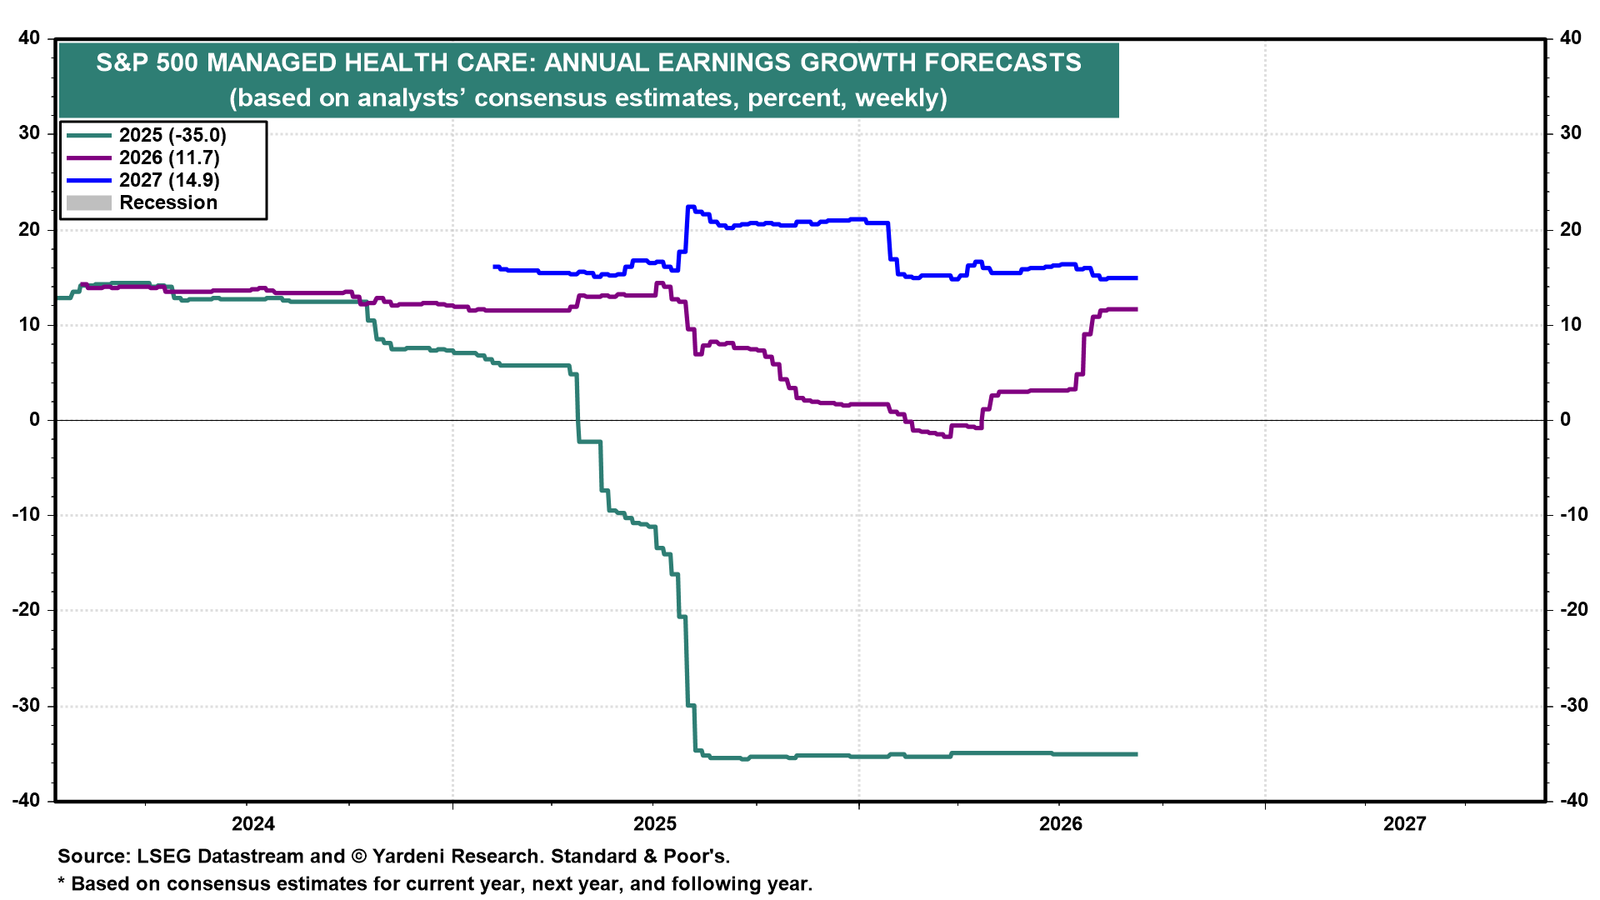
The selloff obscures a sector where earnings are improving. Managed Care is the clearest case. Its earnings fell 35.0% in 2025. Analysts have marked up this year's estimate to 11.7% growth, from -1.6% as recently as March (chart). They see 14.9% next year. Forward earnings has climbed to $186.00 per share from a low of $152.44, and the forward profit margin has risen to 3.0% from 2.5% in March. The industry is up 21.0% ytd, the best in the sector.
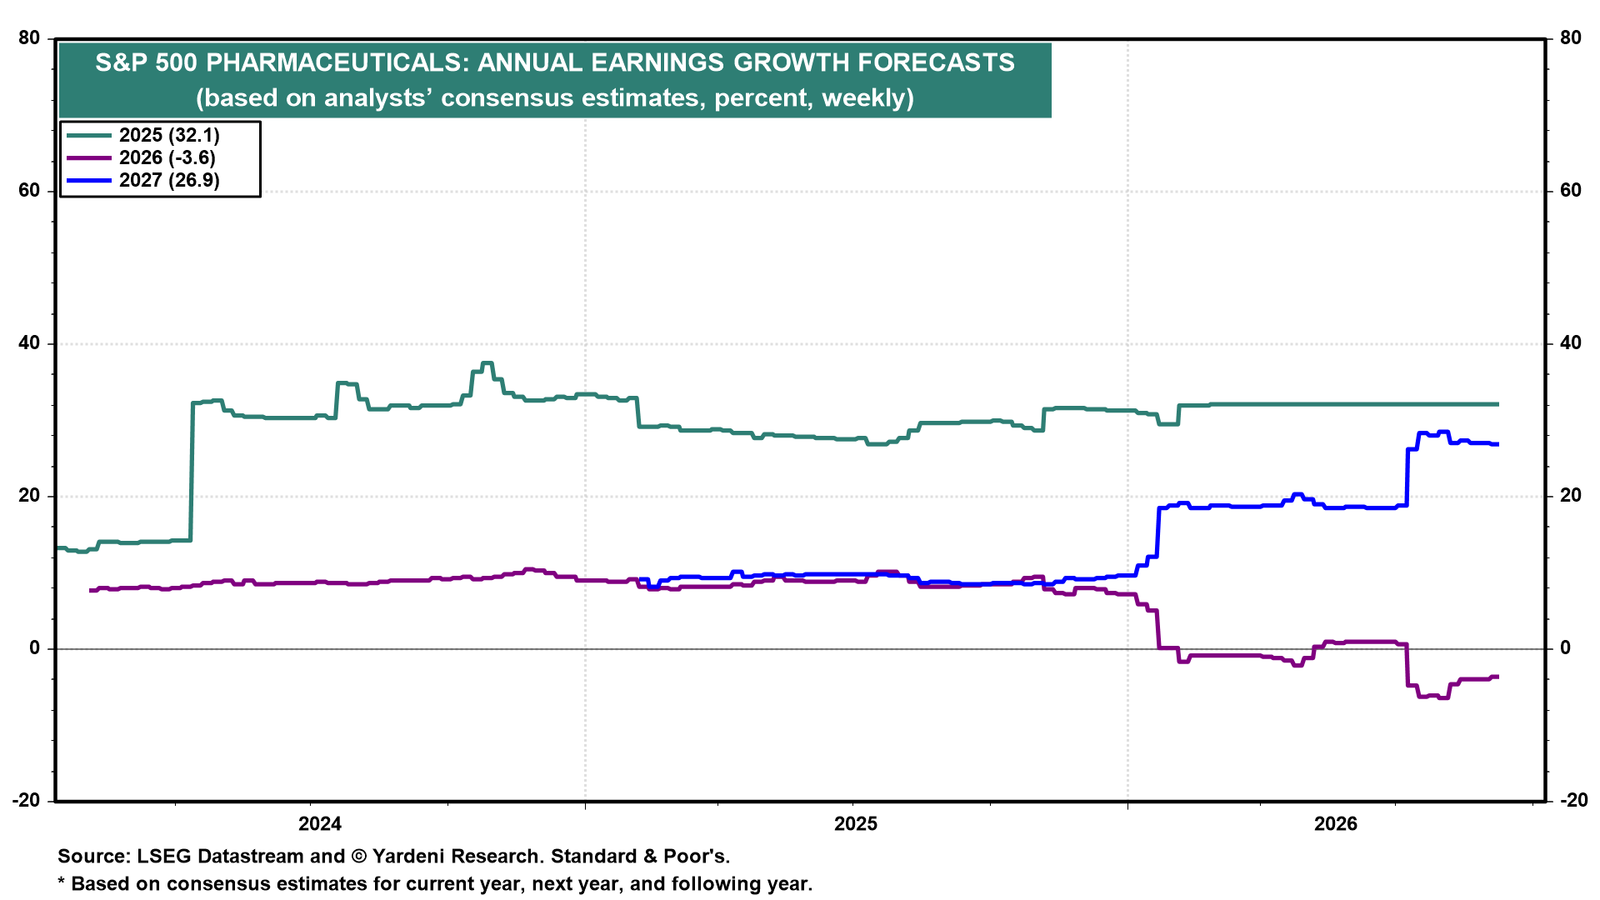
Pharmaceuticals are on the same path, a year behind. Consensus shows earnings falling 3.6% this year, then growing 26.9% in 2027 (chart). The industry's forward earnings is at a record high.
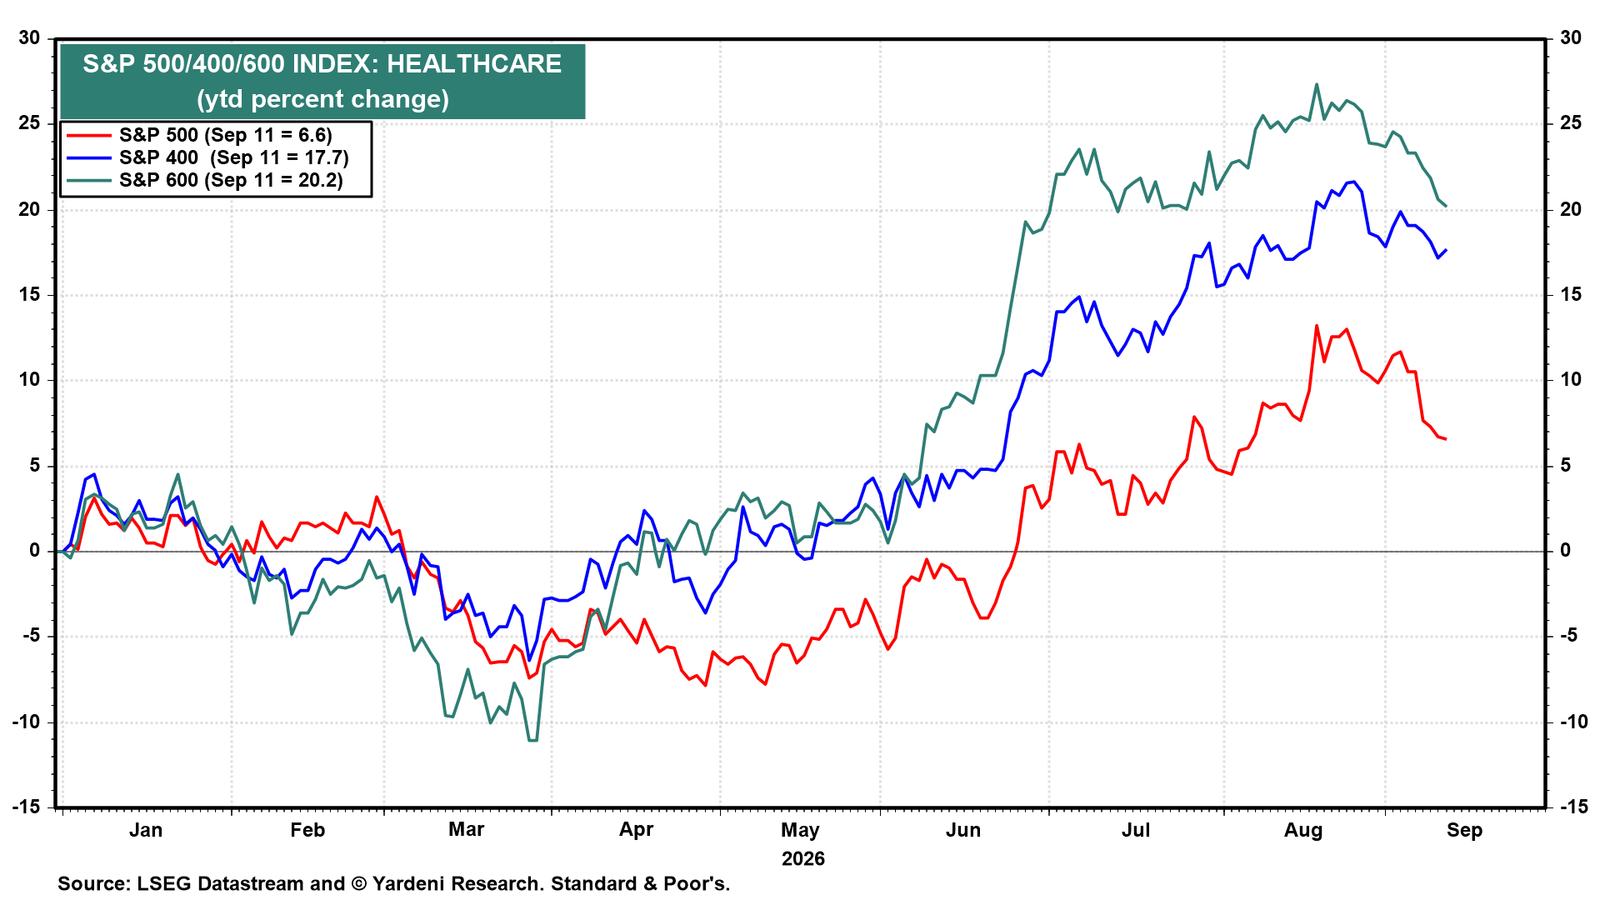
The S&P 600 Health Care index is up 20.2% ytd, and the S&P 400 is up 17.7%, against 6.6% for the S&P 500 sector (chart). We are retaining our overweight rating on Health Care.