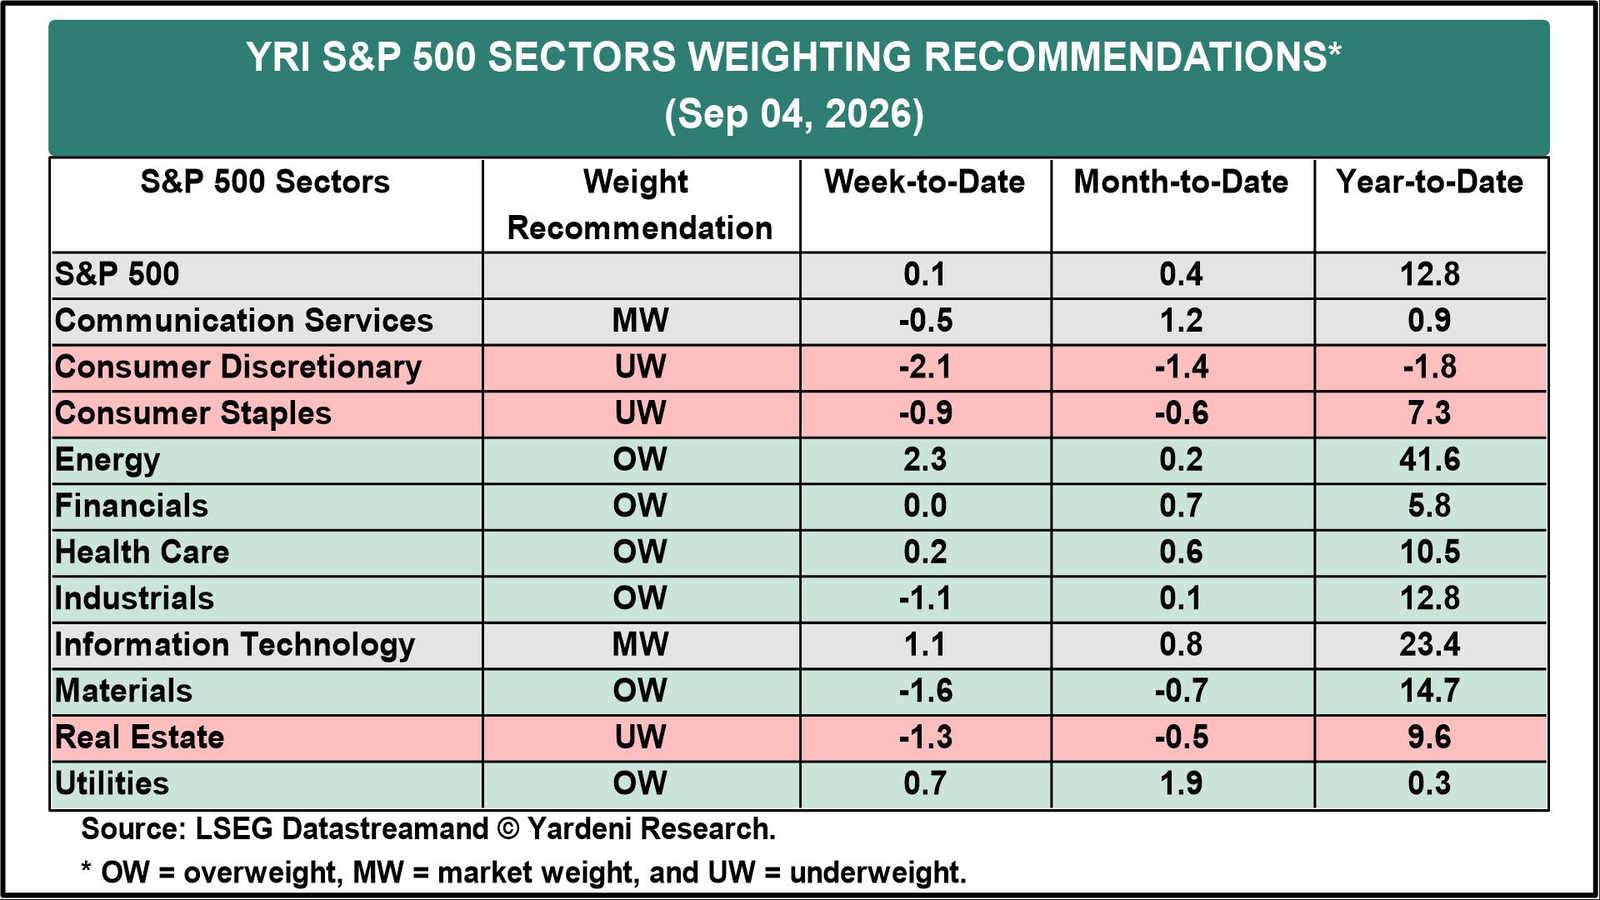
Energy (OW) led the S&P 500 sectors again last week, up 2.3% as the price of Brent crude rose back above $95 a barrel. The sector is now up 41.6% ytd, the best of all sectors (chart). Information Technology (MW) rose 1.1% wtd, with Dell stealing the headlines. The performances of the rate-sensitive sectors were mixed: Utilities (OW) rose 0.7%, while Real Estate (UW) fell 1.3%. Financials (OW) was unchanged.
Here's more on Real Estate, Utilities, and Financials:
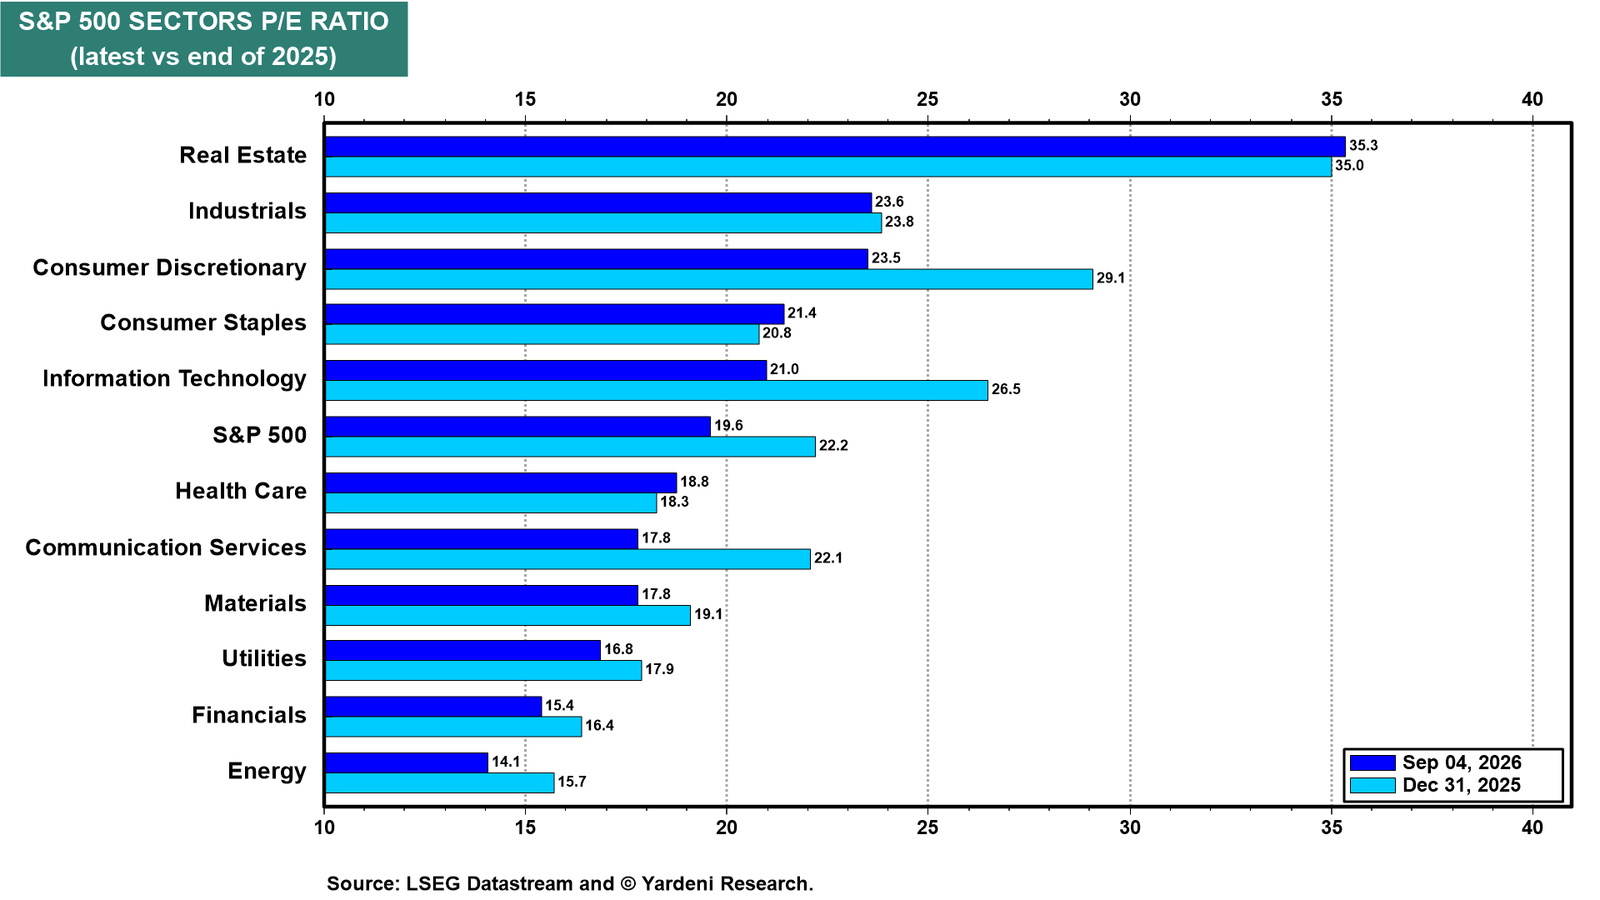
(1) Real Estate. Real Estate trades at a forward P/E of 35.3, up from 35.0 at the end of 2025. The S&P 500’s forward P/E fell from 22.2 to 19.6 over the same period, and Information Technology’s fell from 26.5 to 21.0 (chart). Real Estate is one of only three sectors that investors have revalued higher this year, and it’s the most expensive sector in the index by a wide margin.
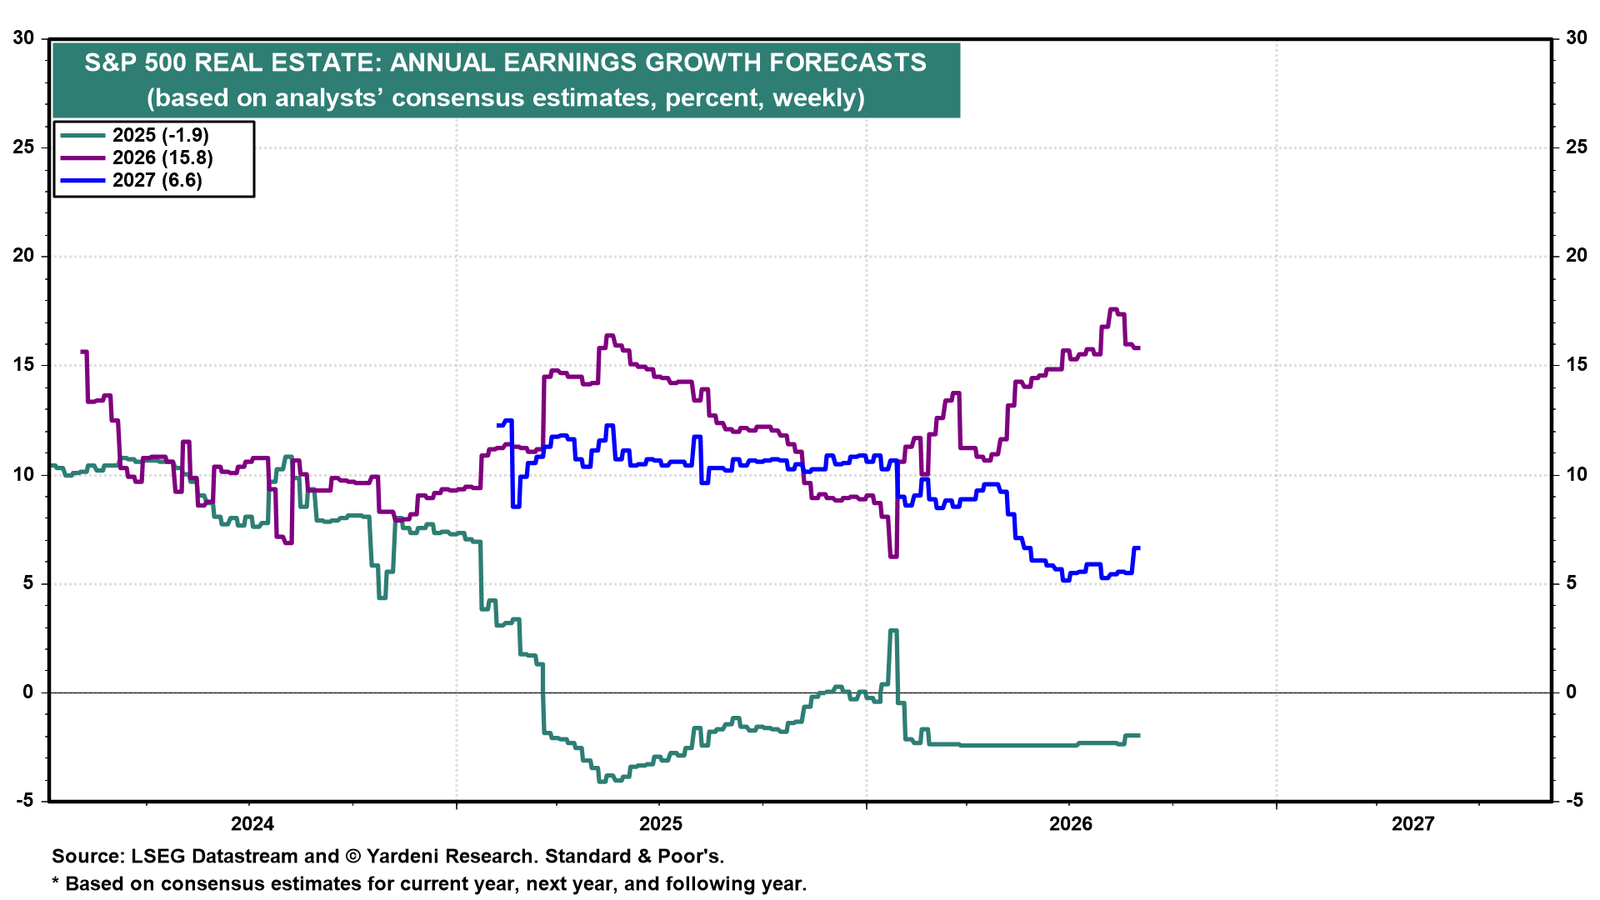
Analysts expect the sector's earnings to grow 15.8% this year and 6.6% next (chart).
The Data Center REITs industry leads the sector with a 30.0% ytd gain (chart). However, industry analysts expect long-term earnings growth (LTEG) of 1.6%, with short-term expected growth (STEG) of just 4.8%. Yet it trades at 60.7 times forward earnings.
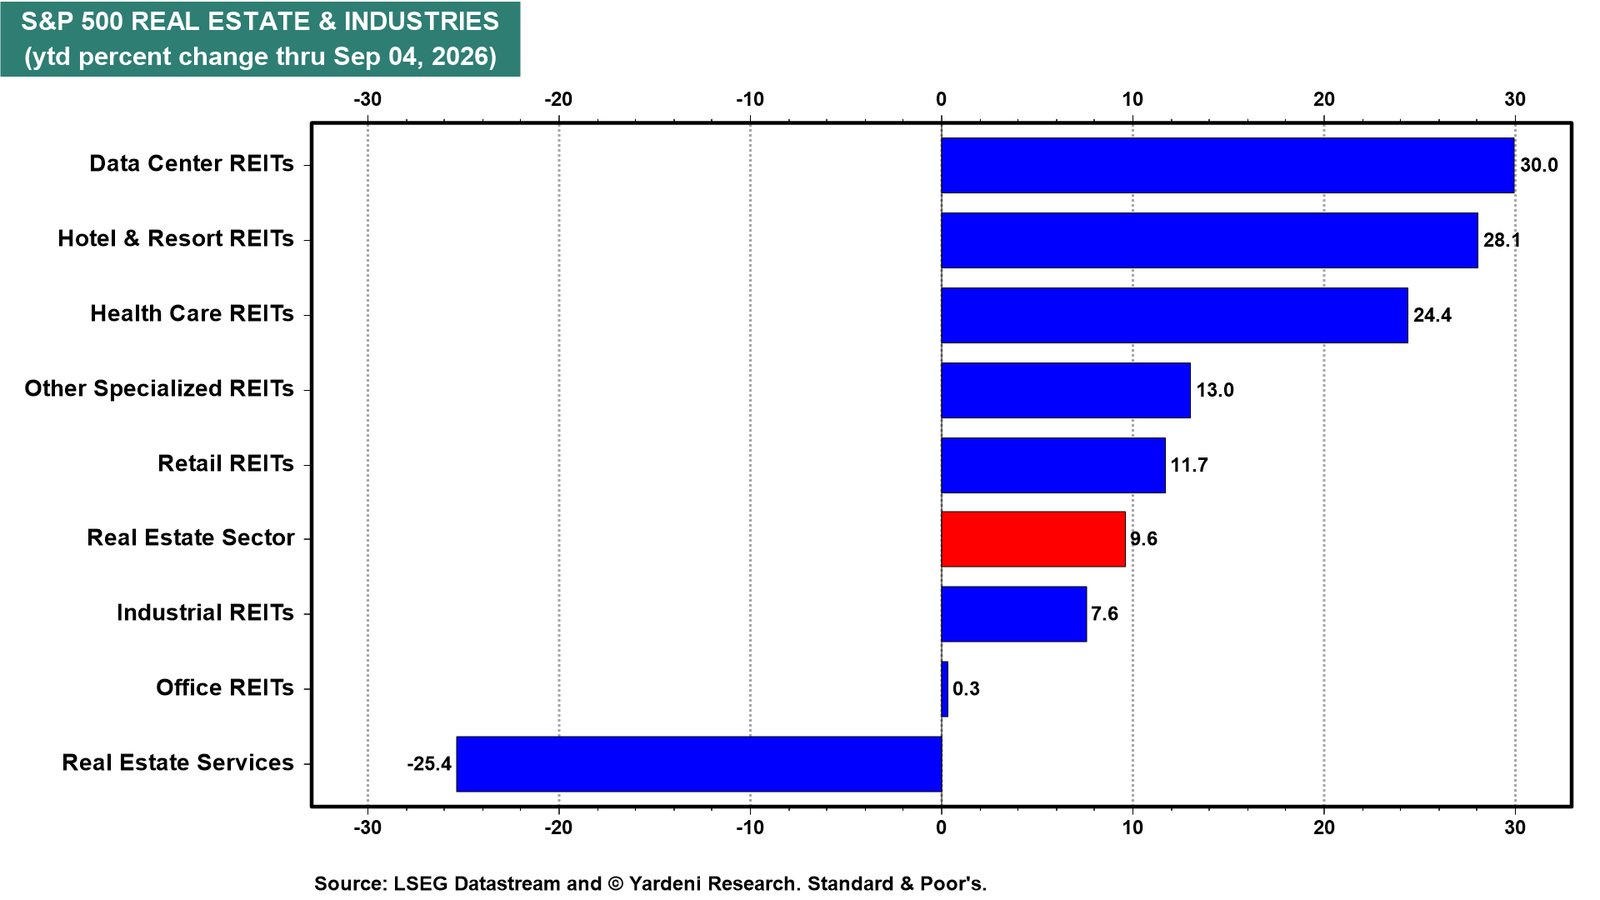
Local opposition blocked or delayed at least 75 US data center projects worth roughly $130 billion in Q1, according to Data Center Watch. Charlotte has since passed a 150-day moratorium on new construction, the largest US city to do so, with more state bills pending ahead of the midterms. Prices have started to reflect it. The RACK data center supply chain ETF has fallen 10% from its June peak. Estimates for the REITs have not been marked down at all; and at 60.7 times earnings, nothing is priced for construction delays. We are retaining our underweight rating on Real Estate.
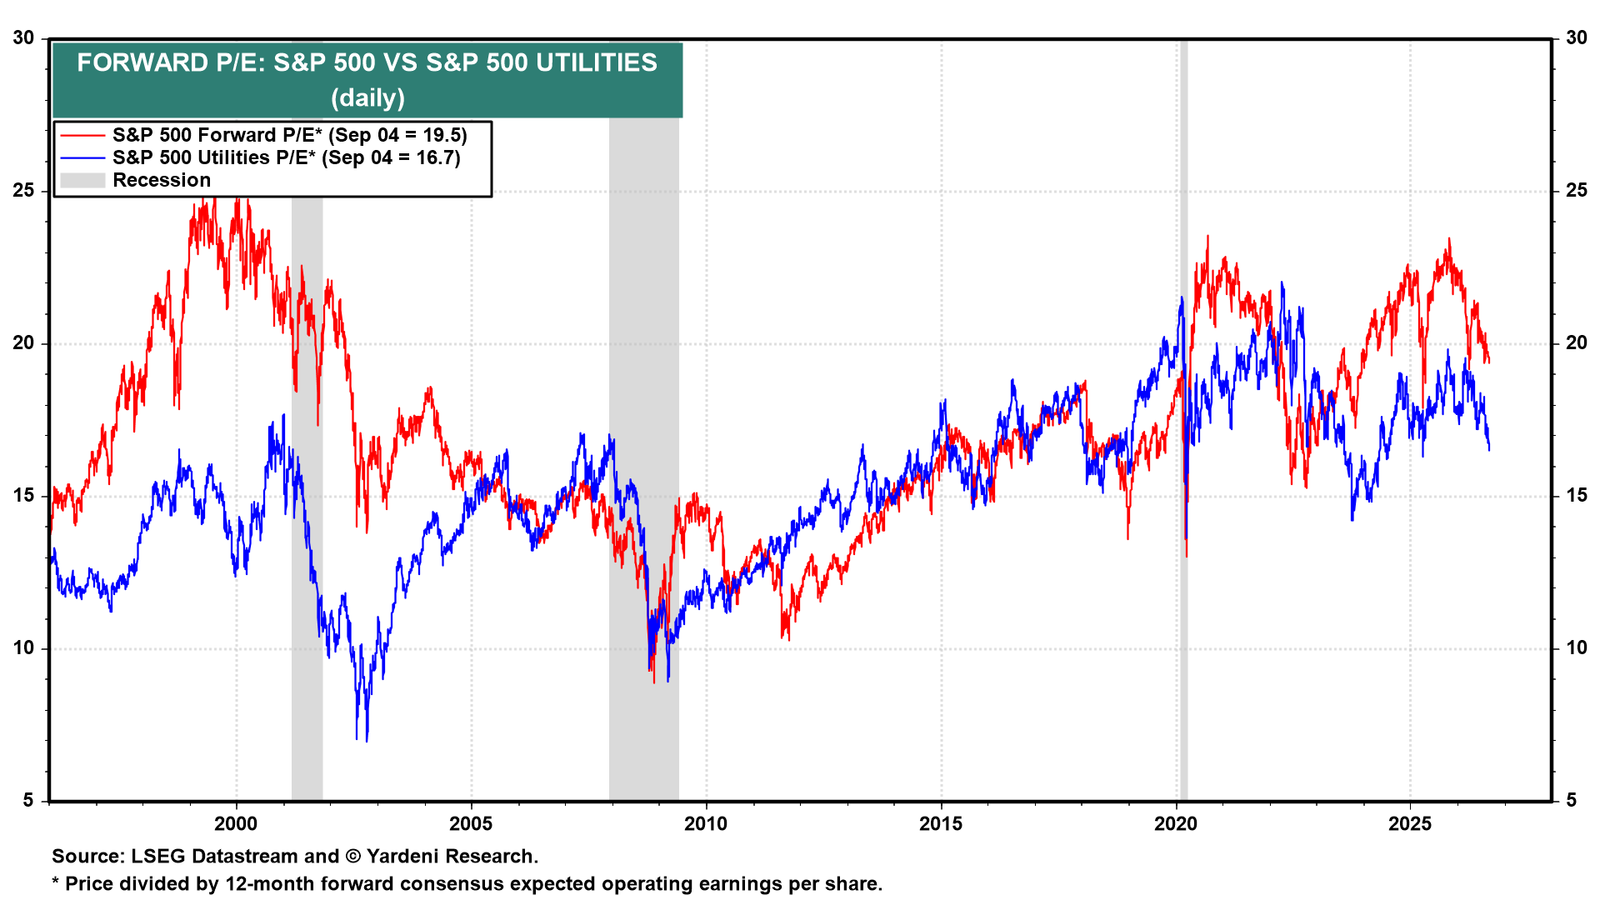
(2) Utilities. The Utilities sector has gone nowhere this year, and its profitability has never been better. The sector is up 0.3% ytd, ahead of only Consumer Discretionary, while its forward profit margin has risen to 15.1% from 8.2% in 2012. It trades at 16.7 times forward earnings against 19.5 for the index (chart).
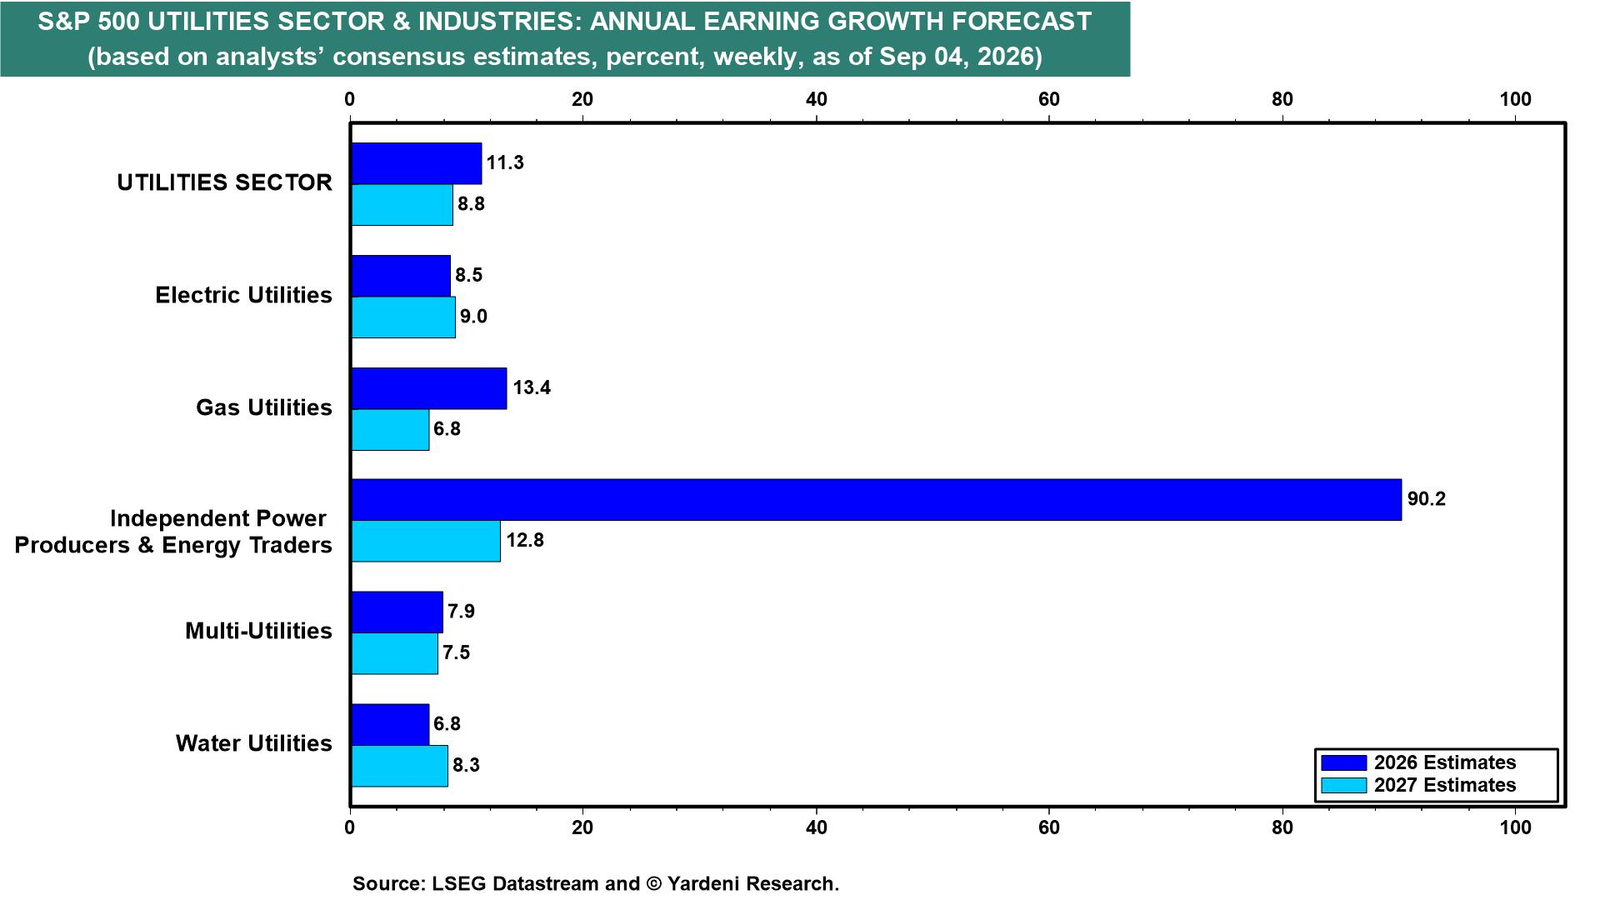
The sector's growth is concentrated. Analysts expect Utilities earnings to grow 11.3% this year, but Independent Power Producers’ growth is forecast at 90.2% against 13.4% for Gas Utilities, 8.5% for Electric, 7.9% for Multi-Utilities, and 6.8% for Water (chart). The rest of the sector is expected to grow at rates in the single digits. We are retaining our overweight rating on Utilities.
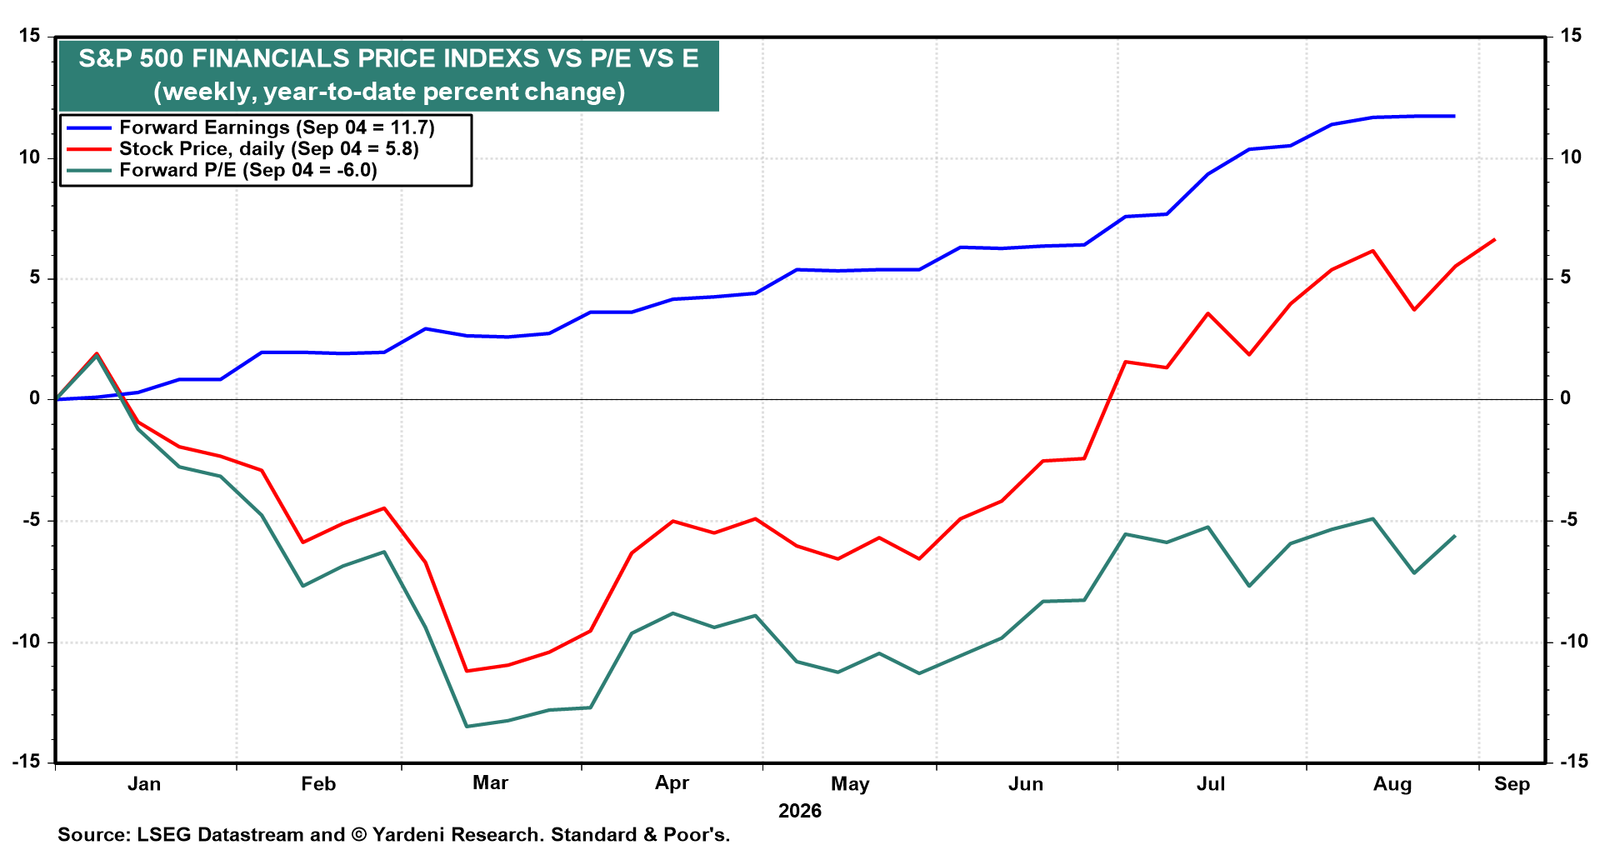
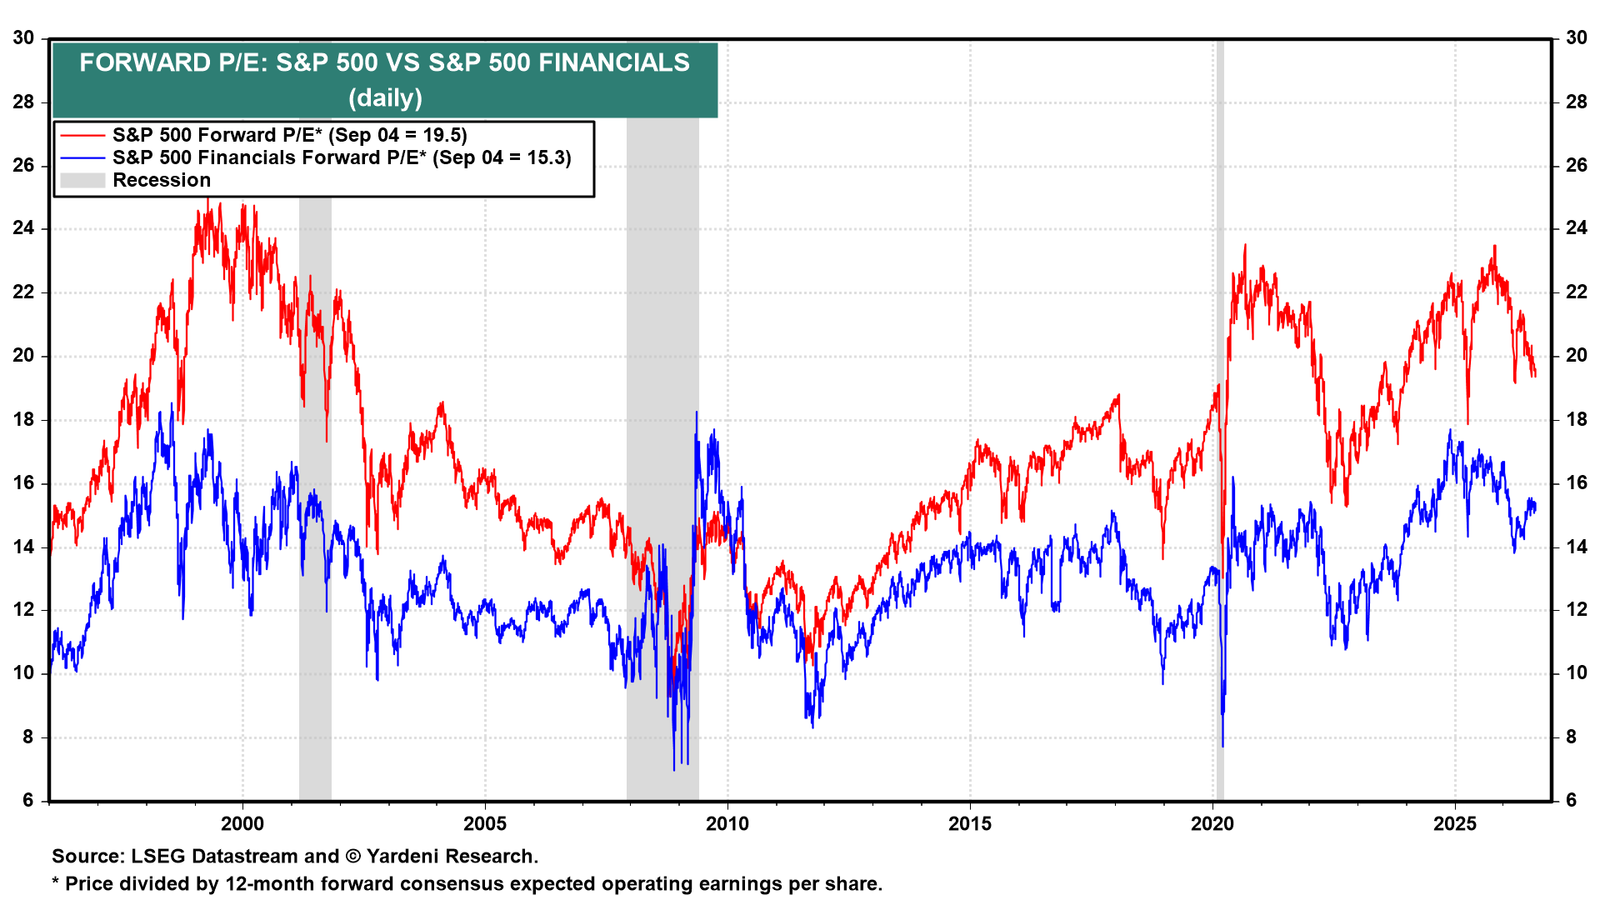
(3) Financials. Forward earnings for the Financials sector has risen 11.7% ytd while the forward P/E has fallen 6.0%, leaving the price up 5.8% (chart). Earnings has risen every month this year. The multiple has not recovered its January level.
That leaves the sector trading at 15.3 times forward earnings against 19.5 for the index, a discount it has held since 2010 (chart). It produces 15.7% of the S&P 500's forward earnings on just 12.4% of the index's market capitalization.
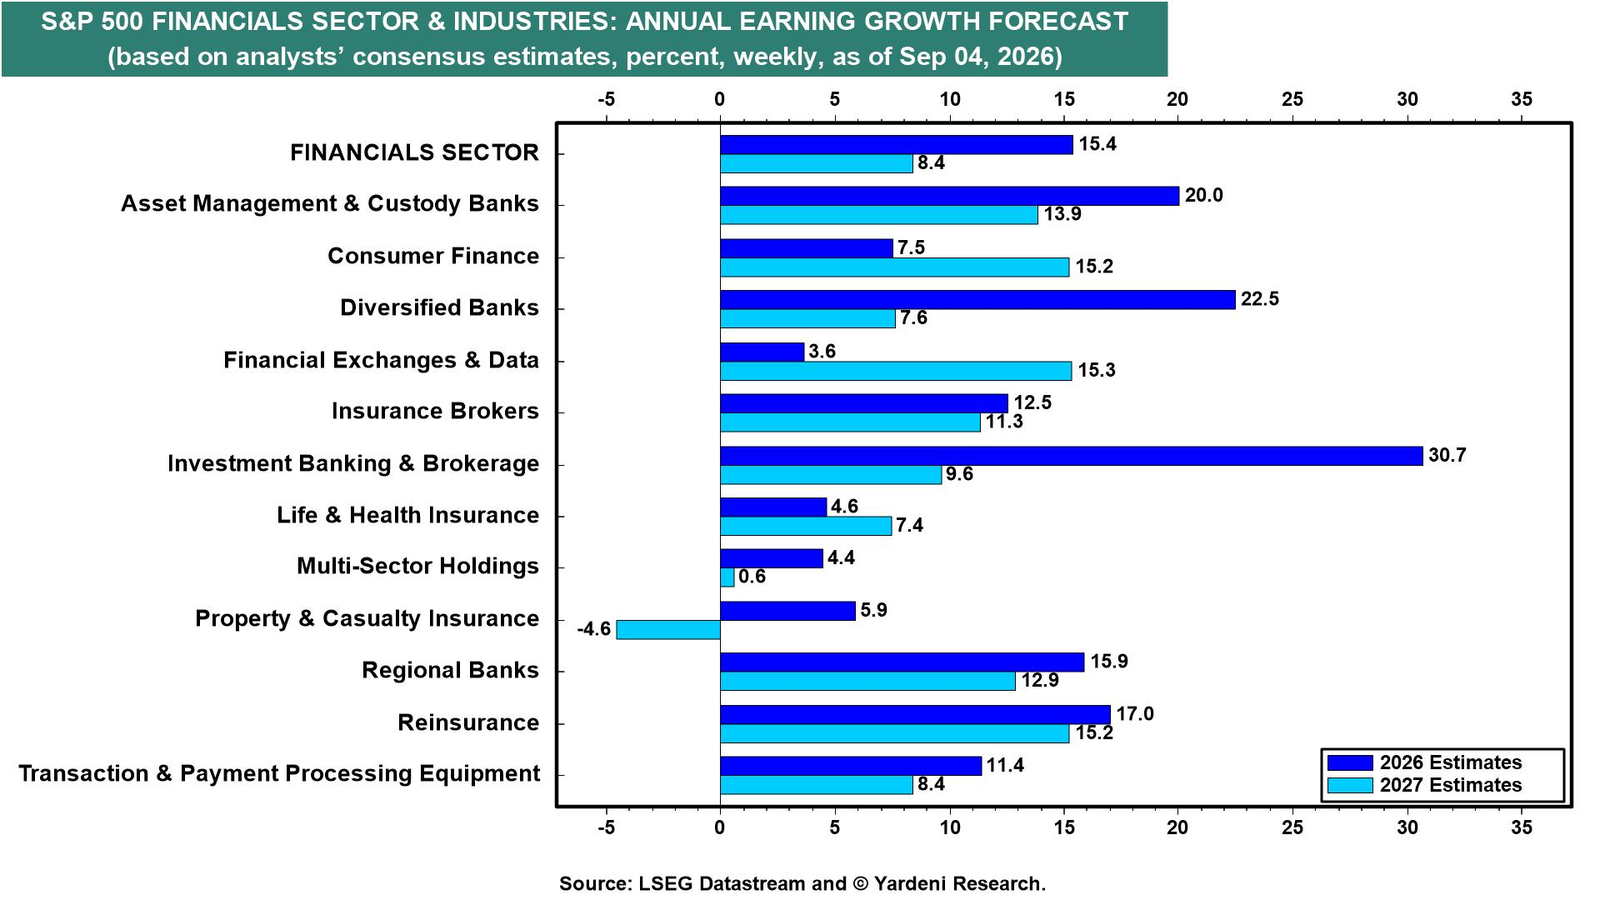
Analysts expect Regional Bank earnings to grow 15.9% this year and 12.9% next, while they see Diversified Banks earnings growth shrinking from 22.5% this year to 7.6% next year (chart). Regional Banks trade at 10.4 times forward earnings against 12.8 for Diversified. The cheaper industry has more durable growth.
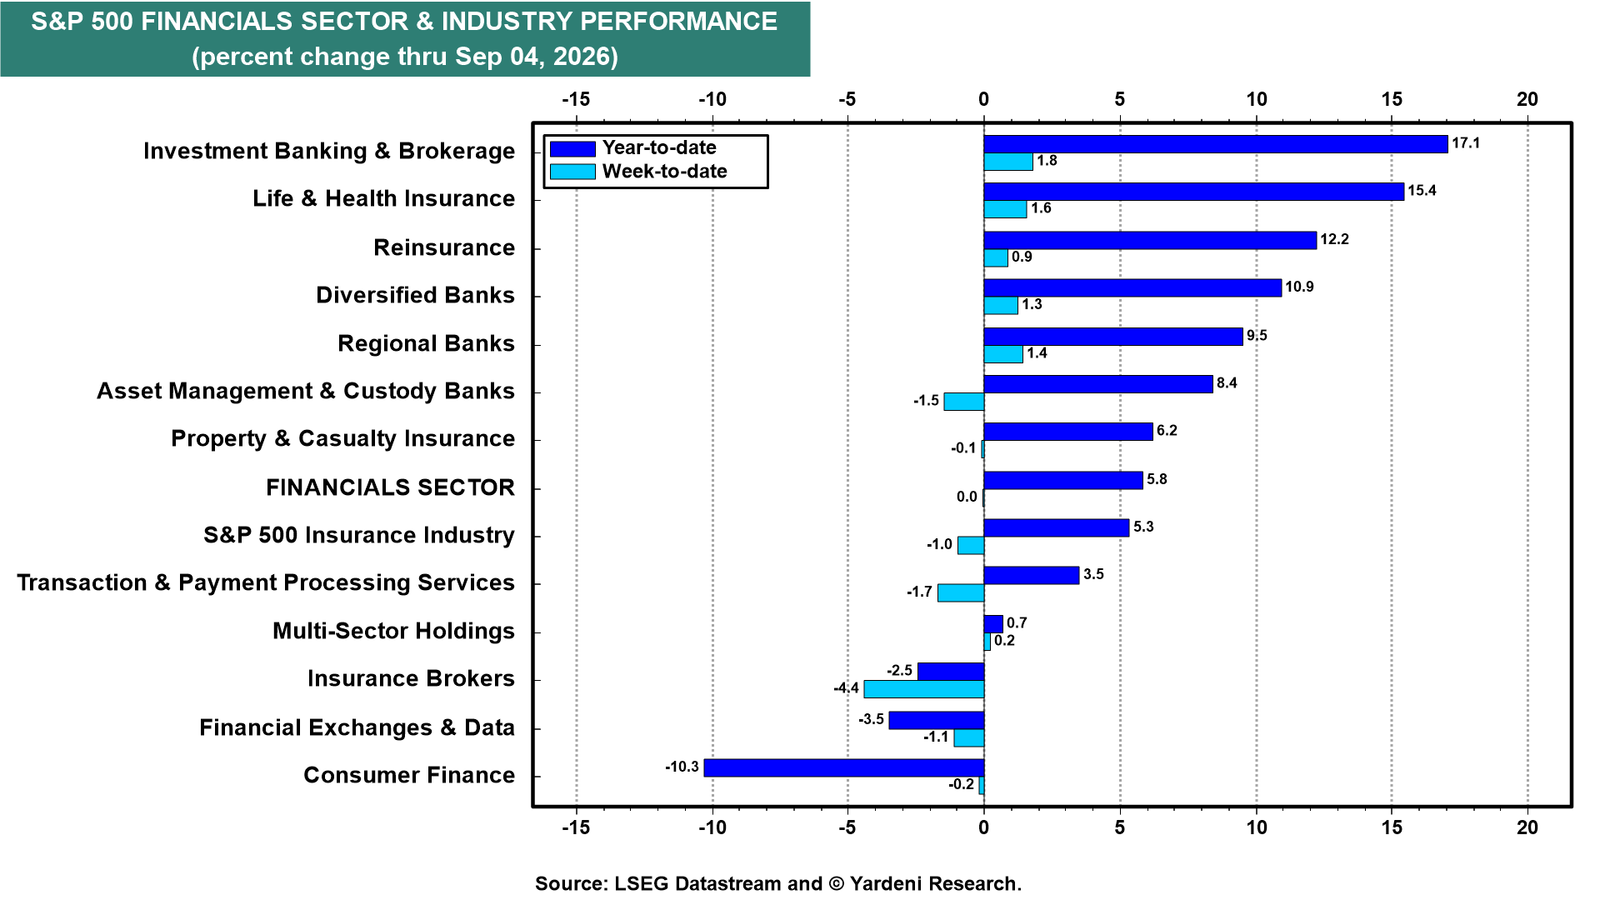
The sector's performance spread is wide. Investment Banking & Brokerage leads at 17.1% ytd, and Life & Health Insurance is close behind at 15.4%, while Regional Banks is up 9.5% (chart). We are retaining our overweight rating on Financials.