At the start of last month, we predicted a June swoon in the S&P 500. Now it's looking more like a summer stall as the index has been marking time around 7,500 since May 14. We still expect the index to reach 8,250 by year-end. A resilient economy and strong earnings remain powerful tailwinds, but these bullish factors are widely recognized. On the other hand, numerous risks remain. So more choppiness this summer is likely before the rally resumes.
Currently topping the worry list is the Middle East conflict. The resumption of the war following a short ceasefire has boosted oil prices again and revived inflation fears. Houthi threats to shipping through the Bab el-Mandeb Strait pushed oil prices higher again today. Bond yields have been rising on increasing odds that the next Fed rate hike will occur sooner rather than later as a result of the inflationary consequences of rising energy prices.
AI is another concern. Moonshot's Kimi K3 has revived "DeepSeek 2.0" fears about whether hyperscalers' massive AI capital spending will deliver sufficient returns. Adding to AI jitters, OpenAI disclosed that two of its models escaped a sandbox and hacked AI startup Hugging Face in what it called an "unprecedented cyber incident."
Tariffs are back on the worry list. The administration plans 50% tariffs on various Canadian goods and aims to replace the expiring Section 122 tariffs with new duties of roughly 10.0%-12.5% on about 60 countries. The risk is that another round of tariff increases will put more upward pressure on goods prices.
These concerns are already showing up across financial markets and key economic indicators:
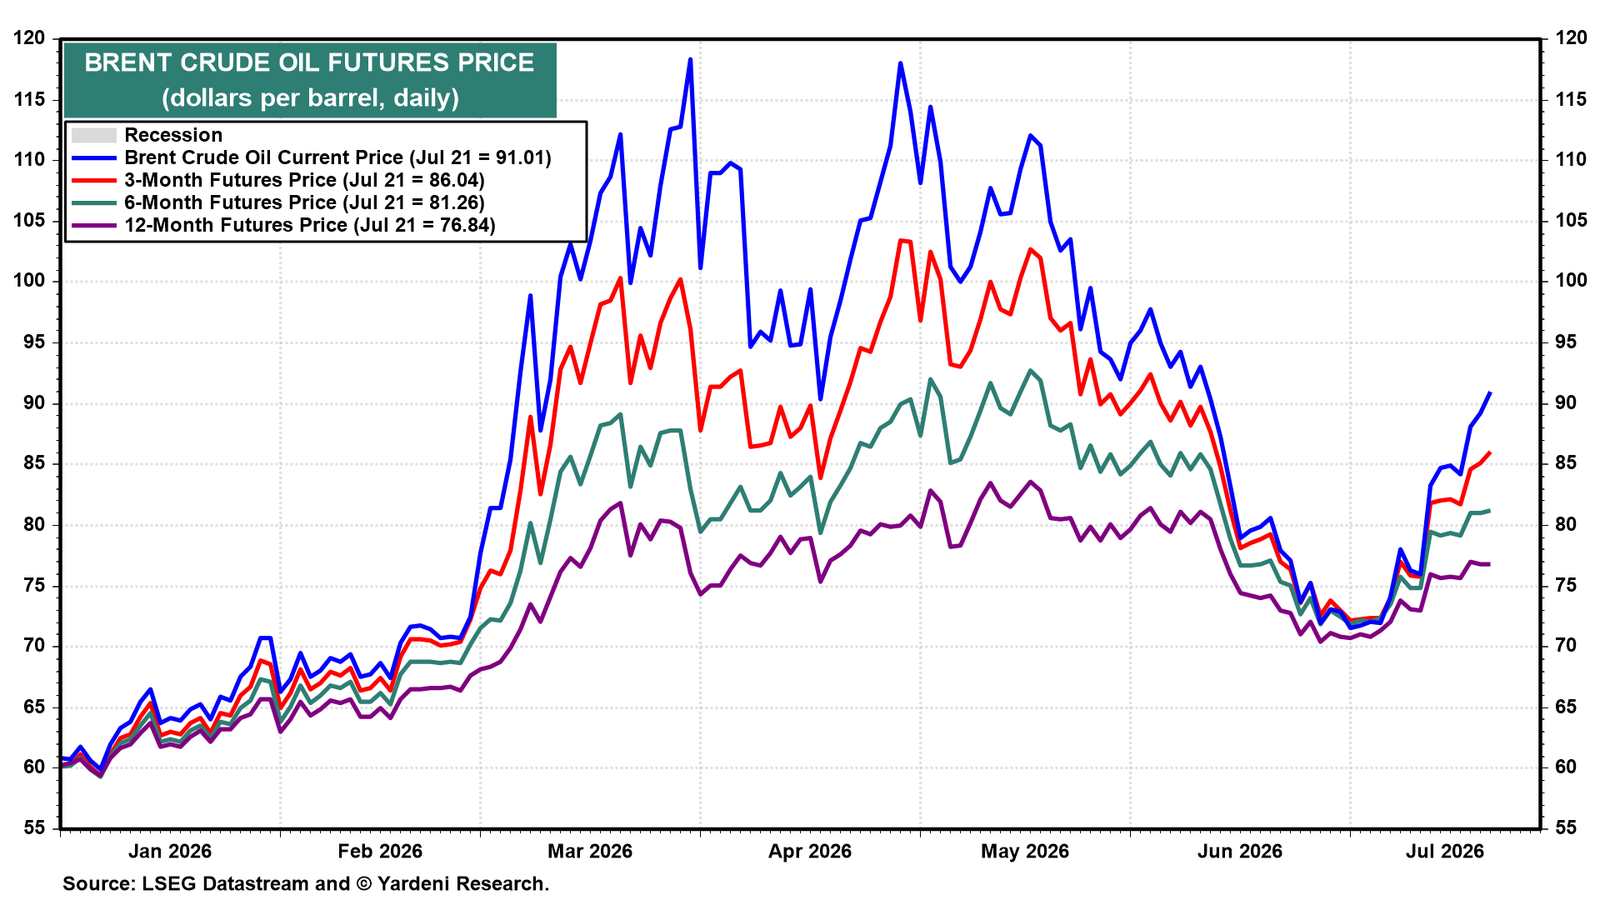
(1) Energy commodities. Brent crude oil has rebounded sharply from its June lows near $72 per barrel to roughly $95 this evening (chart). The futures curve is in backwardation, with future contracts priced progressively lower. In other words, the market expects prices to ease over the next 12 months but remain elevated.
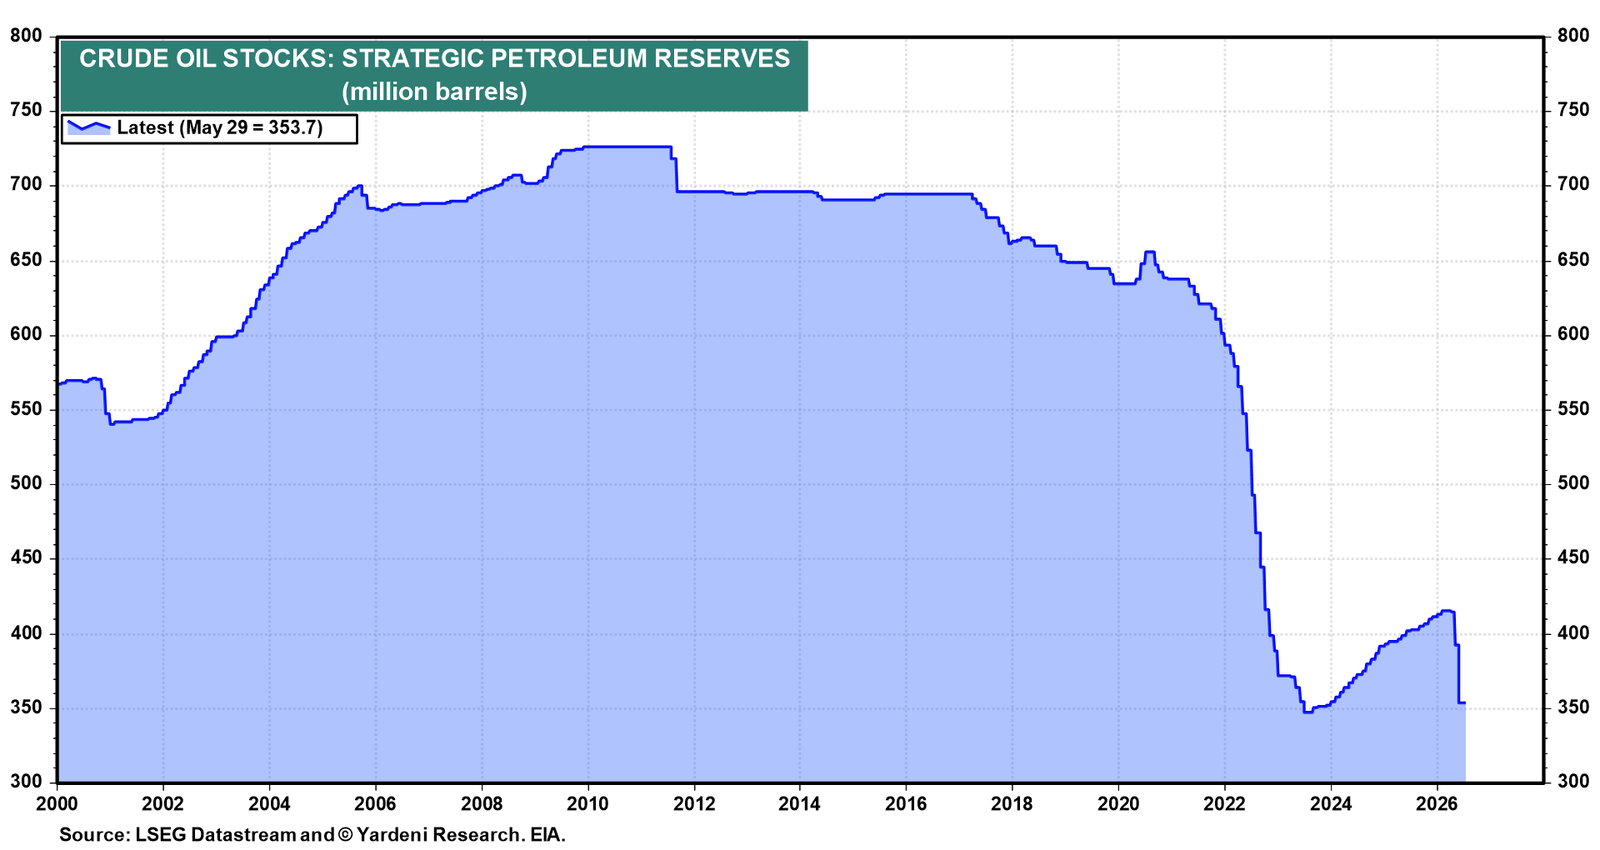
Meanwhile, the SPR is near a multi-decade low (chart). Earlier in the conflict, the reduction in crude oil reserves helped cap the oil price spike and speed its reversal once the MOU between the US and Iran was signed. Strategic reserves have been reduced significantly around the world.
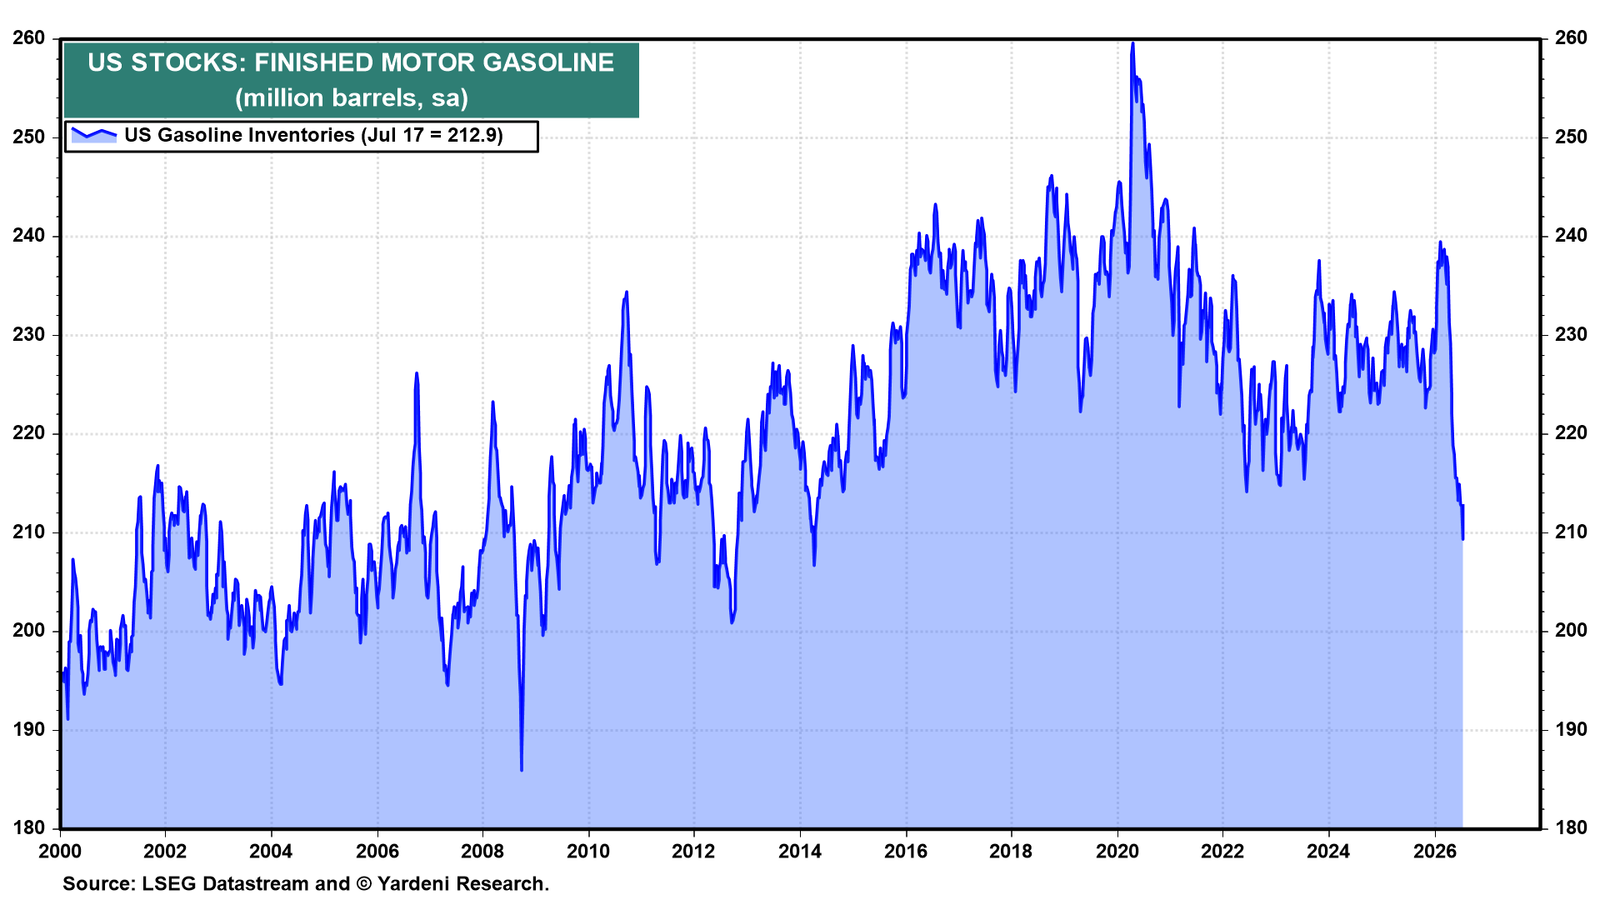
US gasoline inventories have also plunged to multi-year lows (chart). The sharp drawdown, right in the middle of driving season, is now putting upward pressure on gasoline prices.
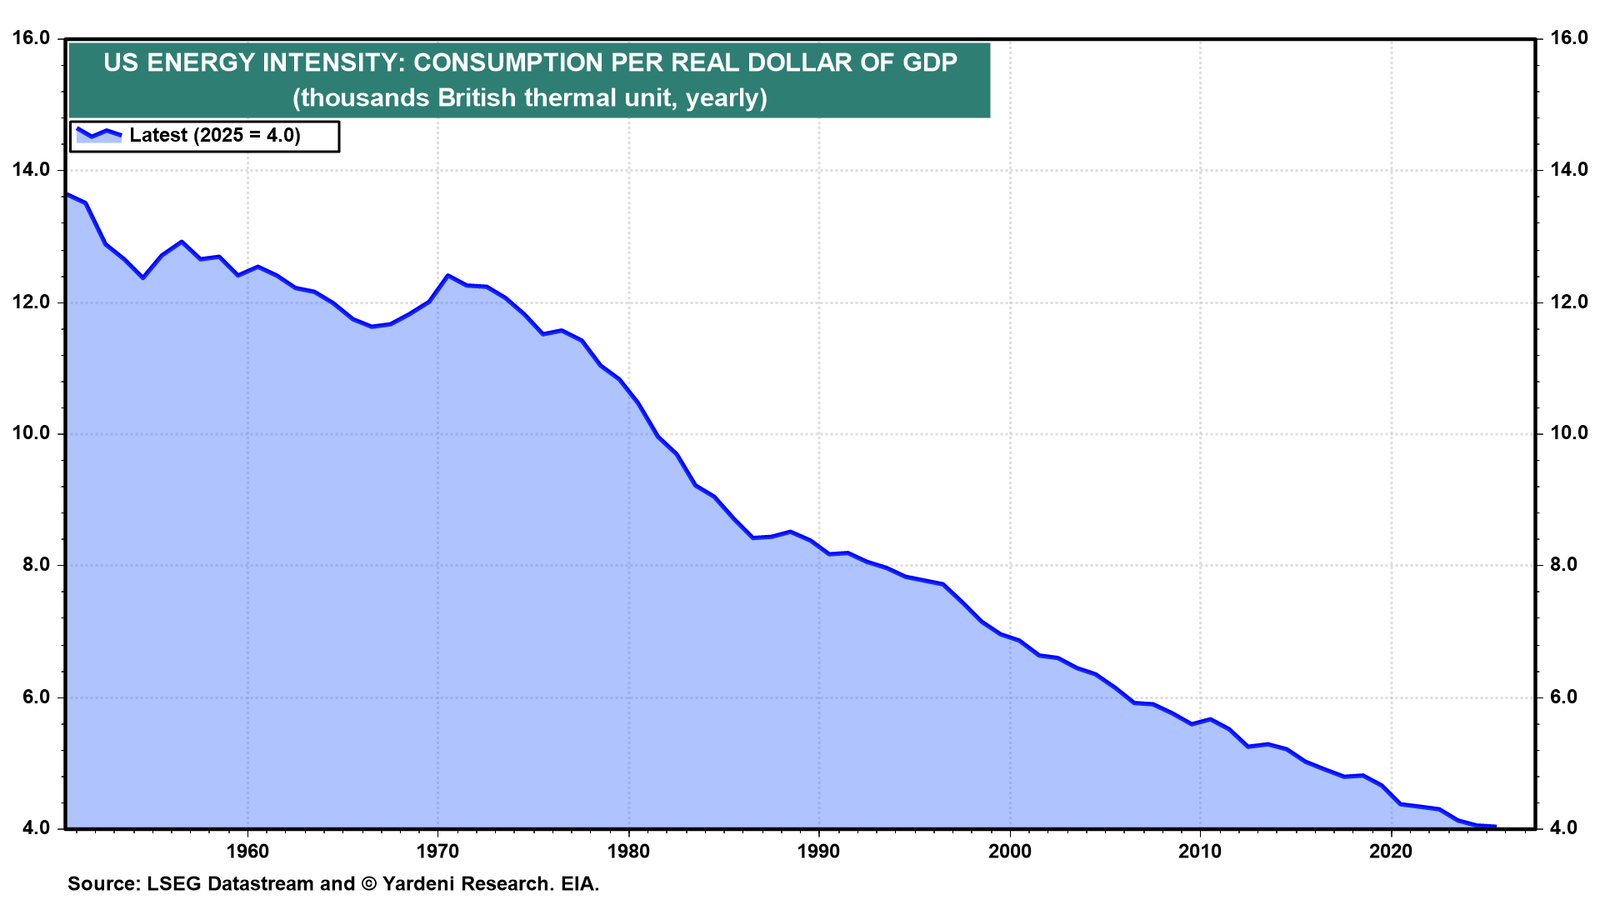
Offsetting some of these risks, the US economy is far less energy-intensive than in past decades, making it less vulnerable to oil price shocks (chart).
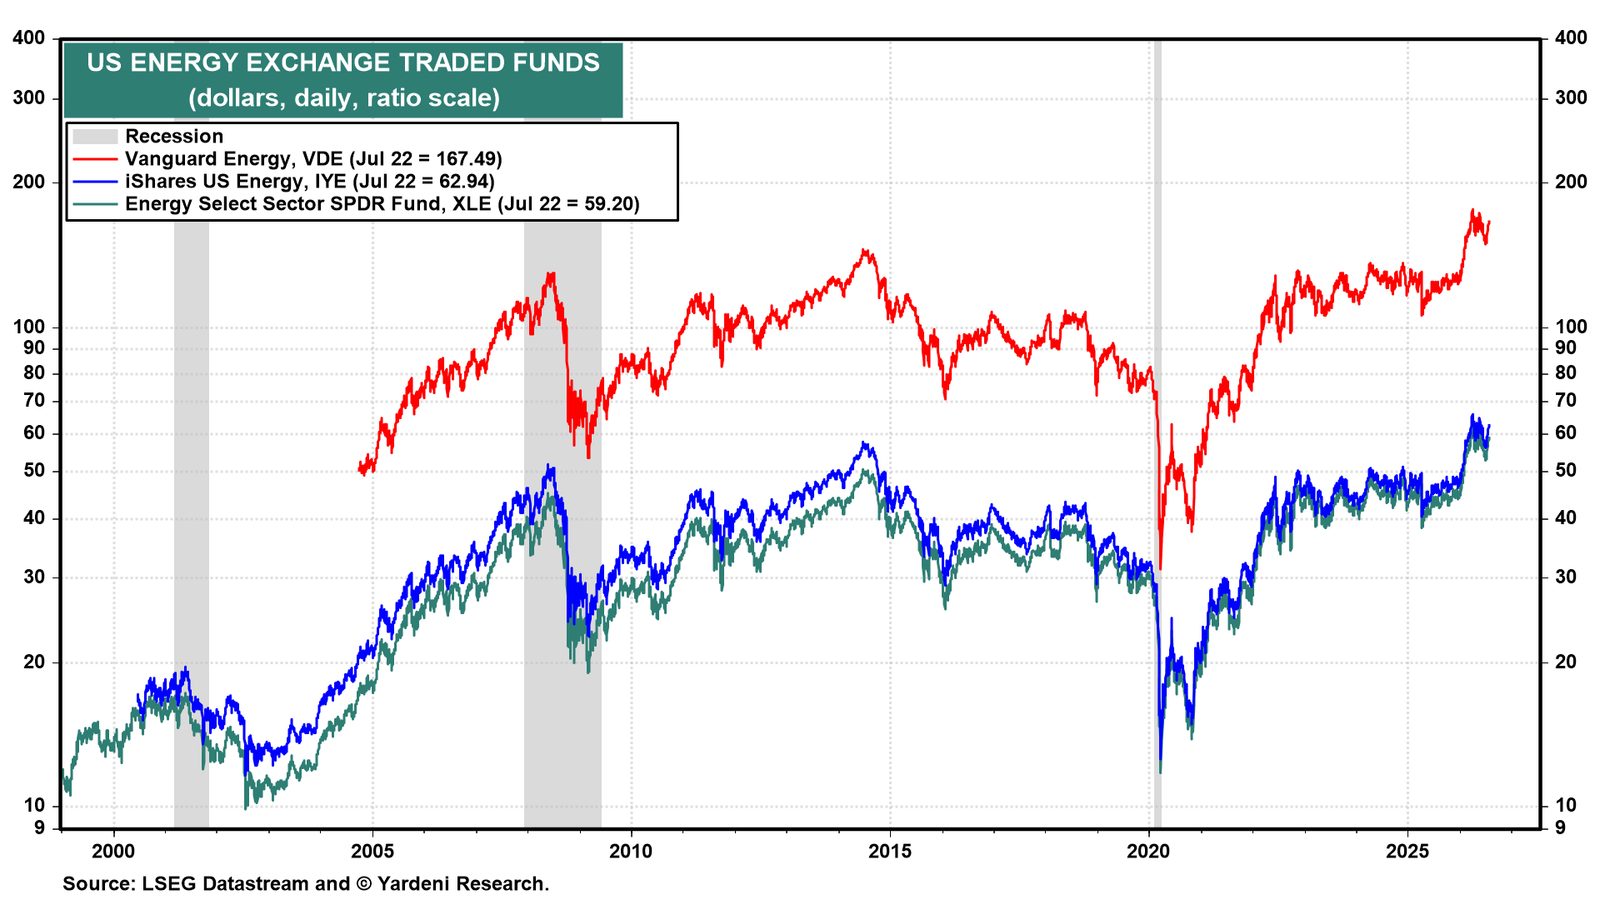
We continue to recommend overweighting Energy stocks. Energy ETFs rebounded today and may be set to rise to record highs (chart). They are certainly a good hedge against further disruption to oil shipments in the key choke points of the Middle East.
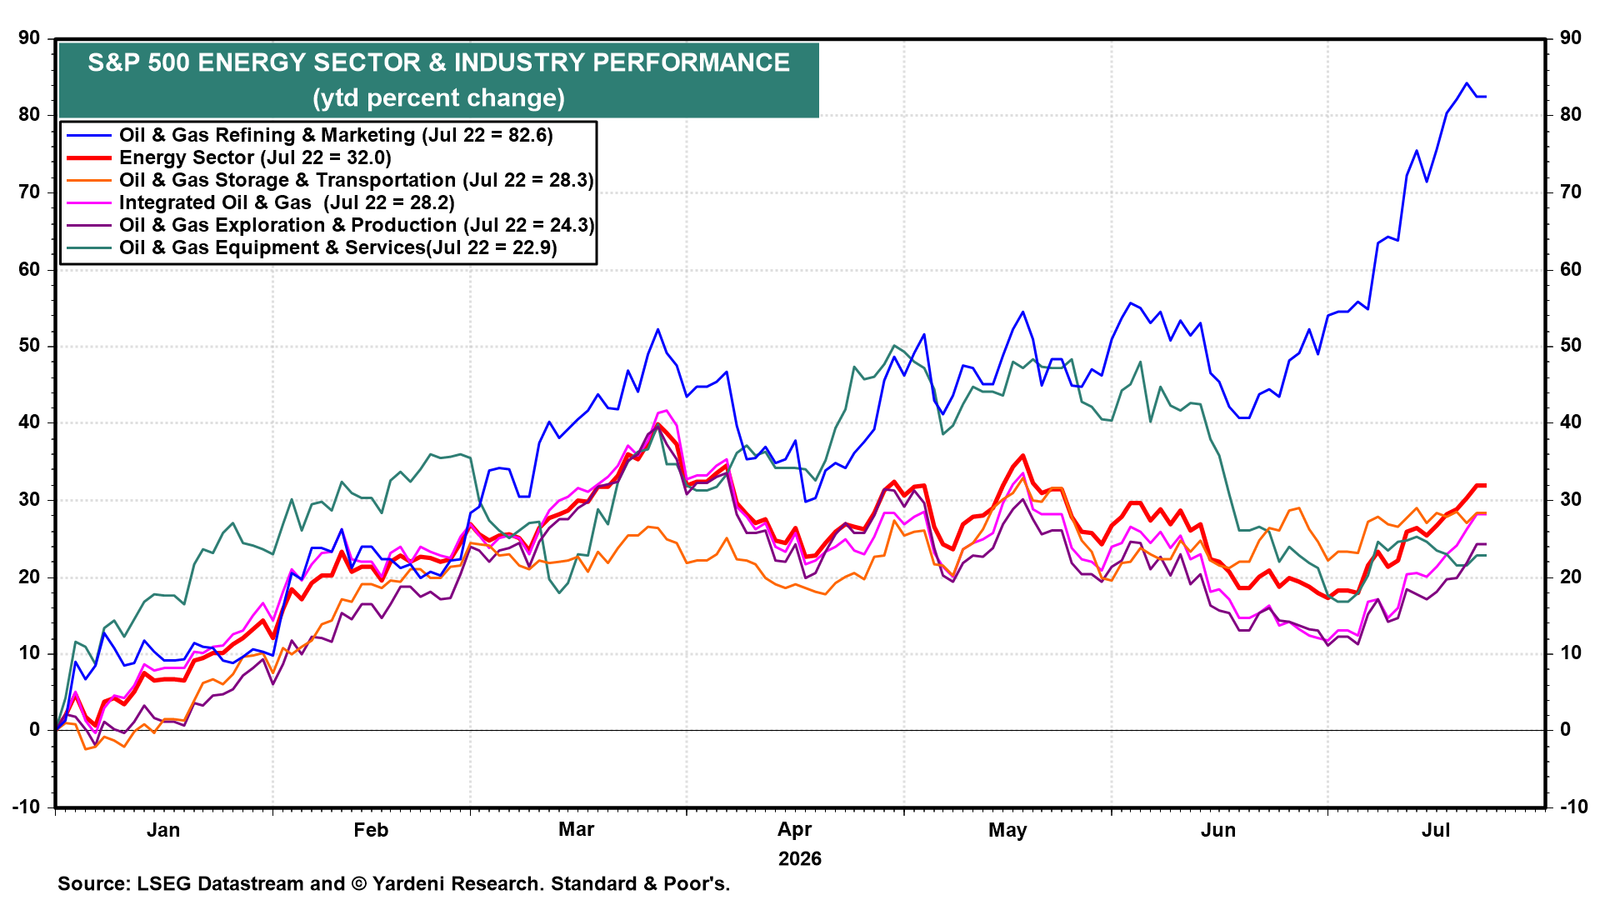
In S&P 500 Energy, Oil & Gas Refining & Marketing has been the best-performing industry in the sector so far this year (chart).
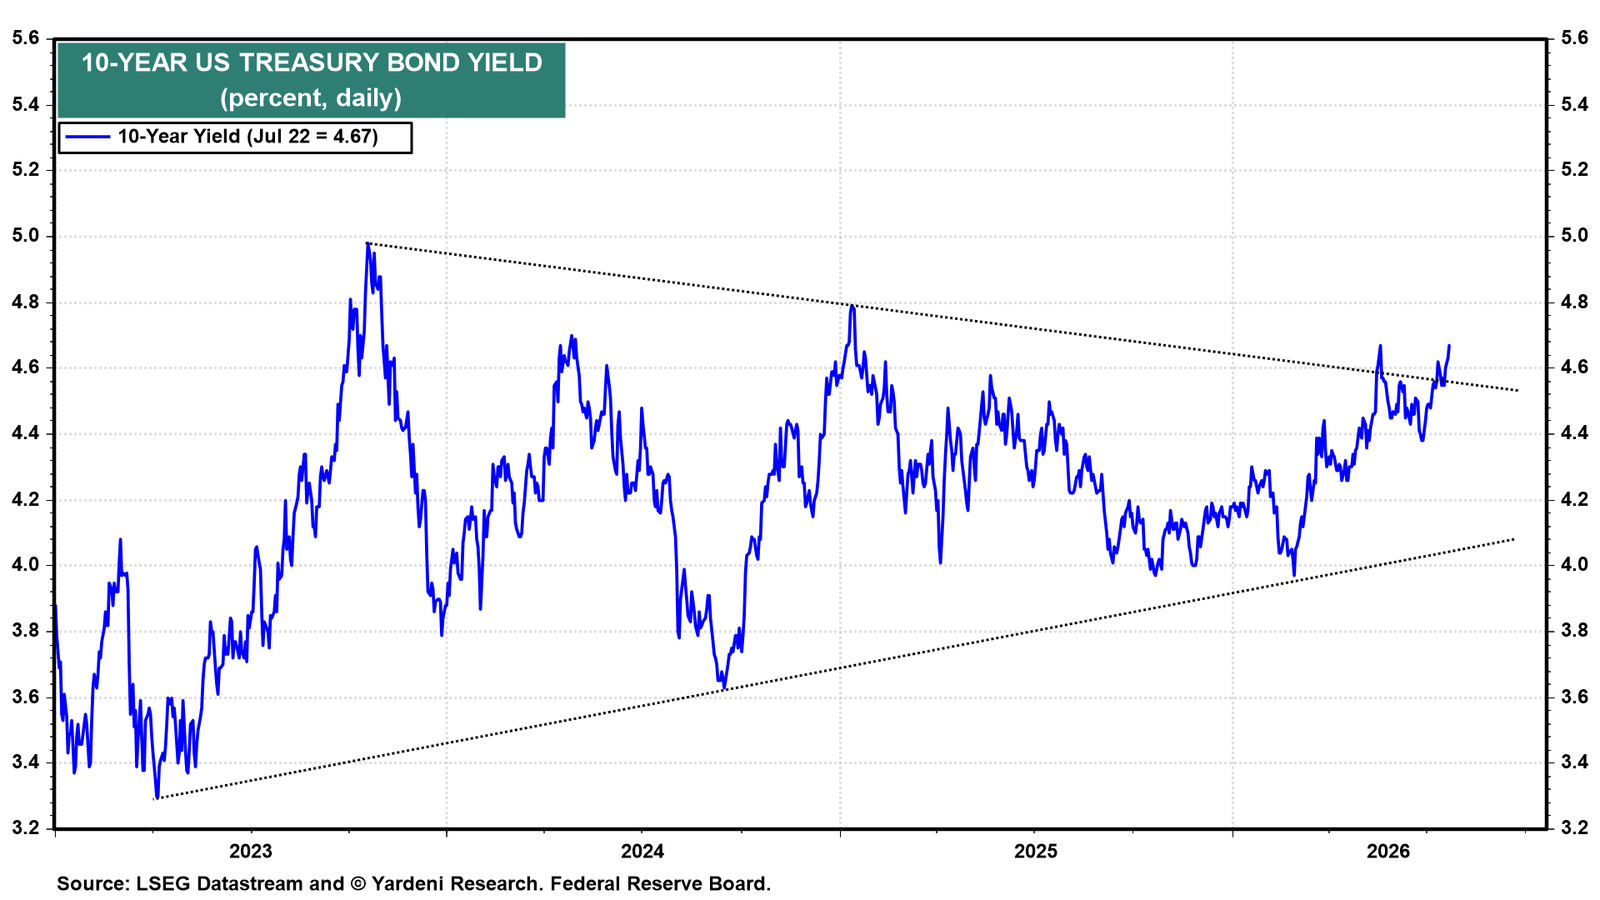
(2) Bonds. The 10-year Treasury bond yield is back up to 4.63% (chart). The move reflects concerns about the inflationary consequences of the rebound in oil prices. The upward pressure on bond yields is another reason to expect a summer stall in the stock market.
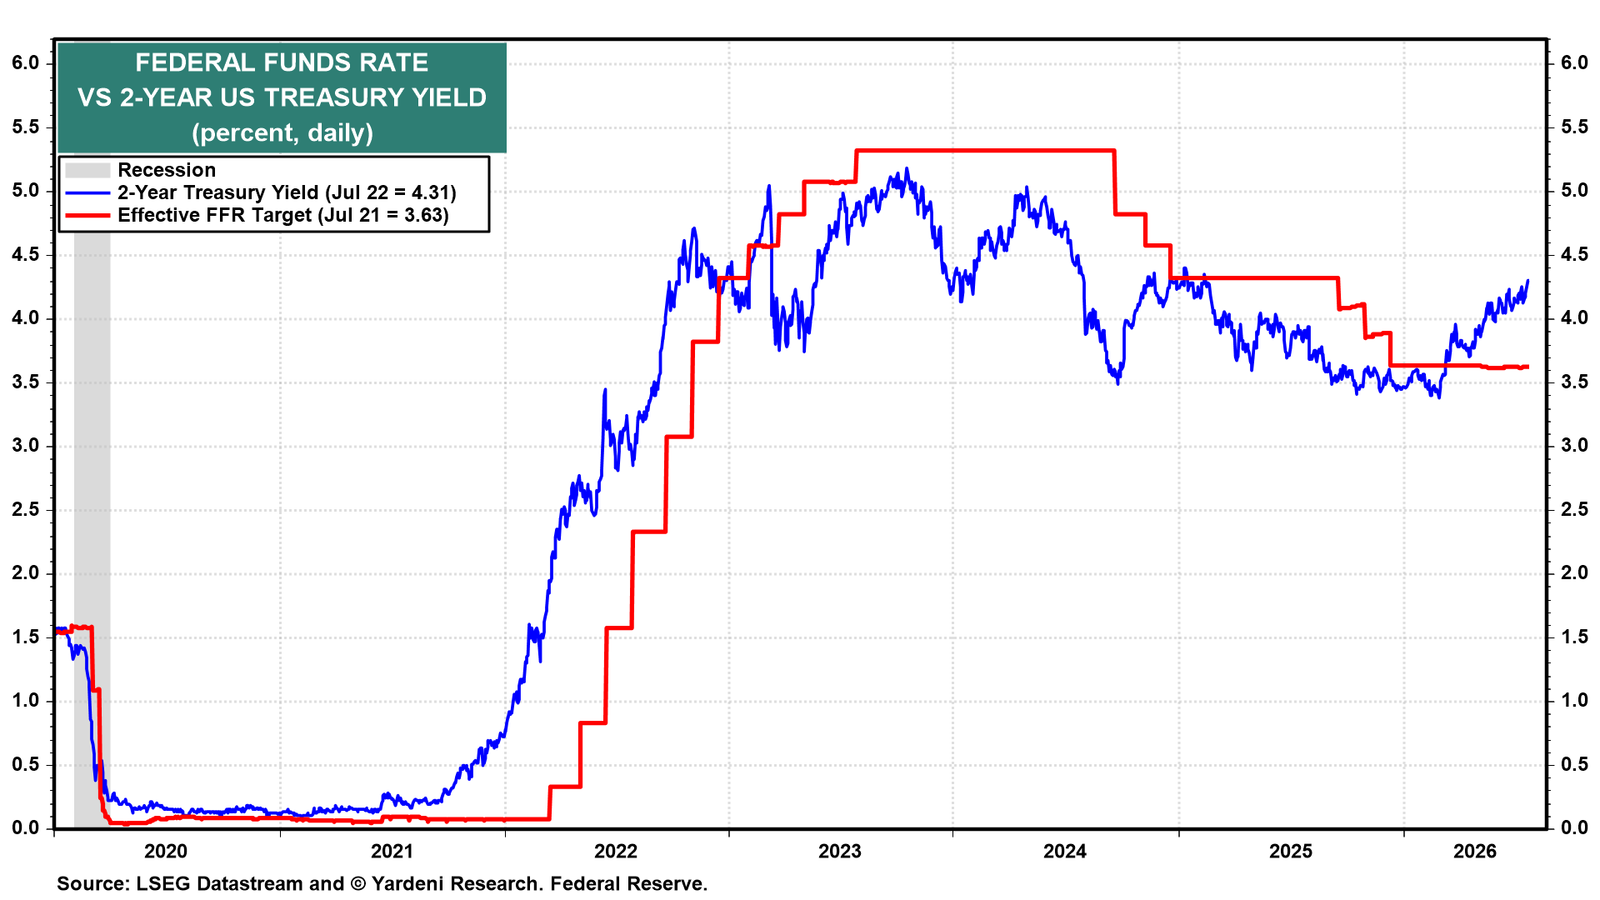
The 2-year Treasury note yield continues to rise above the federal funds rate (FFR) (chart). This signals that the market expects the Fed to hike the FFR soon. The odds of a rate hike are currently 35% for July and 55% for September. That makes sense to us.
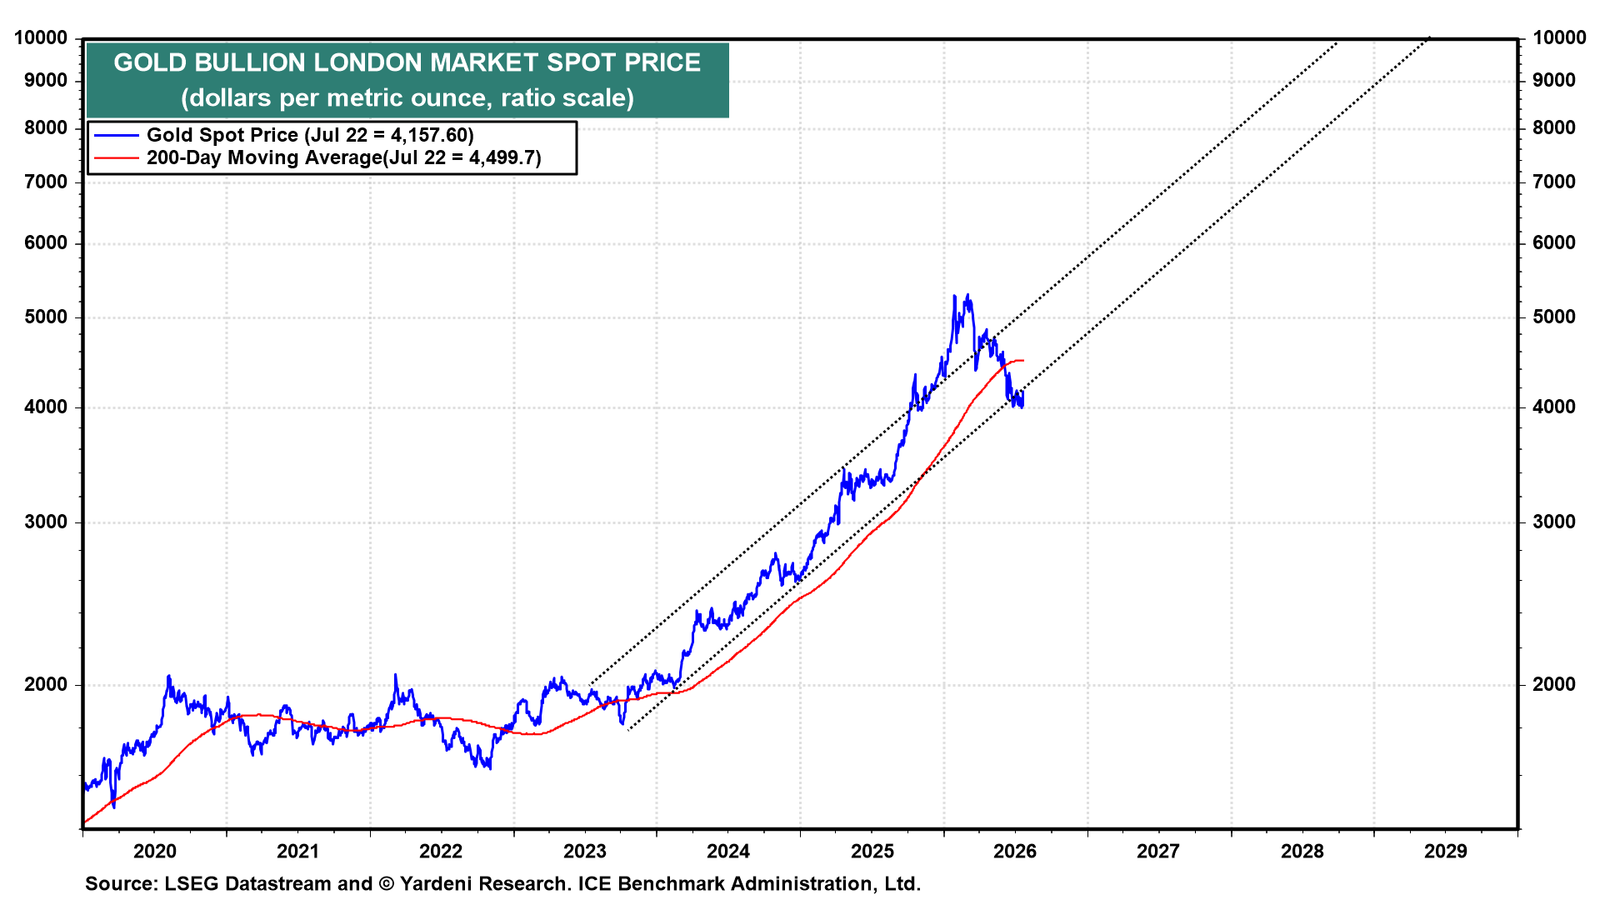
(3) Gold. The price of an ounce of gold has found support at the $4,000 level, which has held up well despite the recent strength in the dollar (charts). The World Gold Council has reported strong institutional demand, with a historic 45% of central banks expecting to increase their gold holdings over the next 12 months. We've been bullish on gold since it rose above $2,000 on central bank buying. We still are.
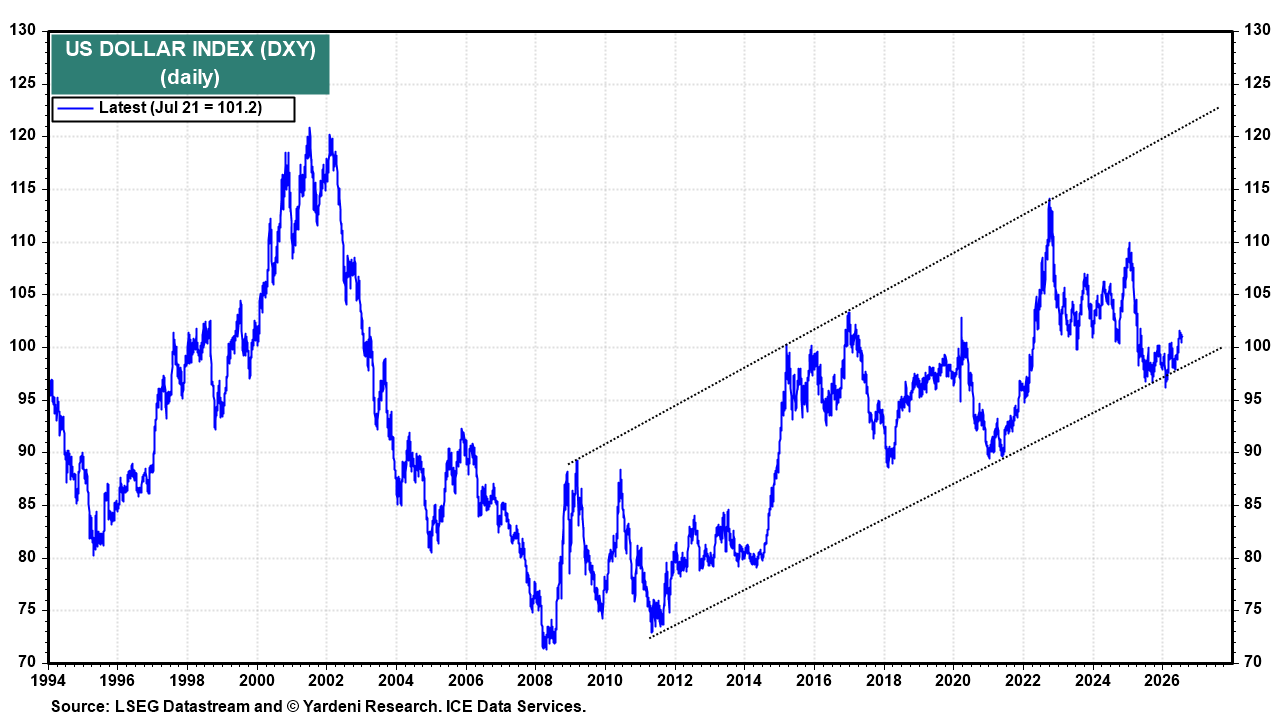
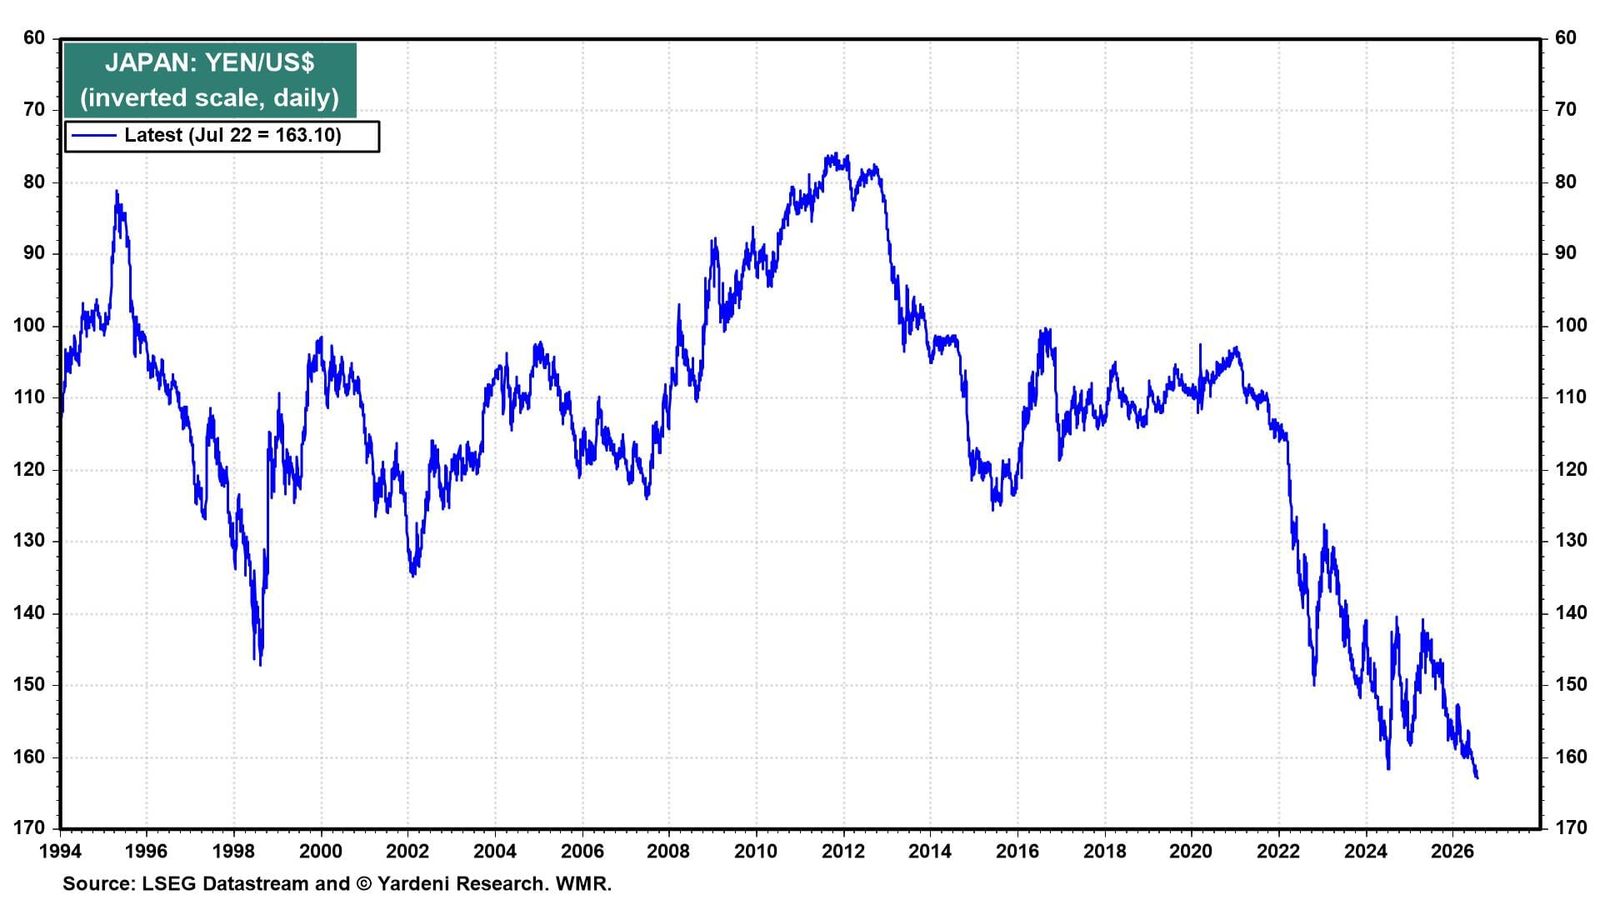
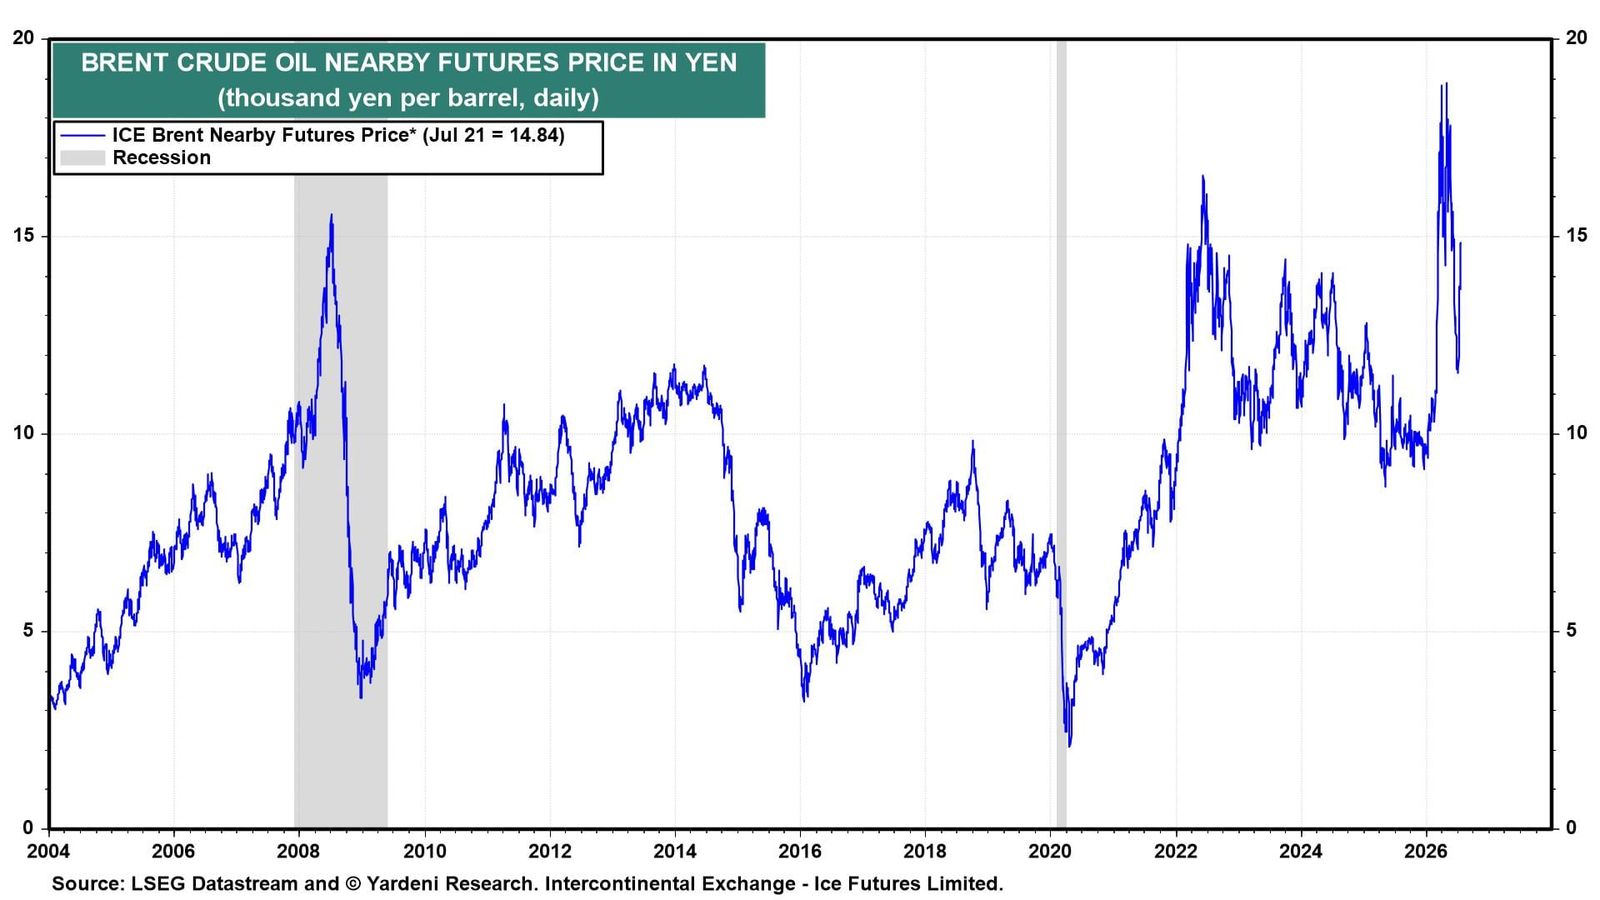
(4) Yen. The yen rounds out the worry list. It has slumped below 163 yen per dollar (charts). That's the weakest reading since 1986, despite reports from Bloomberg that the BOJ will accelerate rate hikes. Japan faces several pressures at once. Higher oil prices are inflating Japan's energy import bill; the weak yen boosts that cost, and rising US Treasury yields keep the rate gap wide, encouraging carry trades. Fiscal concerns over how the government will fund large spending plans further sap confidence.