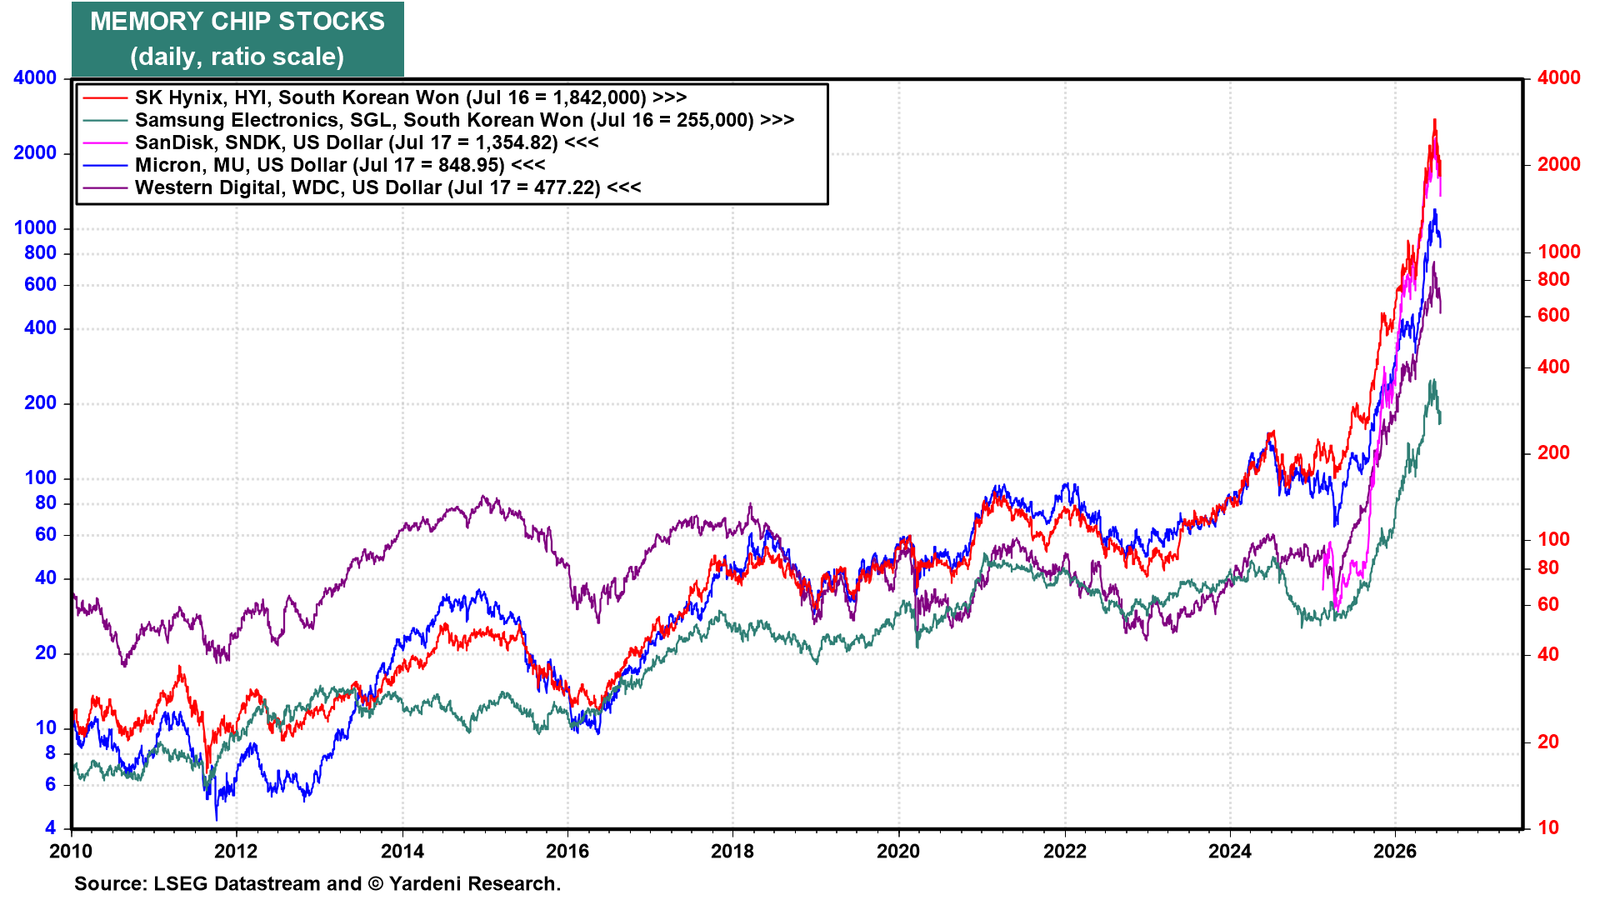
The S&P 500 is 2.0% below its June 2 all-time high. It has been hovering around 7,500 since May 14. Beneath that calm, momentum stocks have been hard hit. The semiconductor index (SOXX) is down 20.3% from its June 22 peak. The Roundhill Memory ETF (DRAM), which started trading on April 2 around $28 and soared 208% to $80.7 on June 22, is down 35% since then.
These developments have all weighed on the S&P 500 Information Technology sector, which we downgraded to market weight on December 7, 2025. Meanwhile, Financials and Health Care, which we are overweight, have held up well. Investment banking is booming. Biotech is performing very well.
Here's what has gotten our attention recently:
(1) Technology: Semiconductors and Memory Correct. Margin calls on Samsung and SK Hynix in South Korea weighed on US semiconductor and memory chip stocks in recent days. Chinese AI lab Moonshot added to the pressure on Friday, launching Kimi K3, a 2.8-trillion-parameter open-weight model it says rivals the best from OpenAI and Anthropic, reviving DeepSeek-era fears and pushing the SOXX lower. The S&P 500 Semiconductors stock price index is likely to fall another 12% to its 200-day moving average (chart).
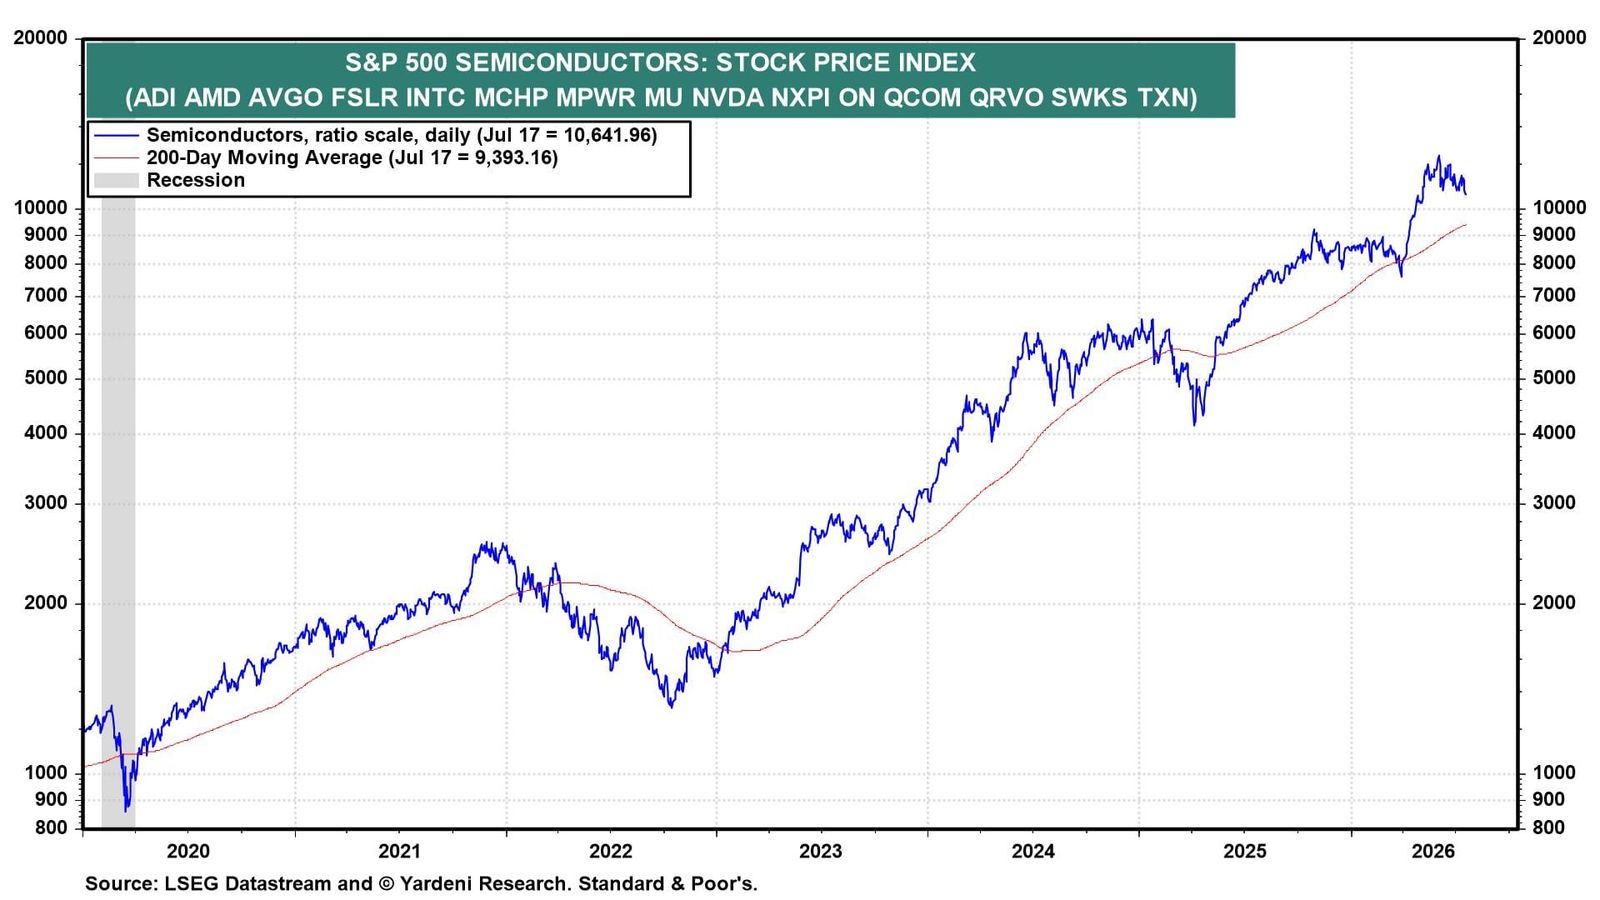
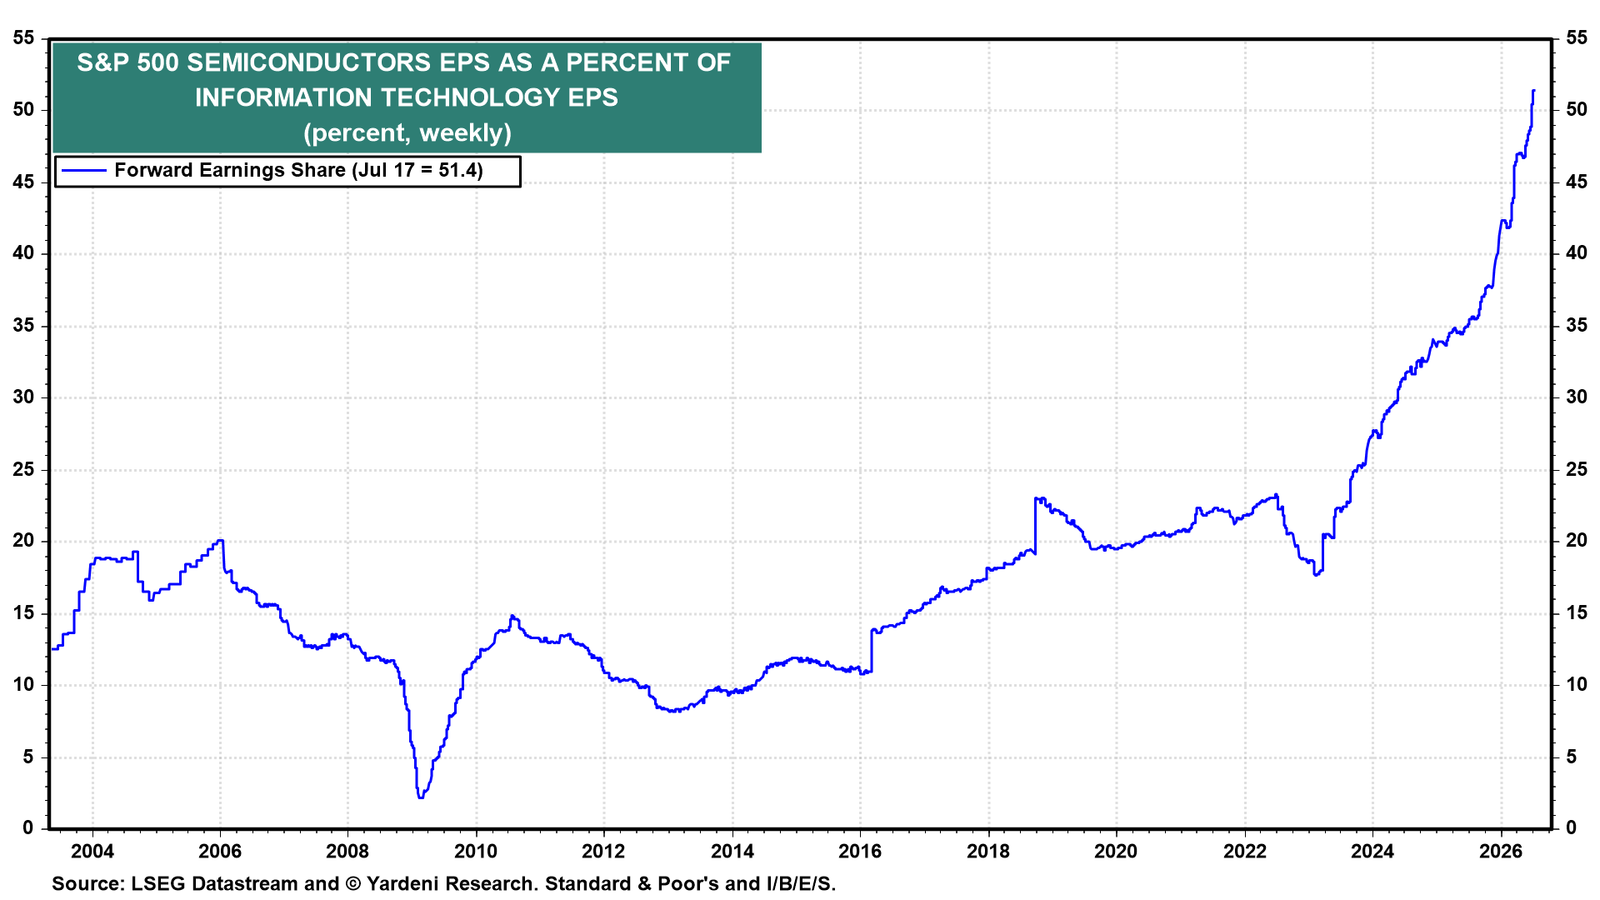
Semiconductors' fundamentals are great. But investors are worried that they might not be sustainable. S&P 500 Semiconductor earnings are expected to grow 106.5% in 2026, up from 25% at the start of 2025, and now make up 51% of Information Technology sector earnings, more than double the share from three years ago (chart).
We flagged the bullish outlook for memory stocks on March 23, when SK Hynix, Micron, and SanDisk traded at a fraction of today's levels. All three roughly tripled and hit records in June (chart). They have been overdue for a correction, which seems to be underway now.
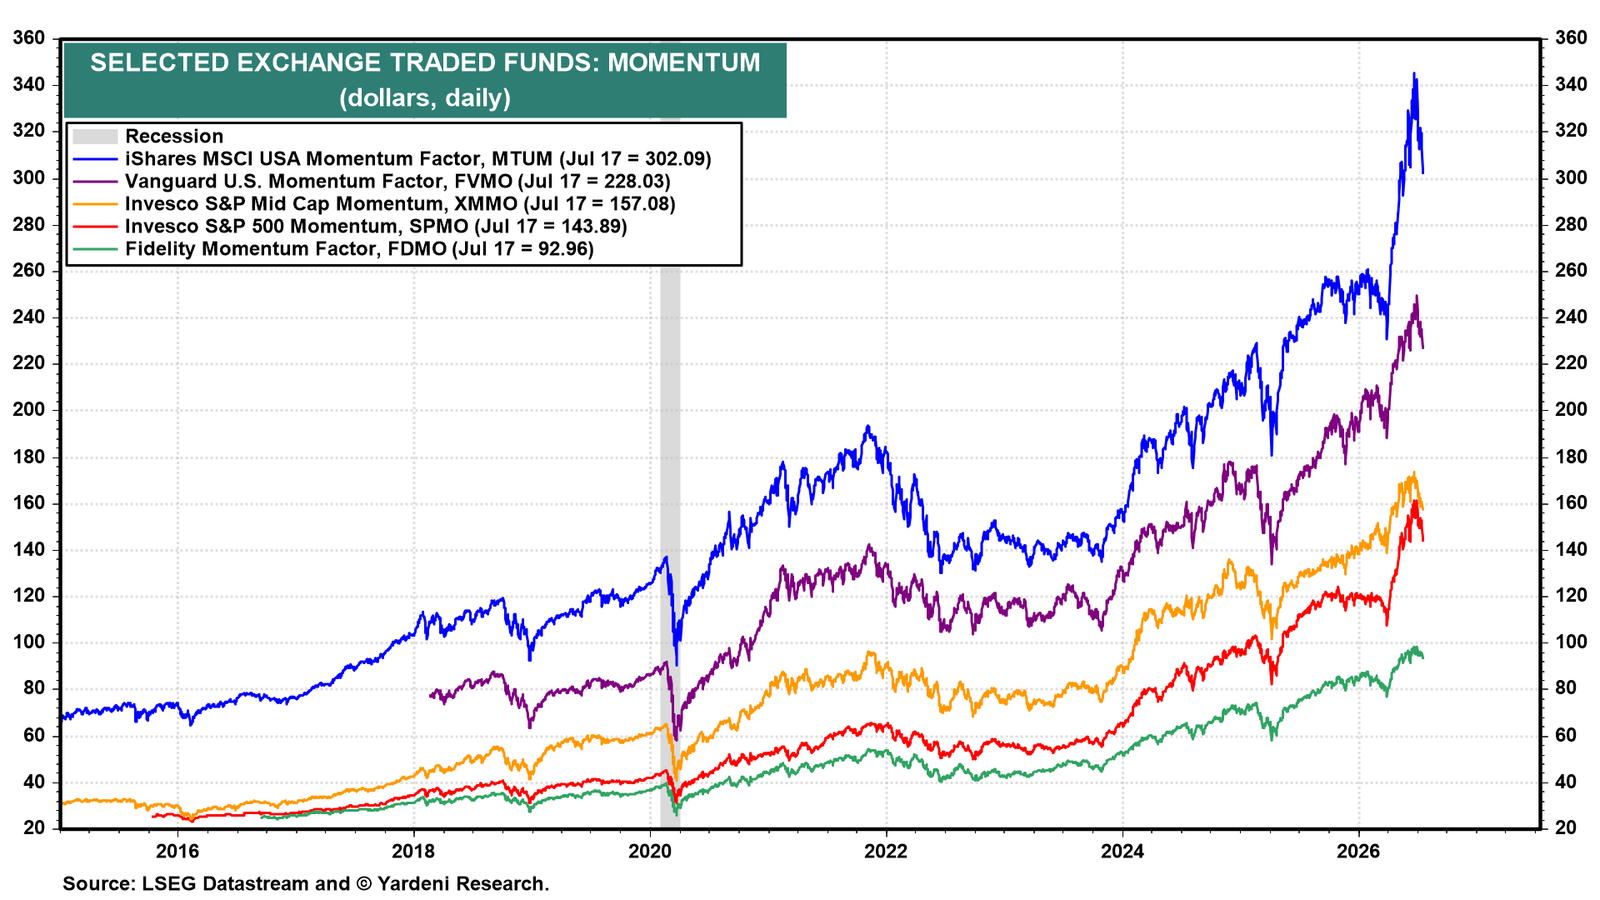
(2) Momentum is also hurting. Momentum stocks have had a strong run. The investment style is now more than 12% below its June 22 peak, according to the iShares MSCI USA Momentum Factor (MTUM) ETF (chart).
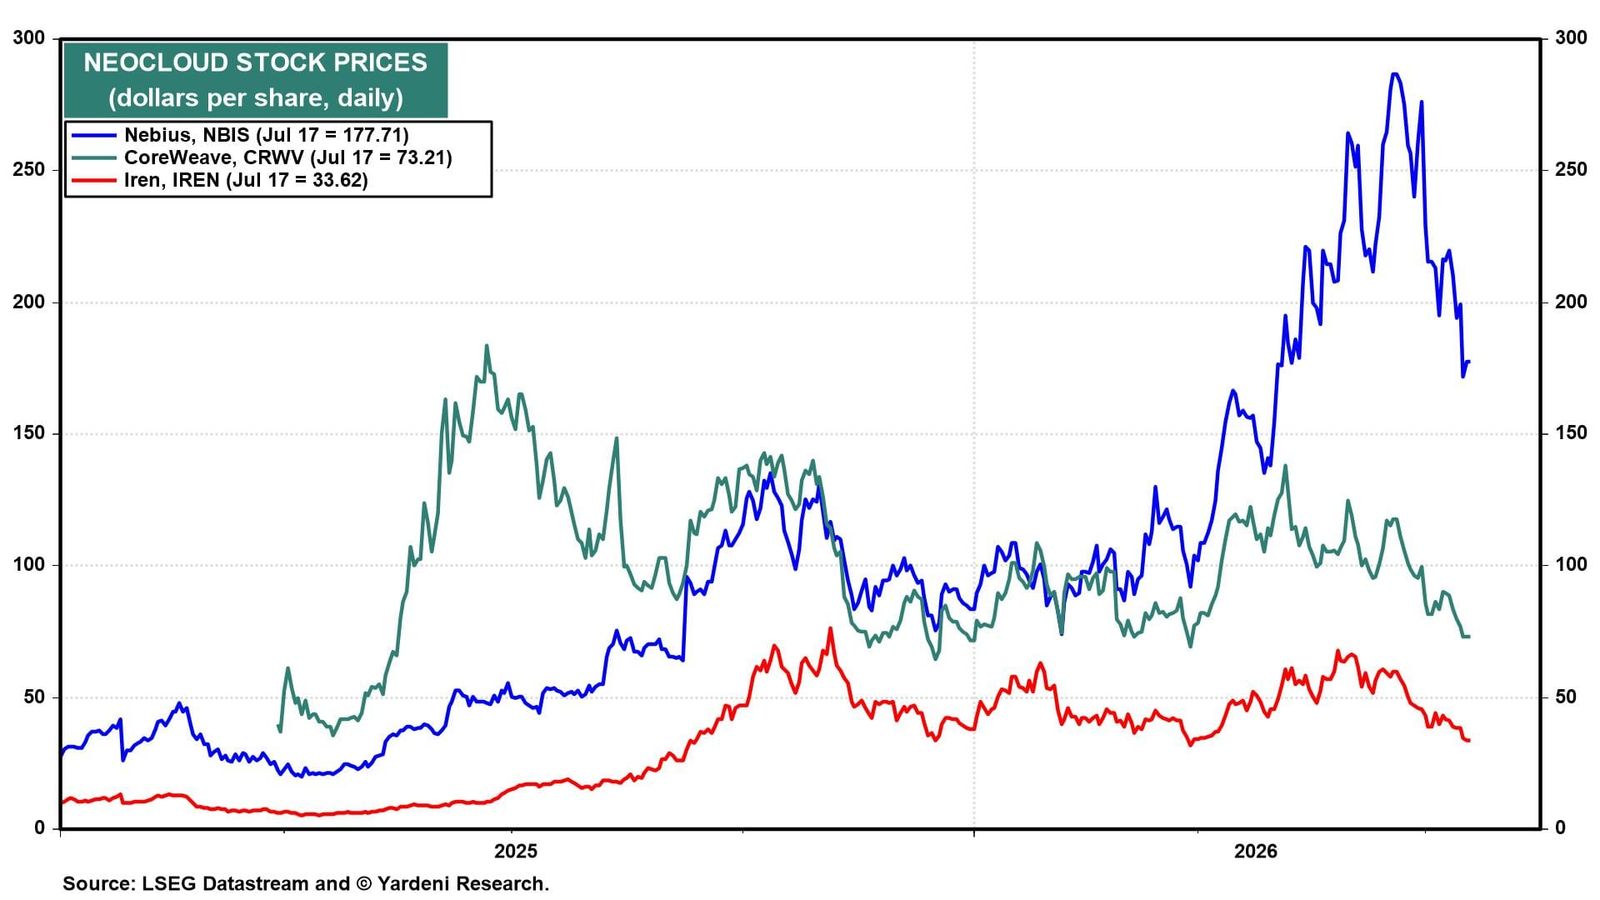
The same unwind hitting memory has shown up harder in other corners of the AI trade. Neocloud operators renting out GPU capacity have been hit hardest. Nebius, CoreWeave, and IREN have all fallen 40%-50% from their 2026 peaks since Meta signaled in May plans to compete directly by selling its own excess computing capacity (chart).
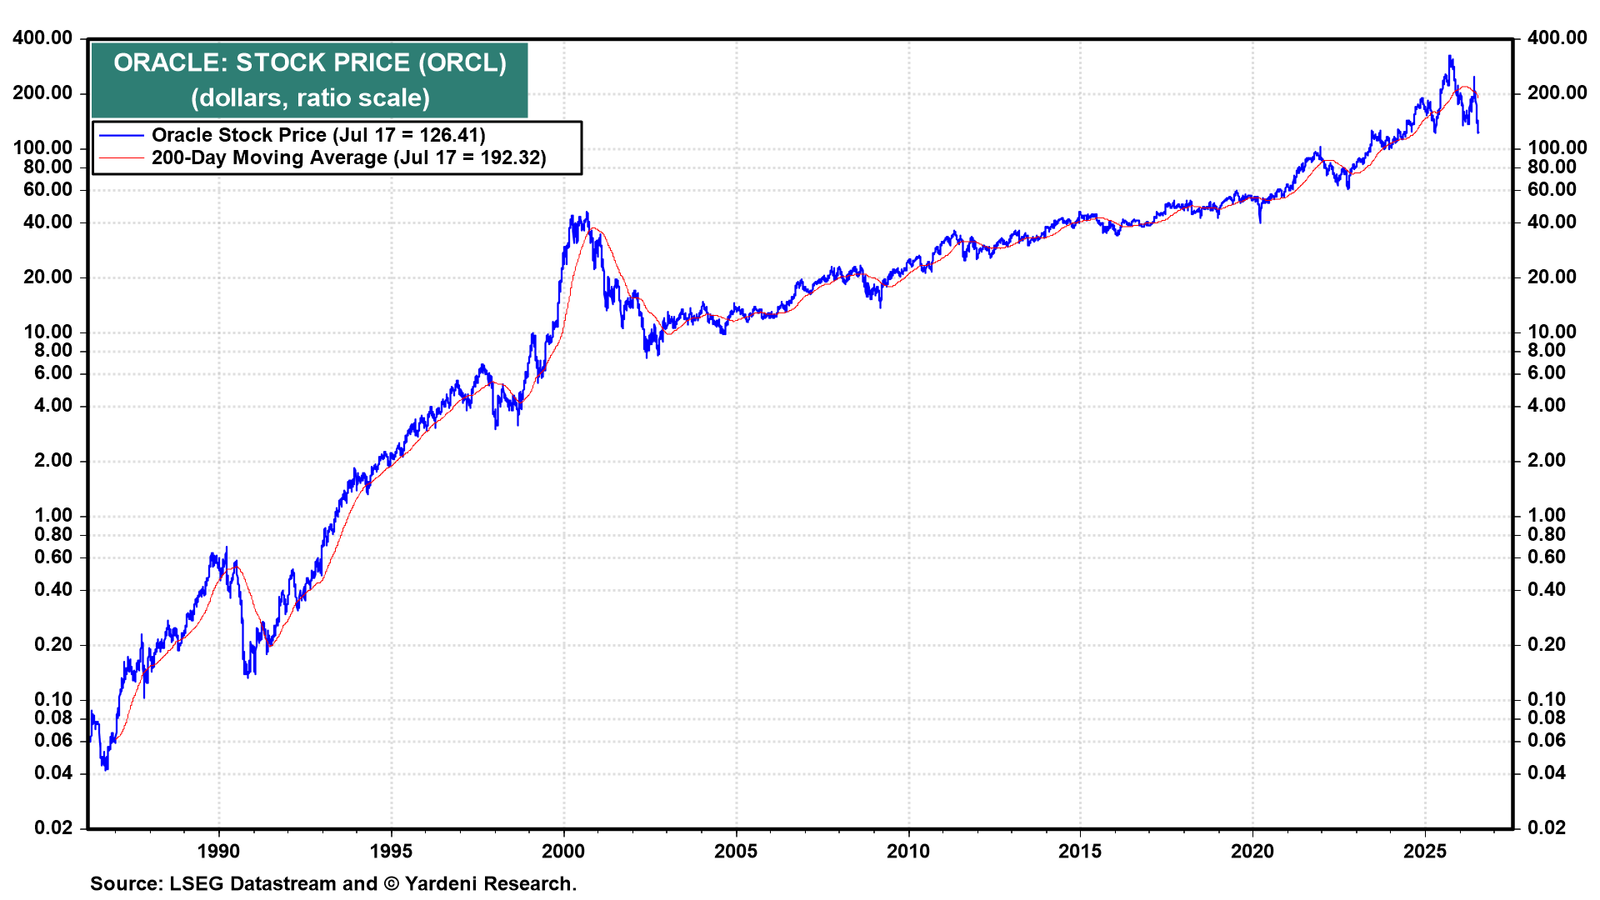
Oracle peaked at a record high of $328 on September 18 last year. It is down 61.5% since then, suggesting that investors are questioning whether its biggest customer, OpenAI, will be able to pay its bills (chart).
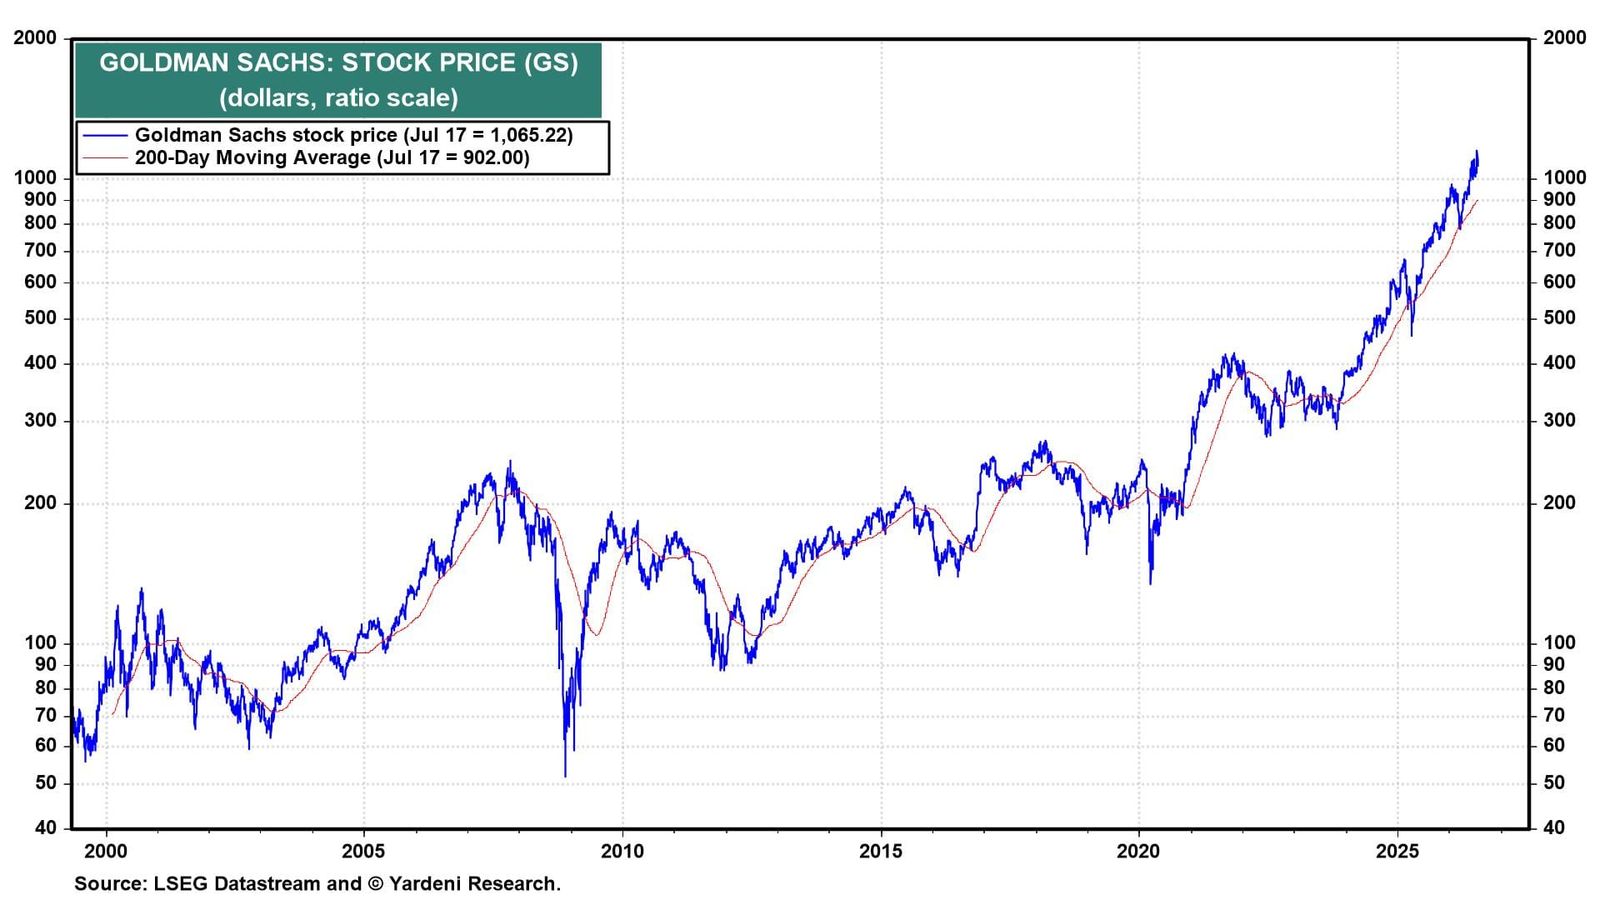
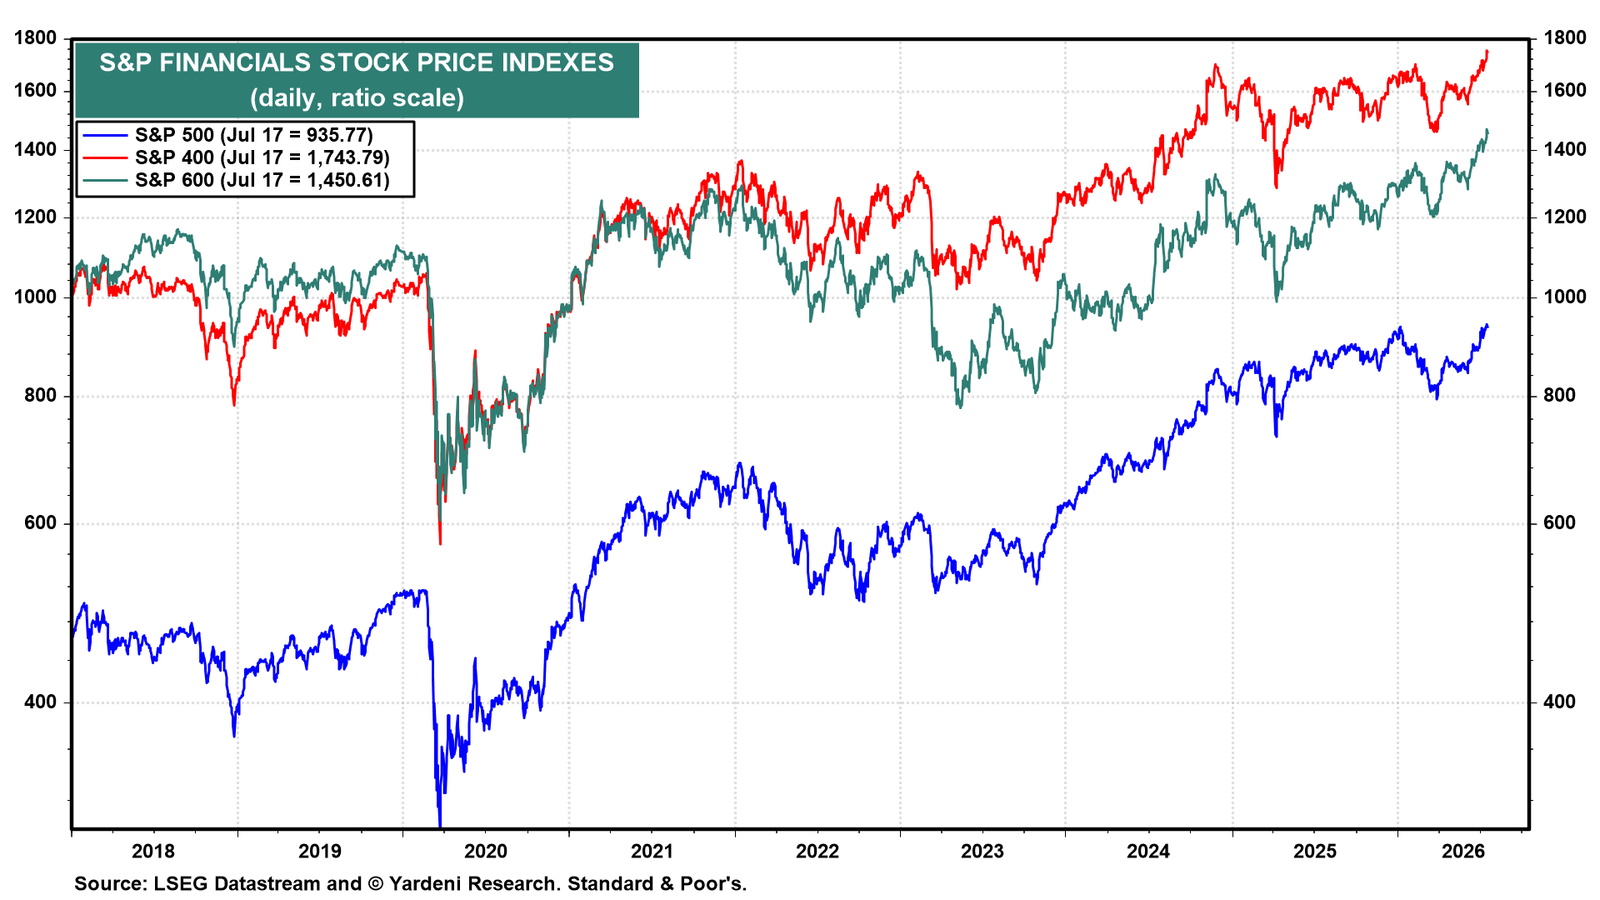
(3) Financials: Great Earnings Beat Great Expectations. Last week's big bank earnings reports were solid, led by a blockbuster one from Goldman Sachs. The firm posted record Q2 revenues and EPS. Shares jumped to yet another record high (chart).
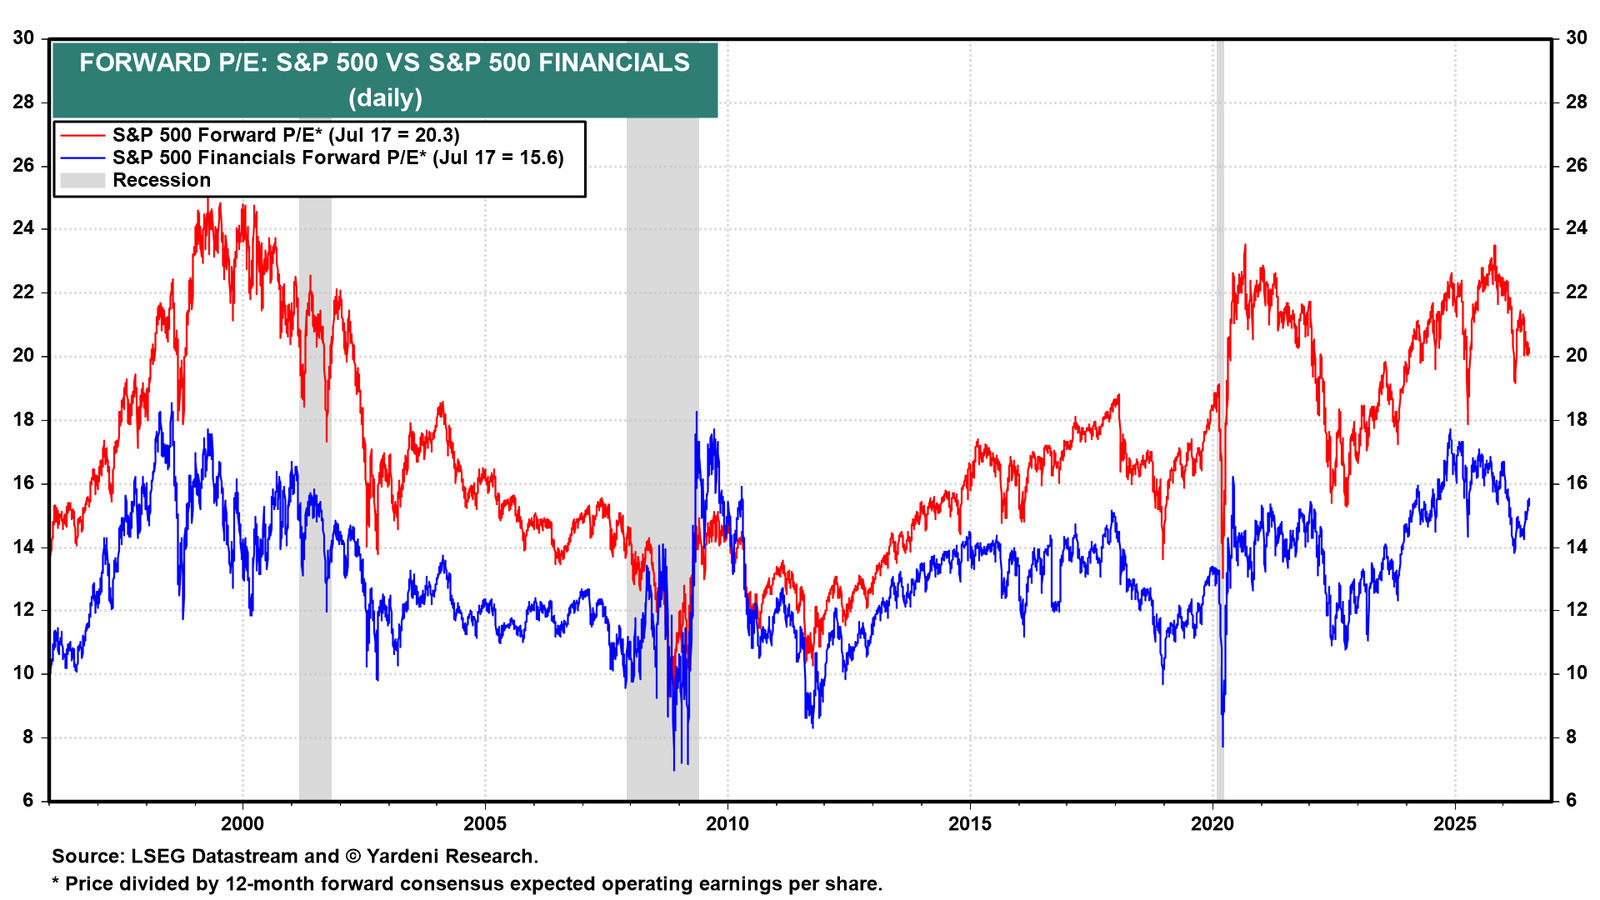
JPMorgan, Citi, Bank of America, Wells Fargo, and Morgan Stanley all beat estimates too. The case goes beyond one quarter. Financials carry a 21.6% forward profit margin, second only to Technology, and a forward P/E of just 15.6, above only Energy (chart).
The S&P 500/400/600 stock price indexes are all breaking out to new record highs (chart).
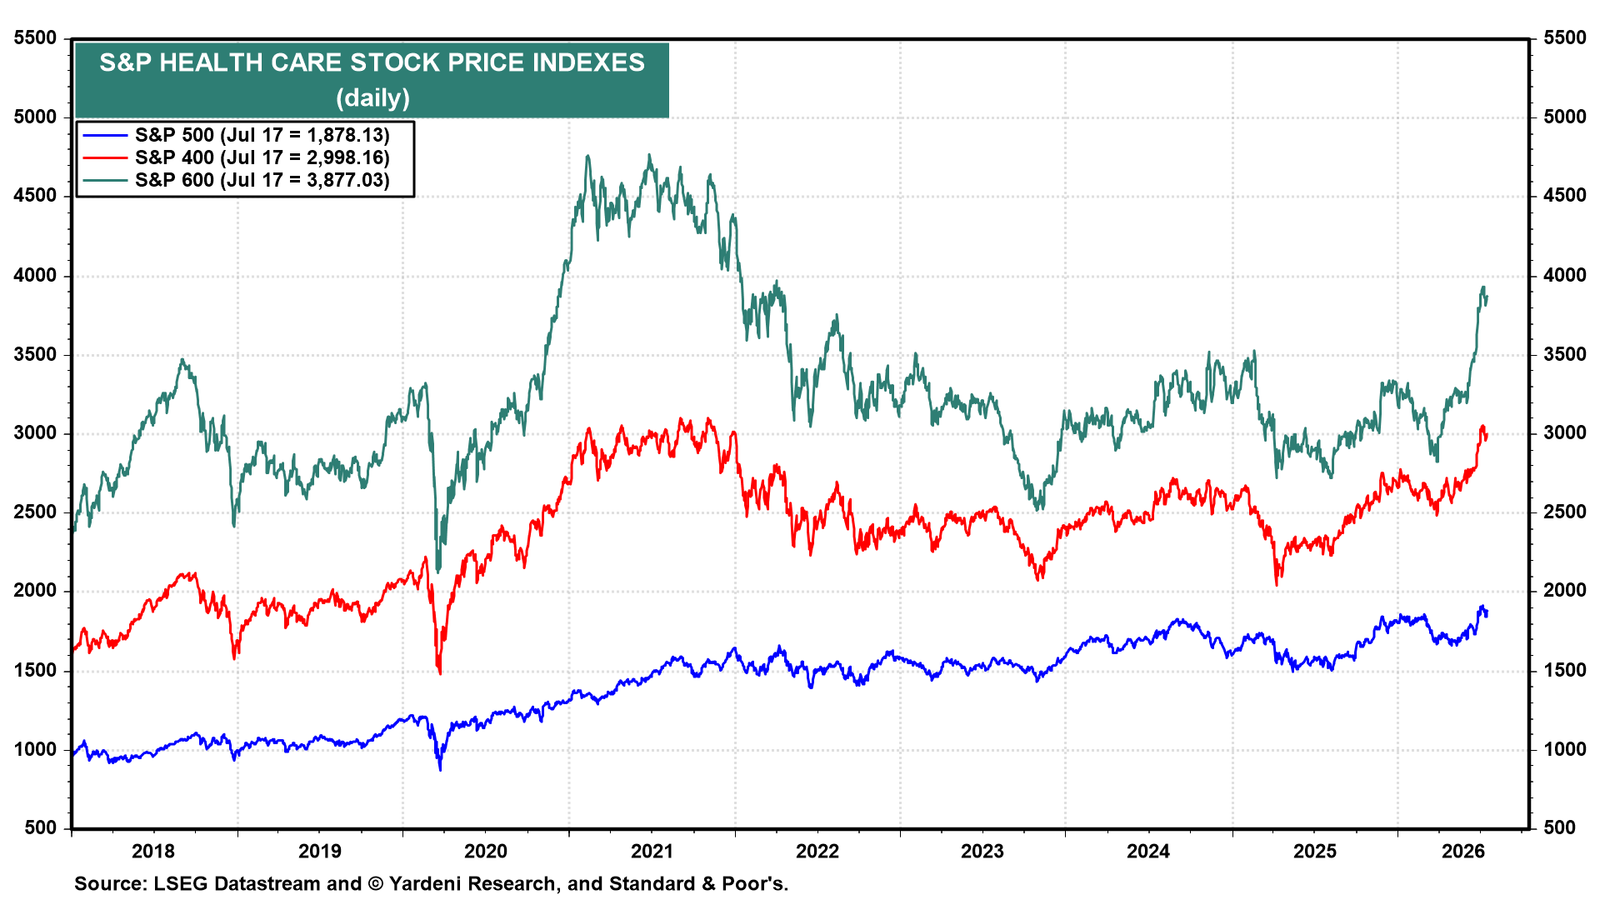
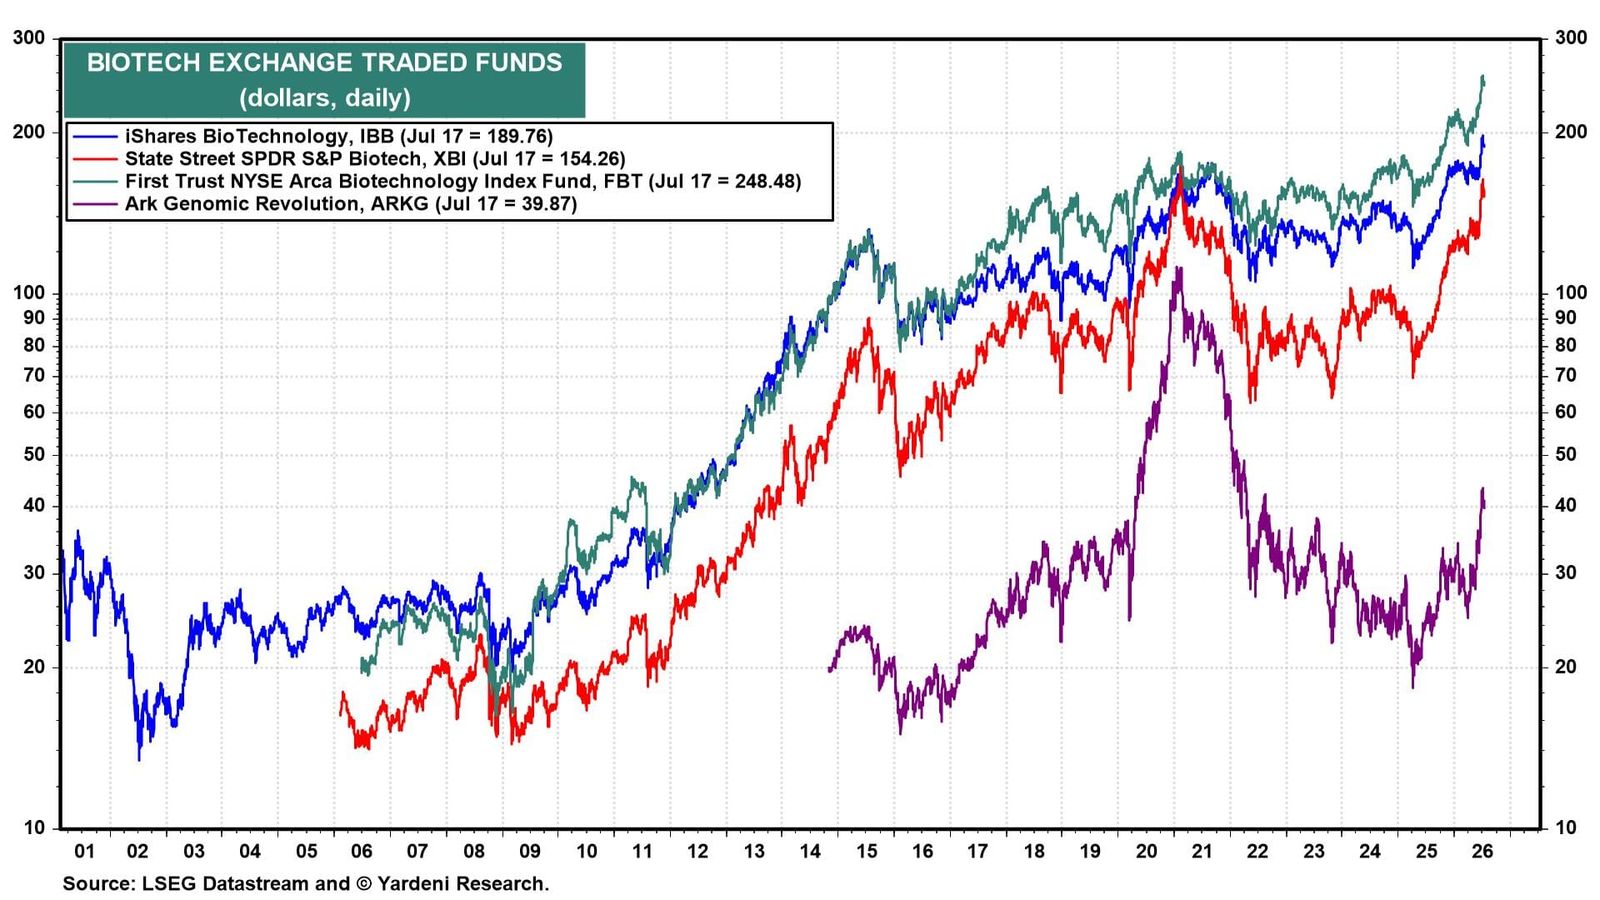
(4) Health Care: Biotech & Pharma Out Of Their Commas. Health Care is finally performing better after years of lagging the market. Biotech ETFs are soaring. The IBB ETF is at a record high (chart). A wave of M&A is driving the biotech rally. Big pharma companies are racing to buy growth ahead of a looming patent cliff, alongside a steady run of FDA approvals and positive trial readouts.
The broader sector confirms the same story. S&P 600 small-cap Health Care has surged to fresh highs, well ahead of both the S&P 400 and S&P 500 (chart).