In our March 4, 2026 QuickTakes, we wrote that the war between the US and Iran might last longer than widely expected. We suggested that any peace deal with Iran's government would effectively be vetoed by the Islamic Revolutionary Guard Corps simply by their threatening to attack ships sailing through the Strait of Hormuz. "These terrorists are likely to be hard to eradicate with just air power," we wrote.
The IRGC remains in control of the war. They fired at ships in the Strait in recent days, violating the interim US-Iran agreement signed last month that aimed to reopen the Strait and end the war after a further 60 days of negotiations. So the war has re-escalated.
Here’s what’s been going on in the global financial markets as a new week of war begins:
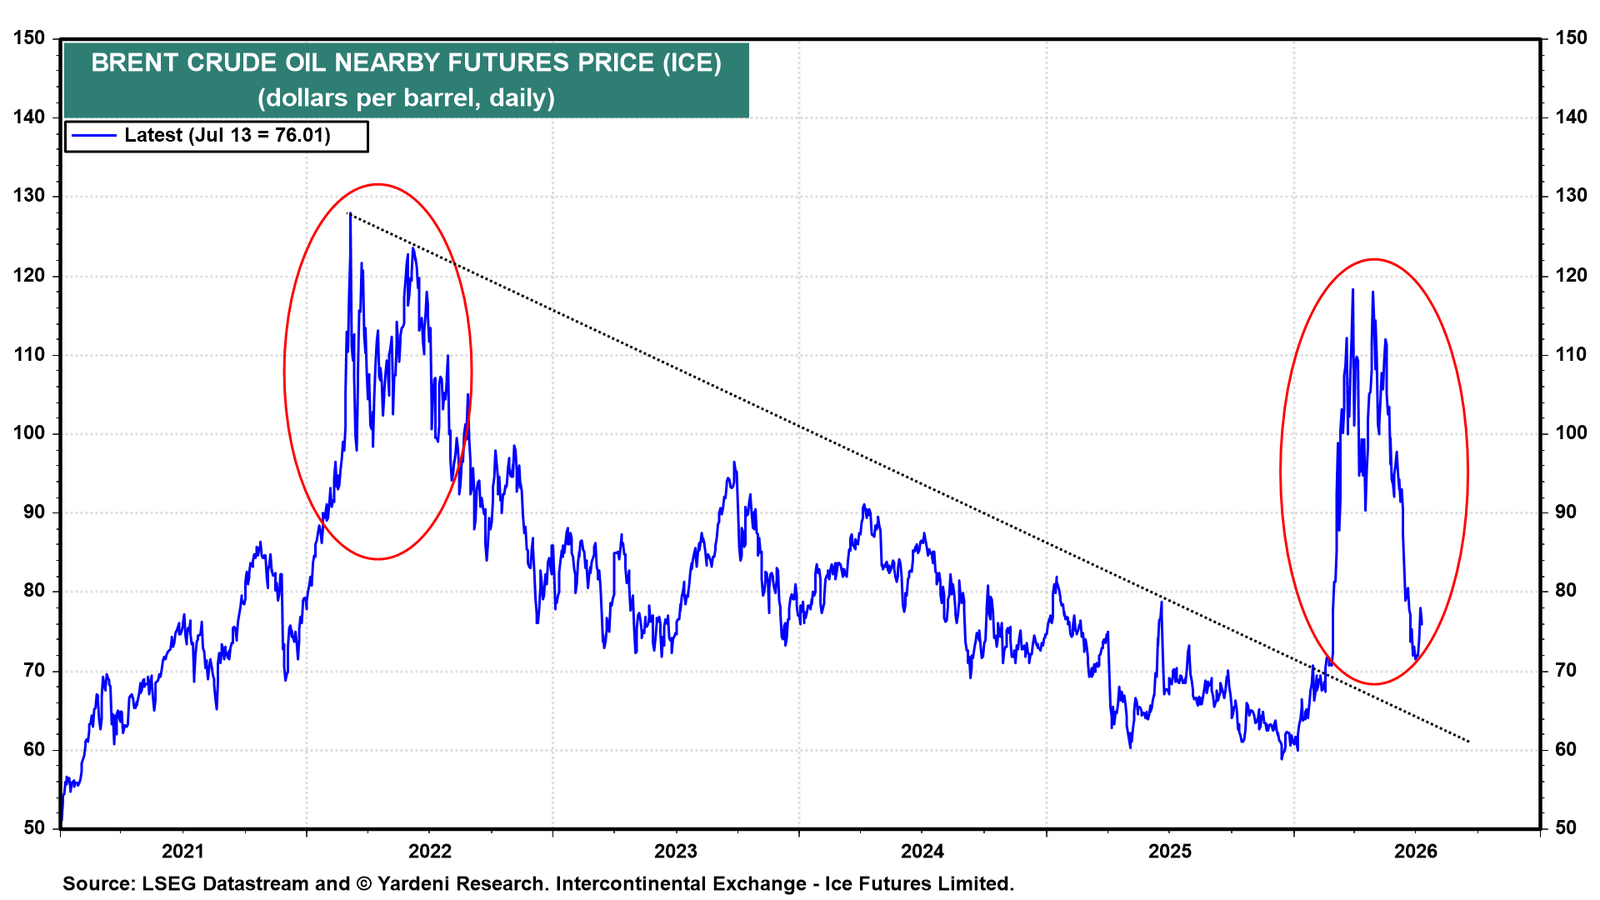
(1) Commodities. The price of a barrel of Brent crude oil rose 2.75% to $78.75 this evening. President Donald Trump said today that the Strait is open to commercial traffic, although Iran declared earlier that it had closed the Strait. The sharp drop in oil prices during June confirms that the war might have interrupted, but only briefly, a bear market in crude oil that started after Russia invaded Ukraine in 2022 (chart). That would explain why the disruption of oil supplies transiting the Strait hasn't had a much bigger impact on the oil price.
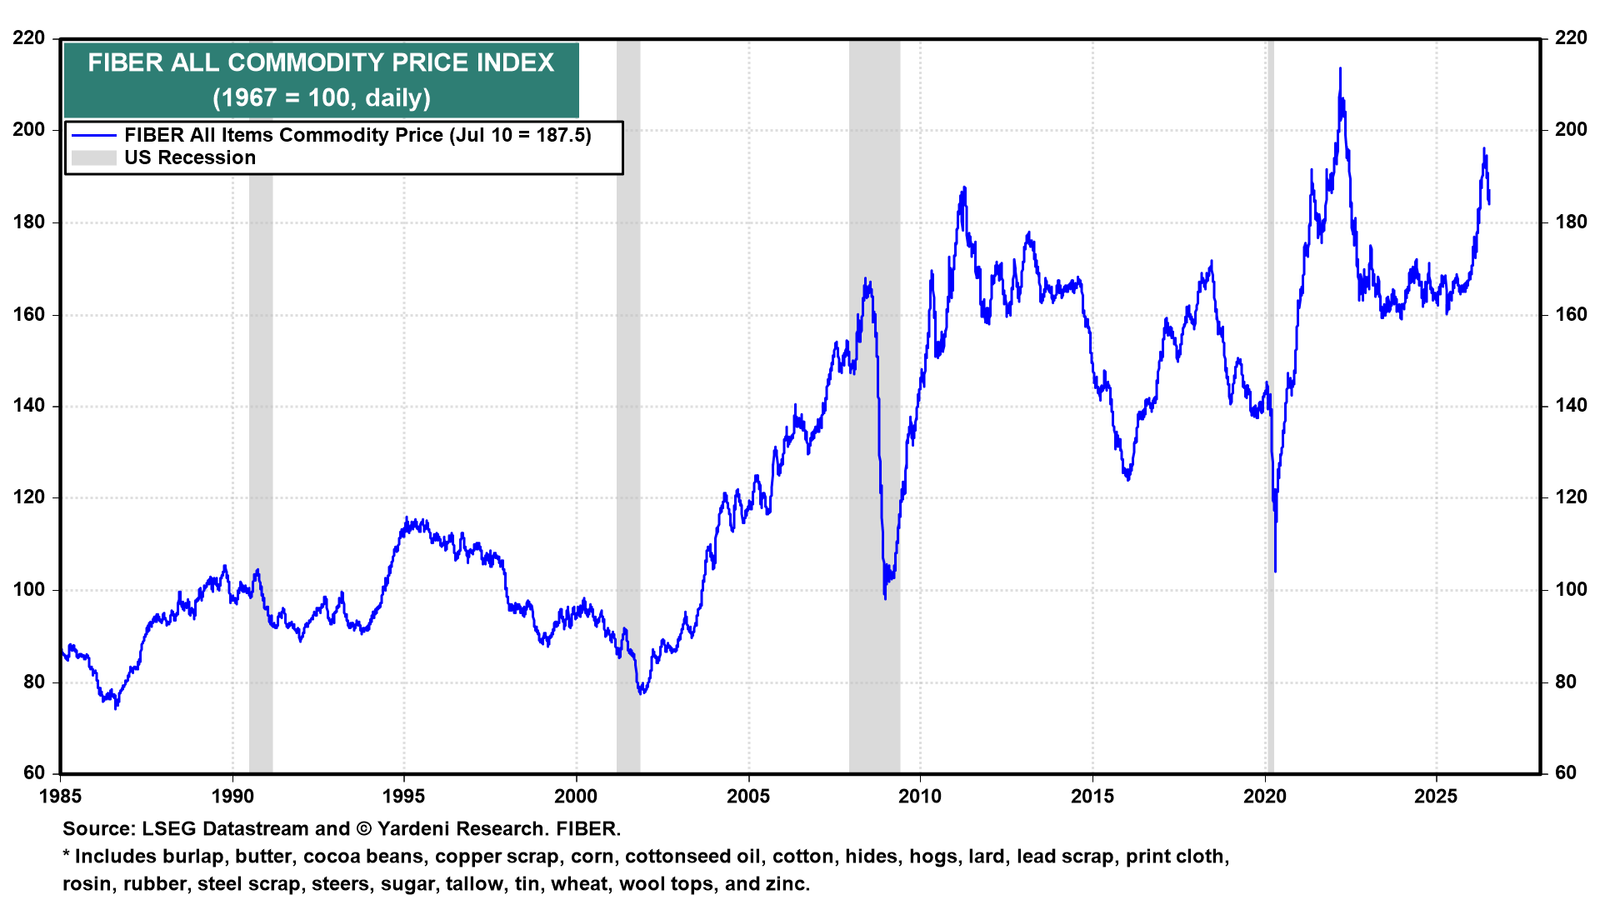
The FIBER industrial materials price index, which includes West Texas Intermediate crude oil, remains elevated, suggesting that the global economy is handling the latest oil crisis remarkably well (chart).
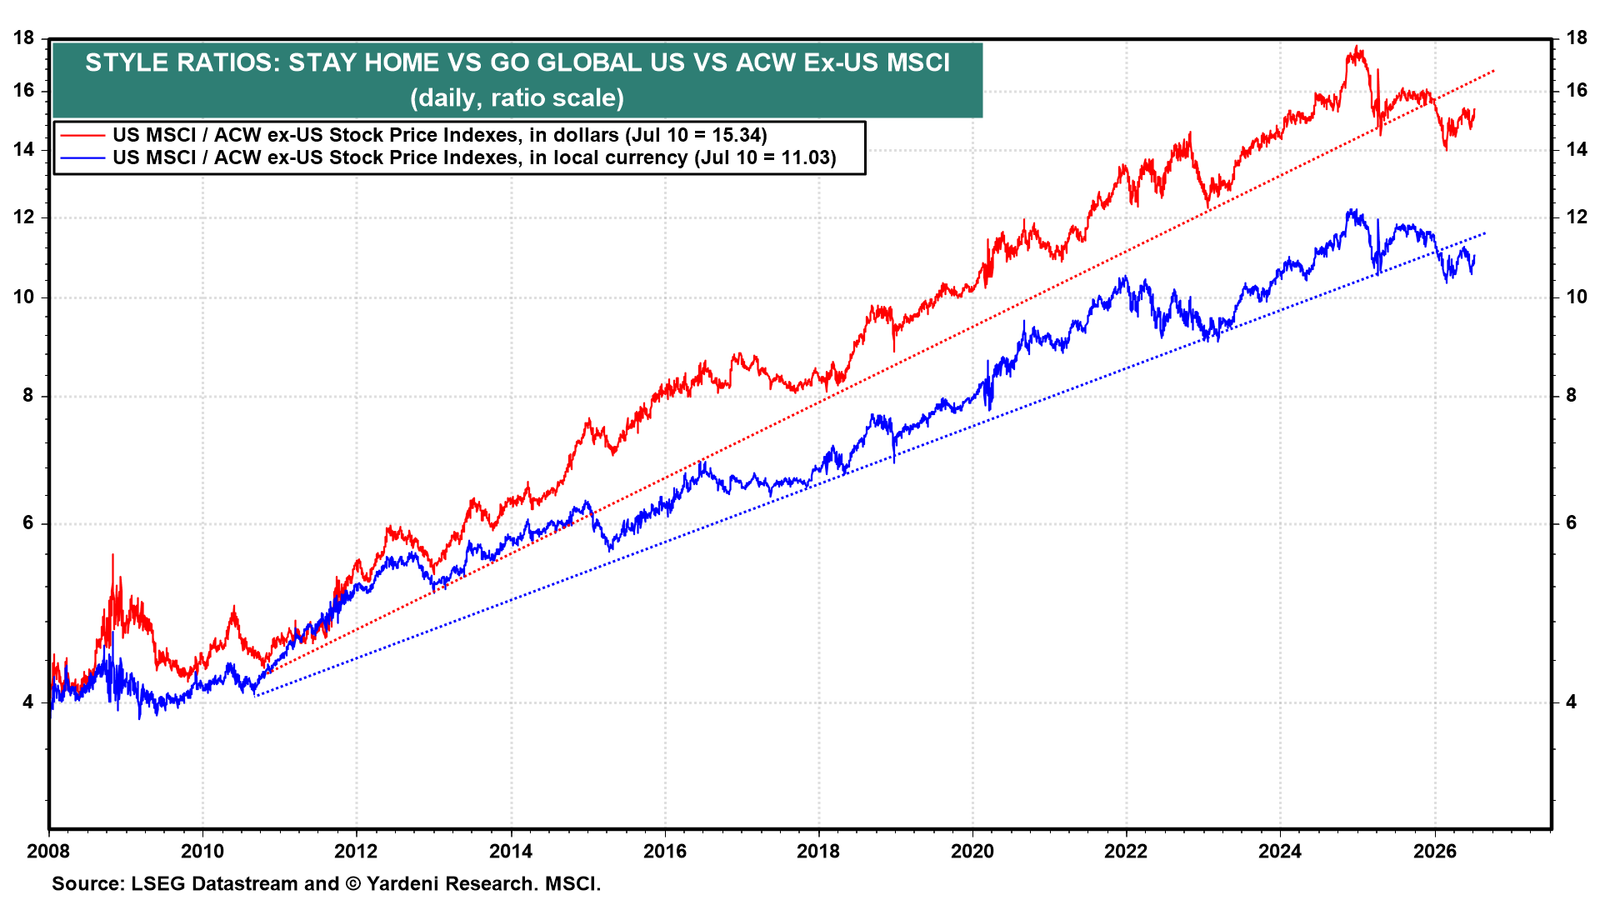
(2) Go Global vs Stay Home. It was a good week for Stay Home. The Stay Home/Go Global ratio rose last week but remains below its multi-year uptrend (chart).
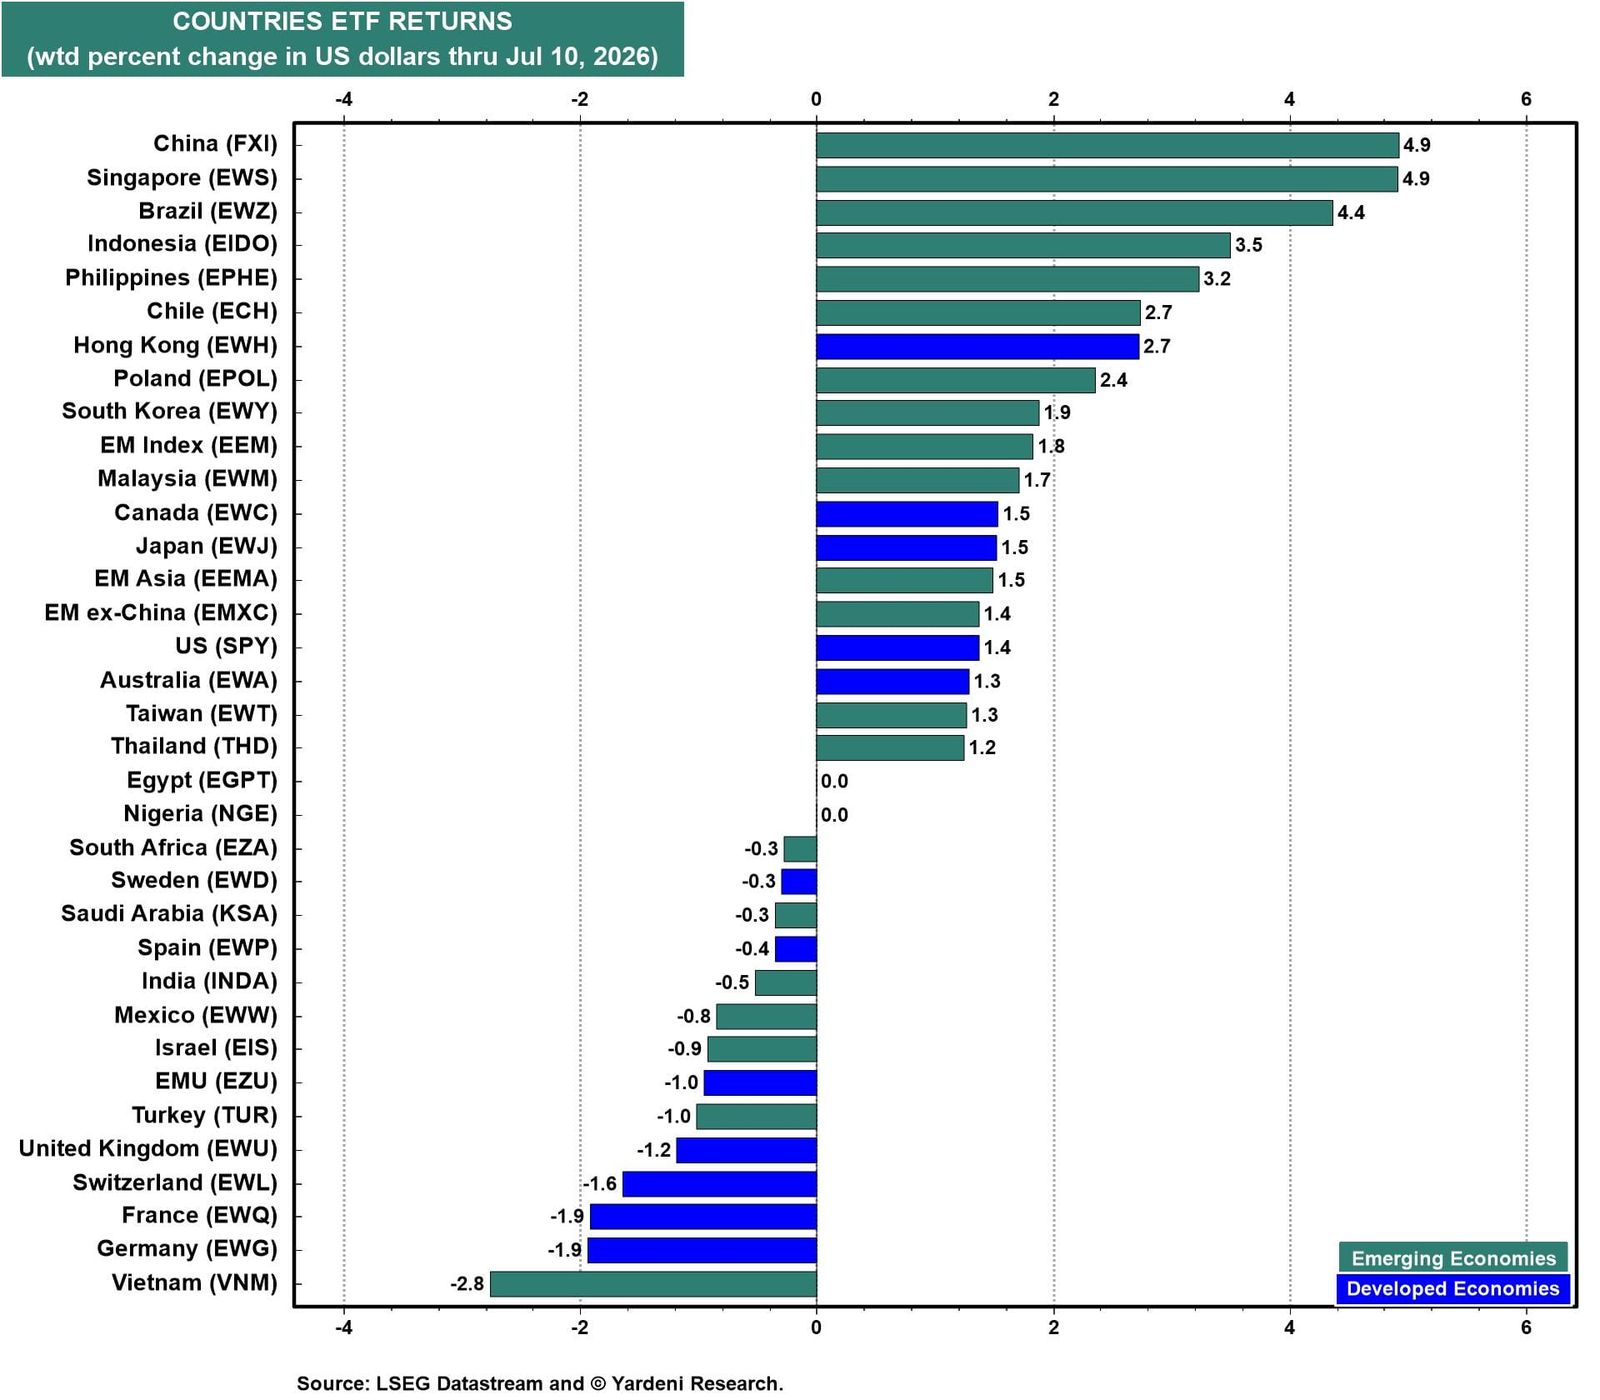
Go Global leadership rotated again last week. The exchange-traded funds of China and Singapore led all the country ETF markets, up 4.9% each, while Germany and France lagged, down 1.9% each (chart). South Korea bounced 1.9% last week after recent profit-taking, a sign that the sharp sell-off in Korea over prior weeks may be stabilizing. Vietnam brought up the rear, down 2.8%.
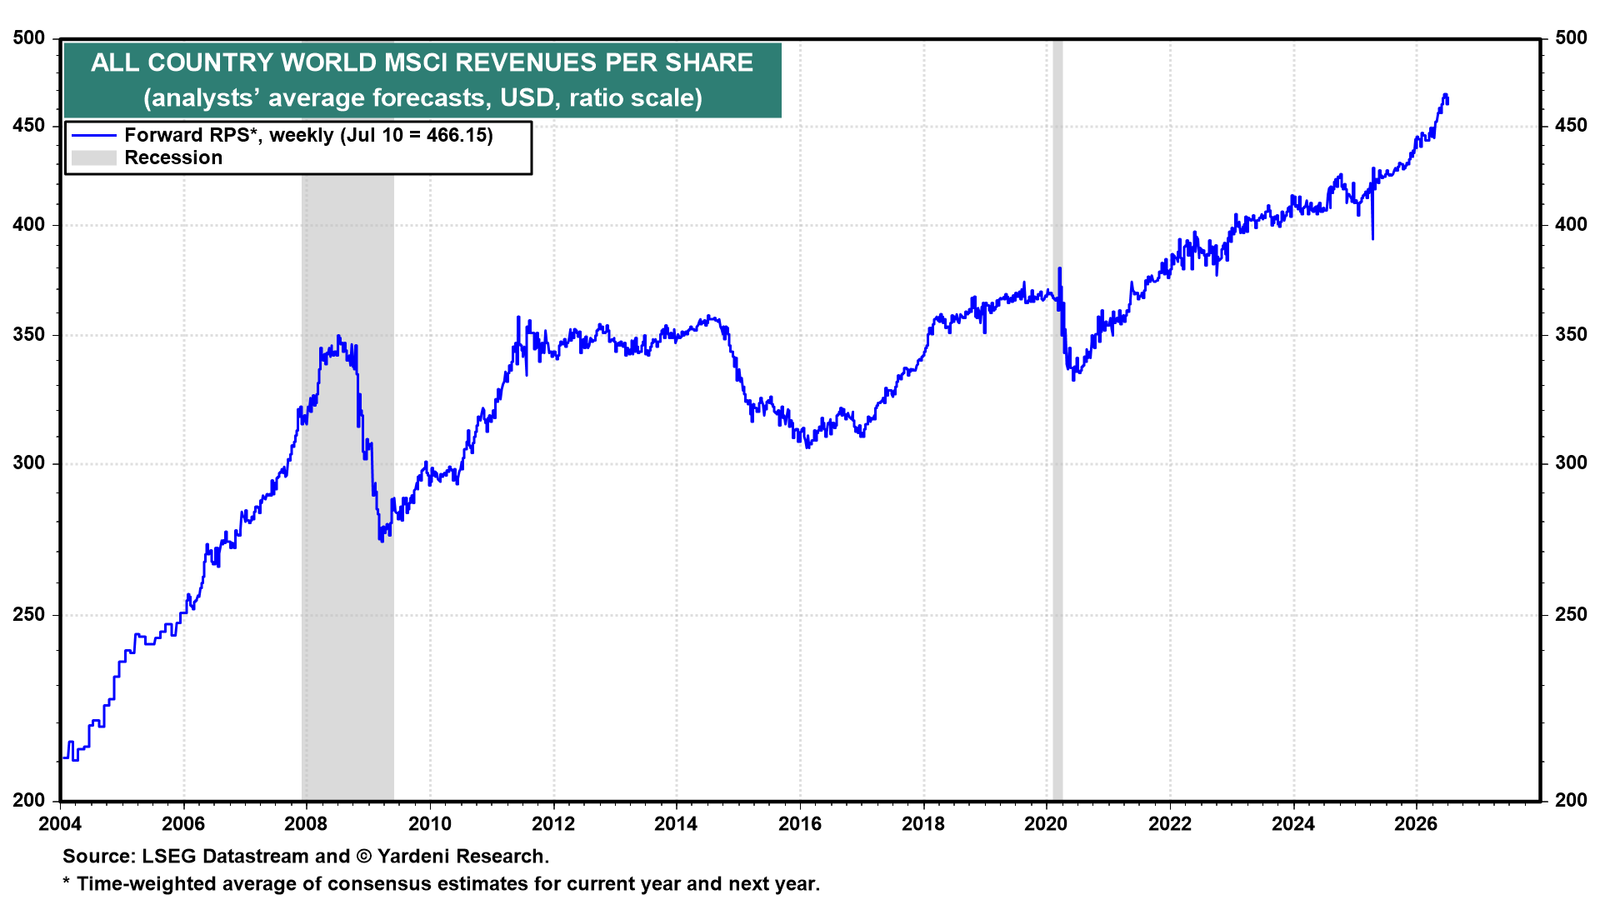
(3) Revenues & Earnings. All Country World (ACW) MSCI’s forward revenues per share rose to a record high last week, confirming that the global economy is performing remarkably well (chart).
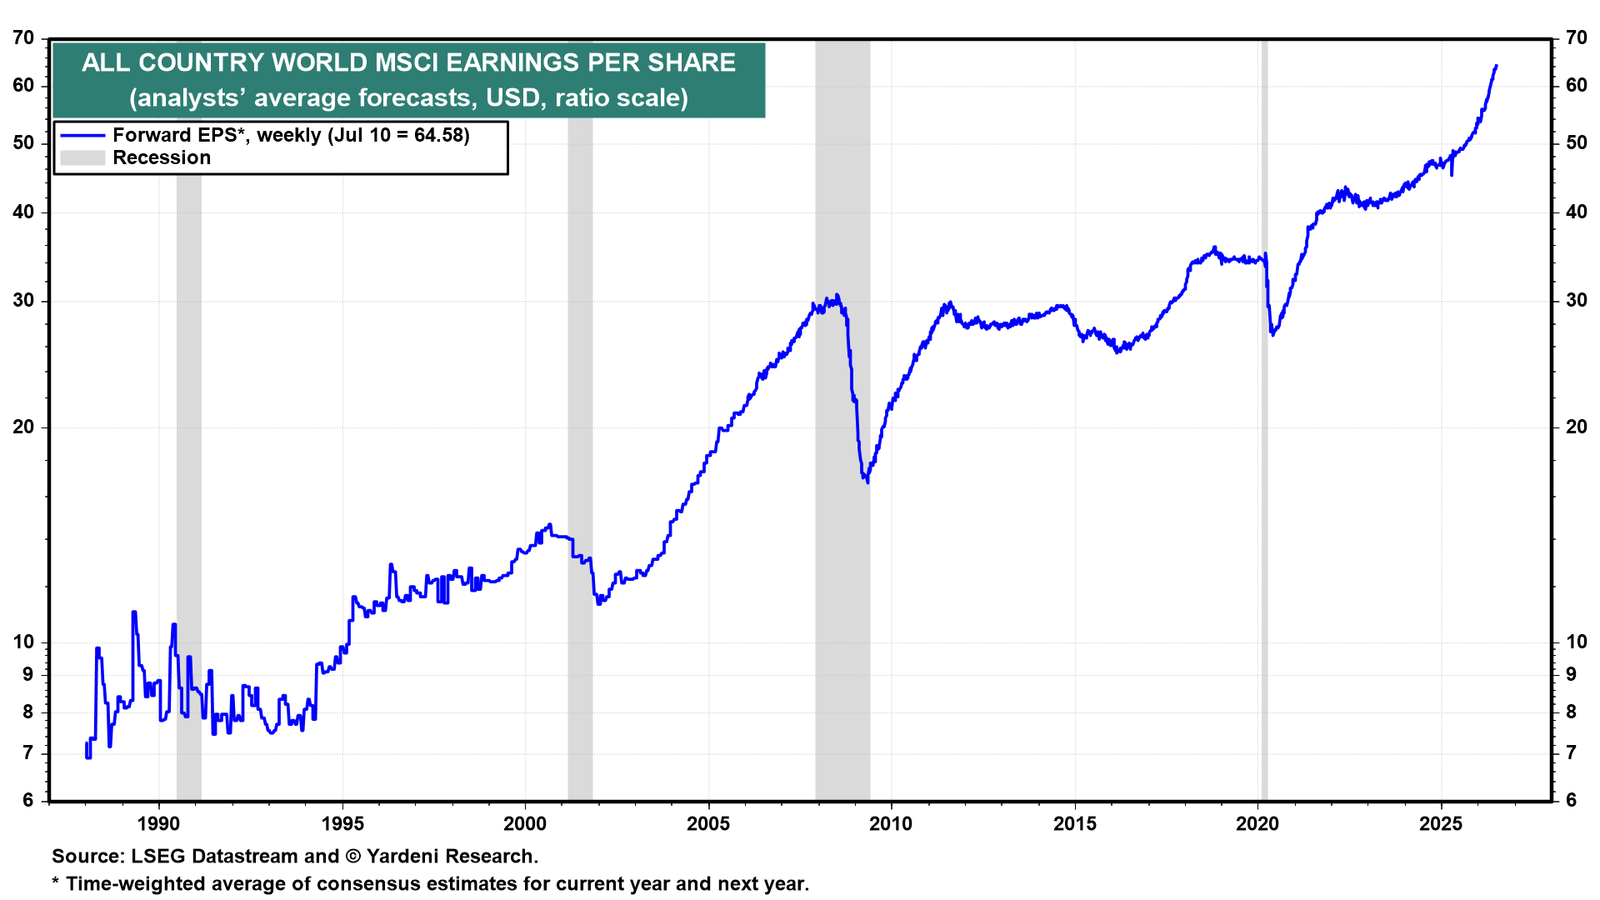
The ACW MSCI's forward earnings per share is rising at even a faster pace (chart).
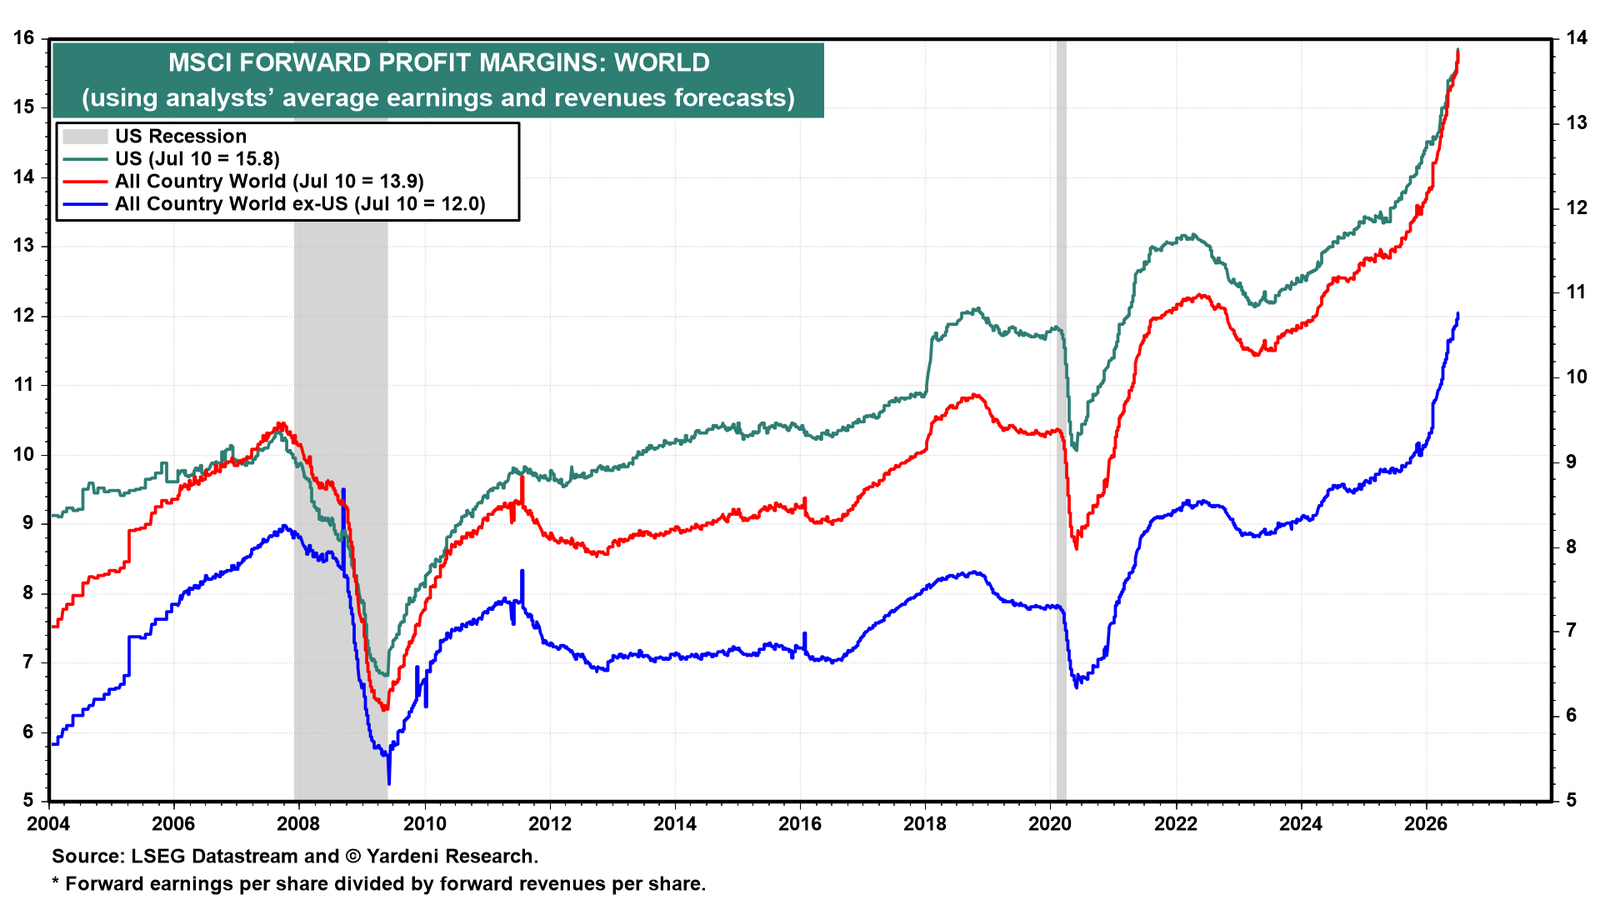
Forward profit margins are rising steeply worldwide, though most of the recent strength is in the US and Asia (chart).
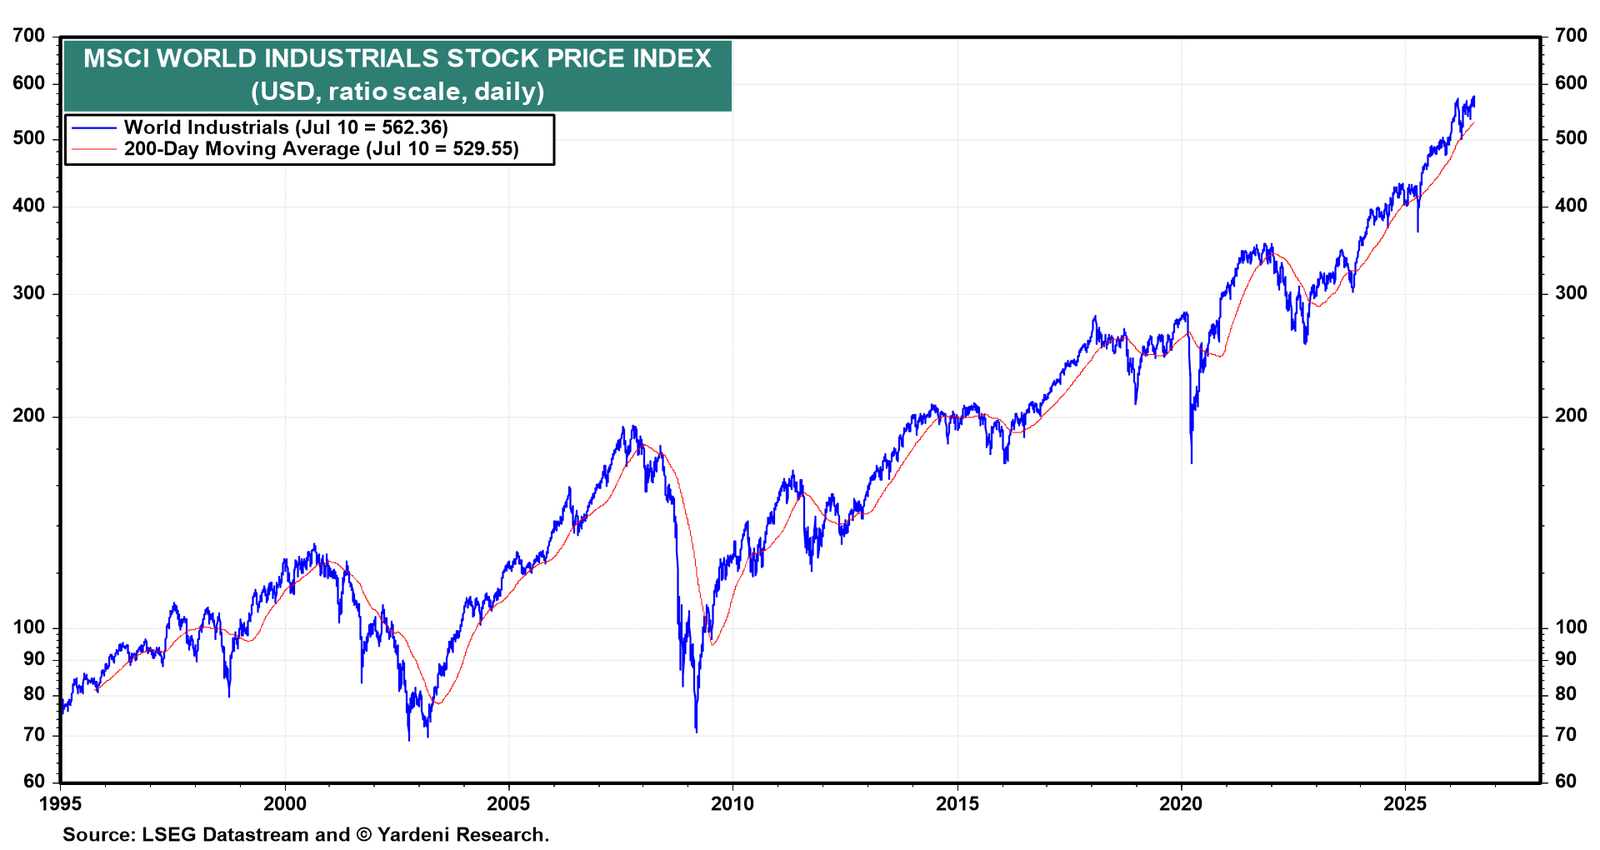
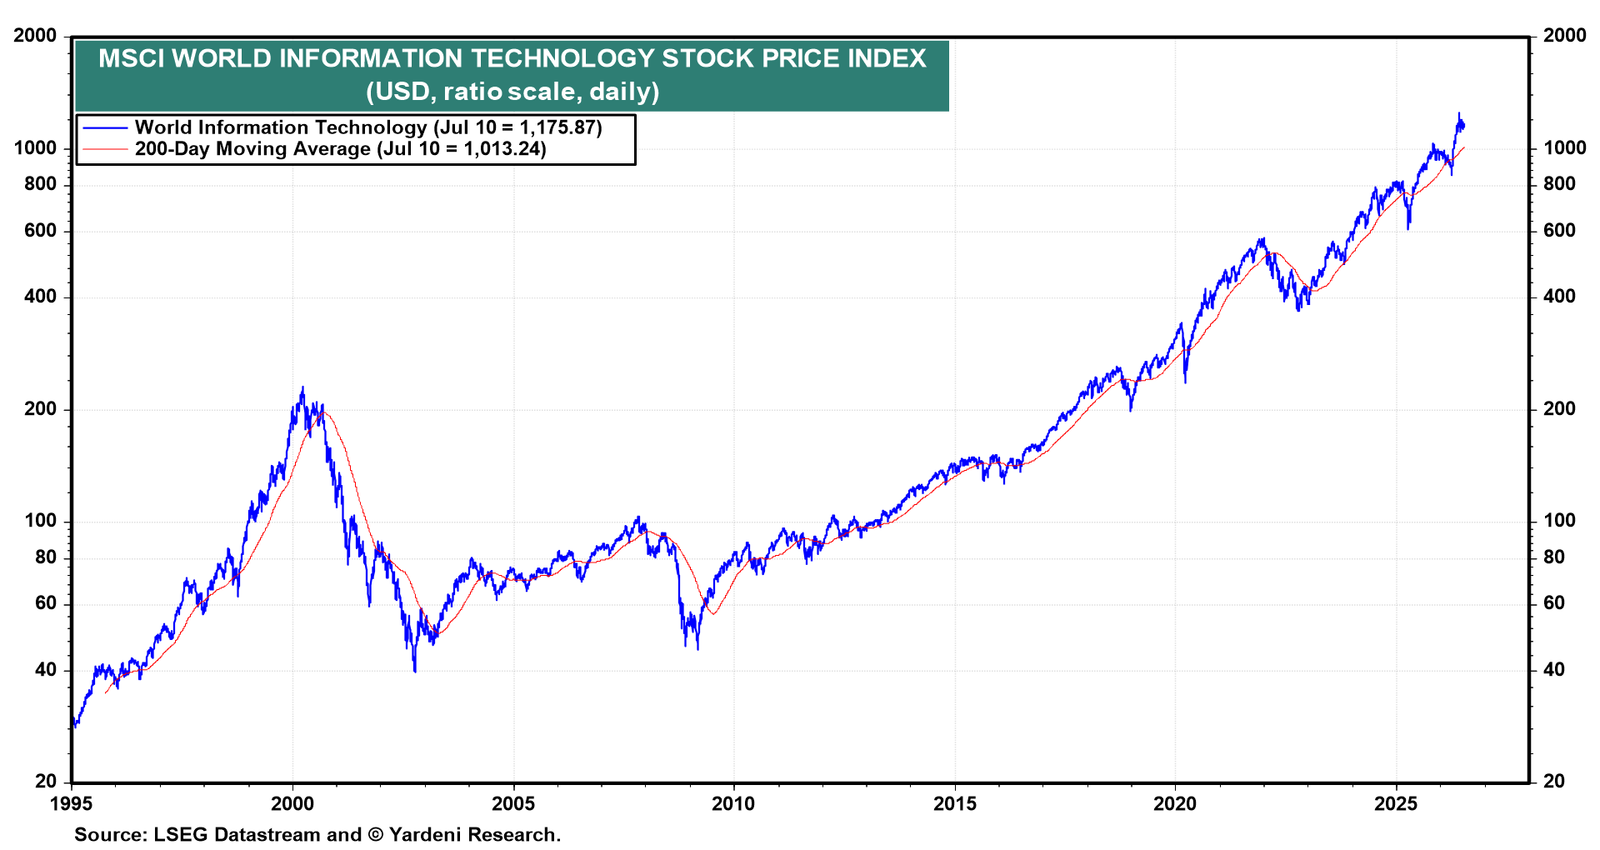
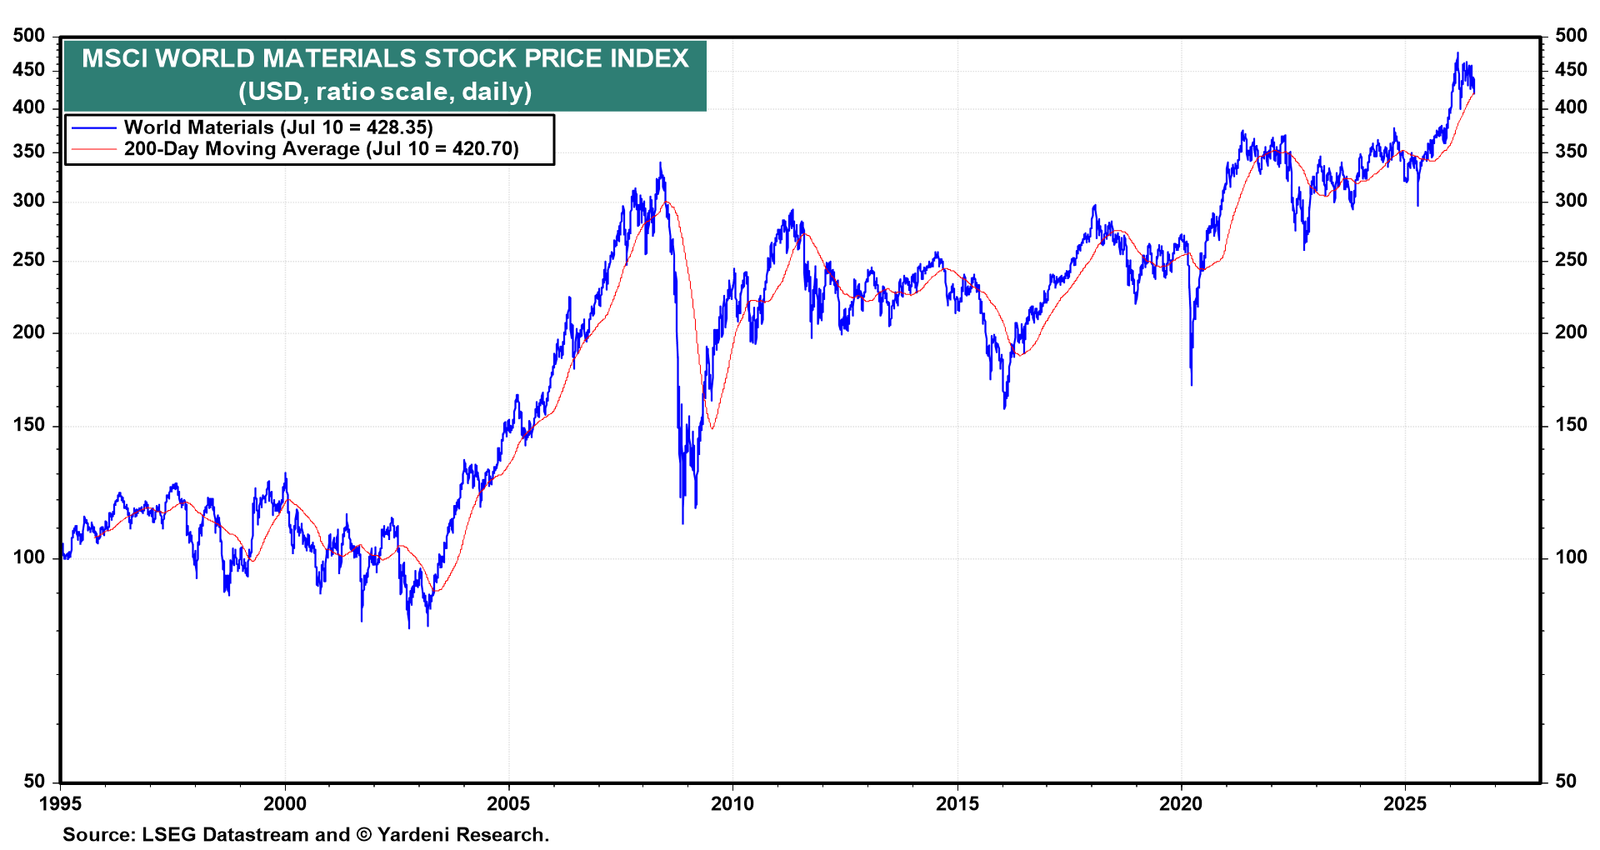
(4) World Sectors. The global bull market continues to charge ahead across sectors.
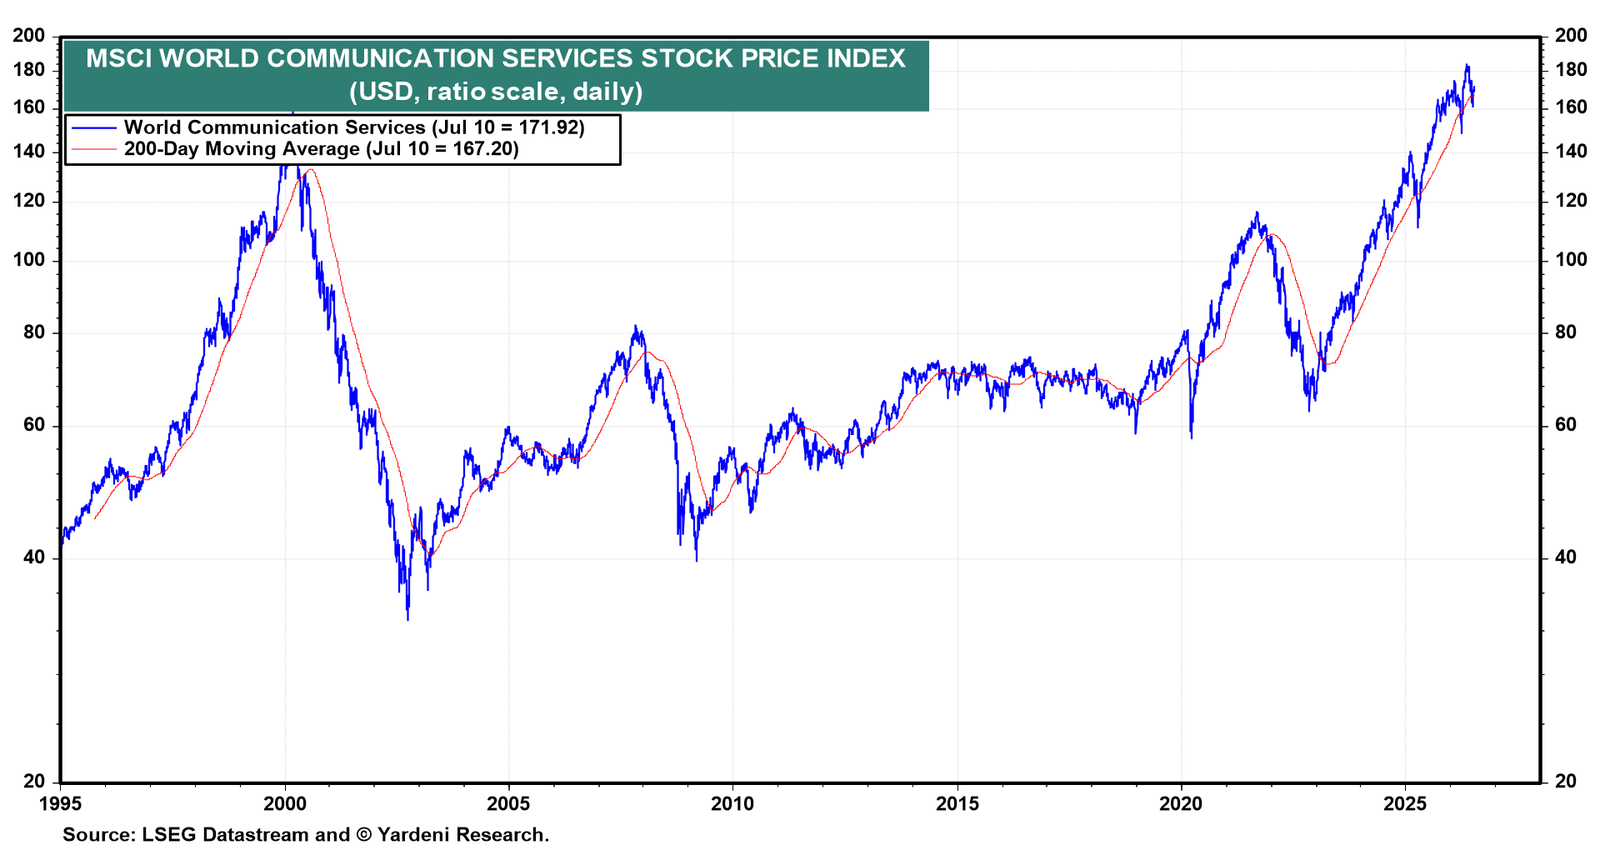
The World MSCI’s Communication Services sector remains on a steep uptrend in record-high territory and just rebounded above its 200-day moving average (dma) (chart).
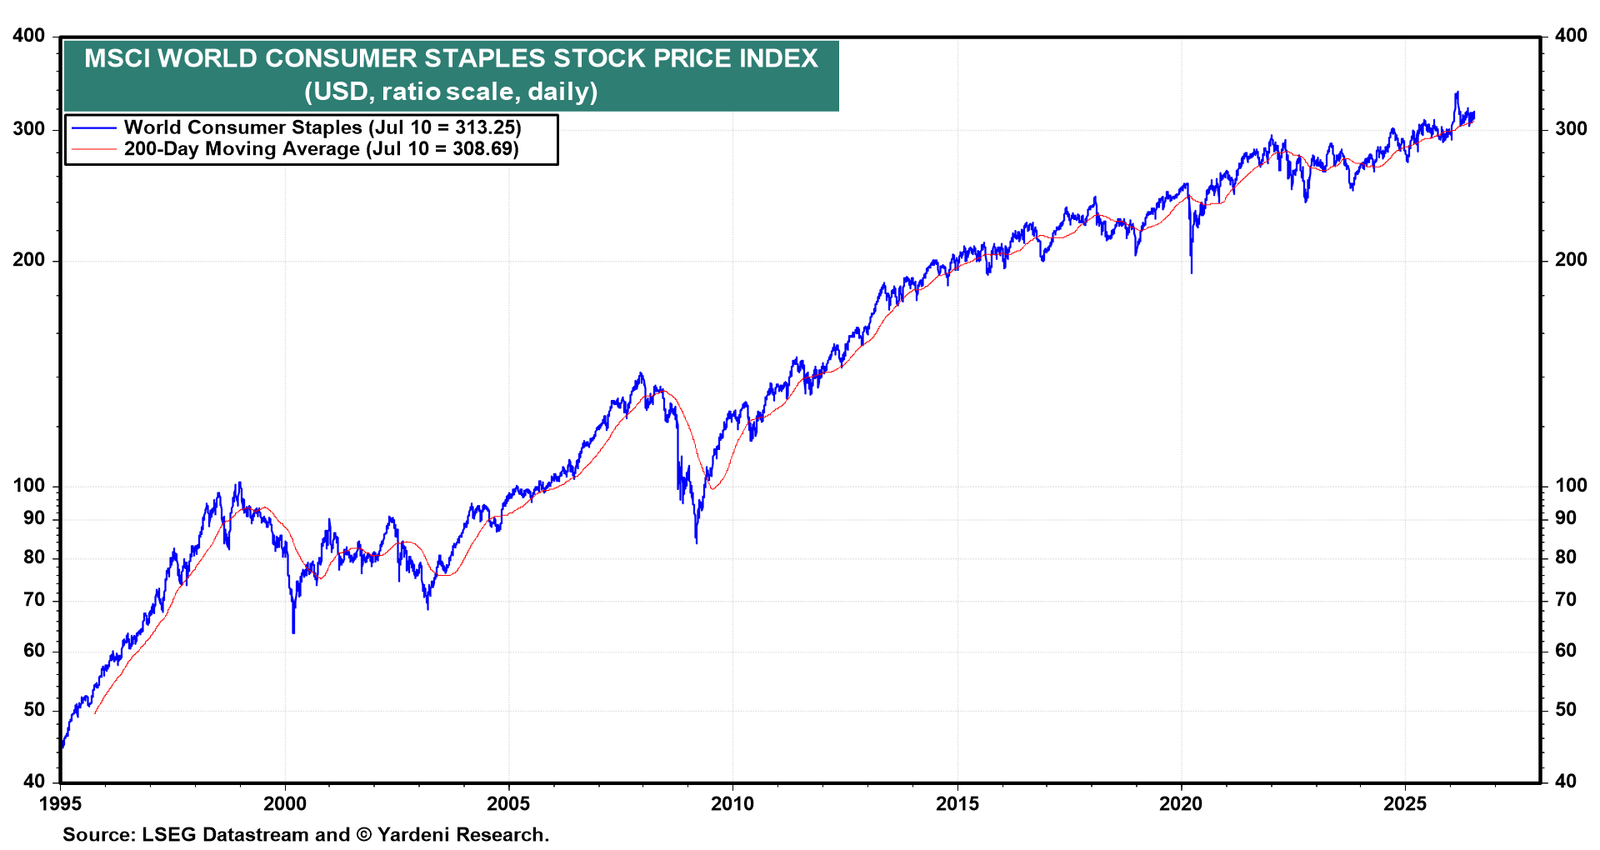
Consumer Staples continues to drift higher to record highs (chart).
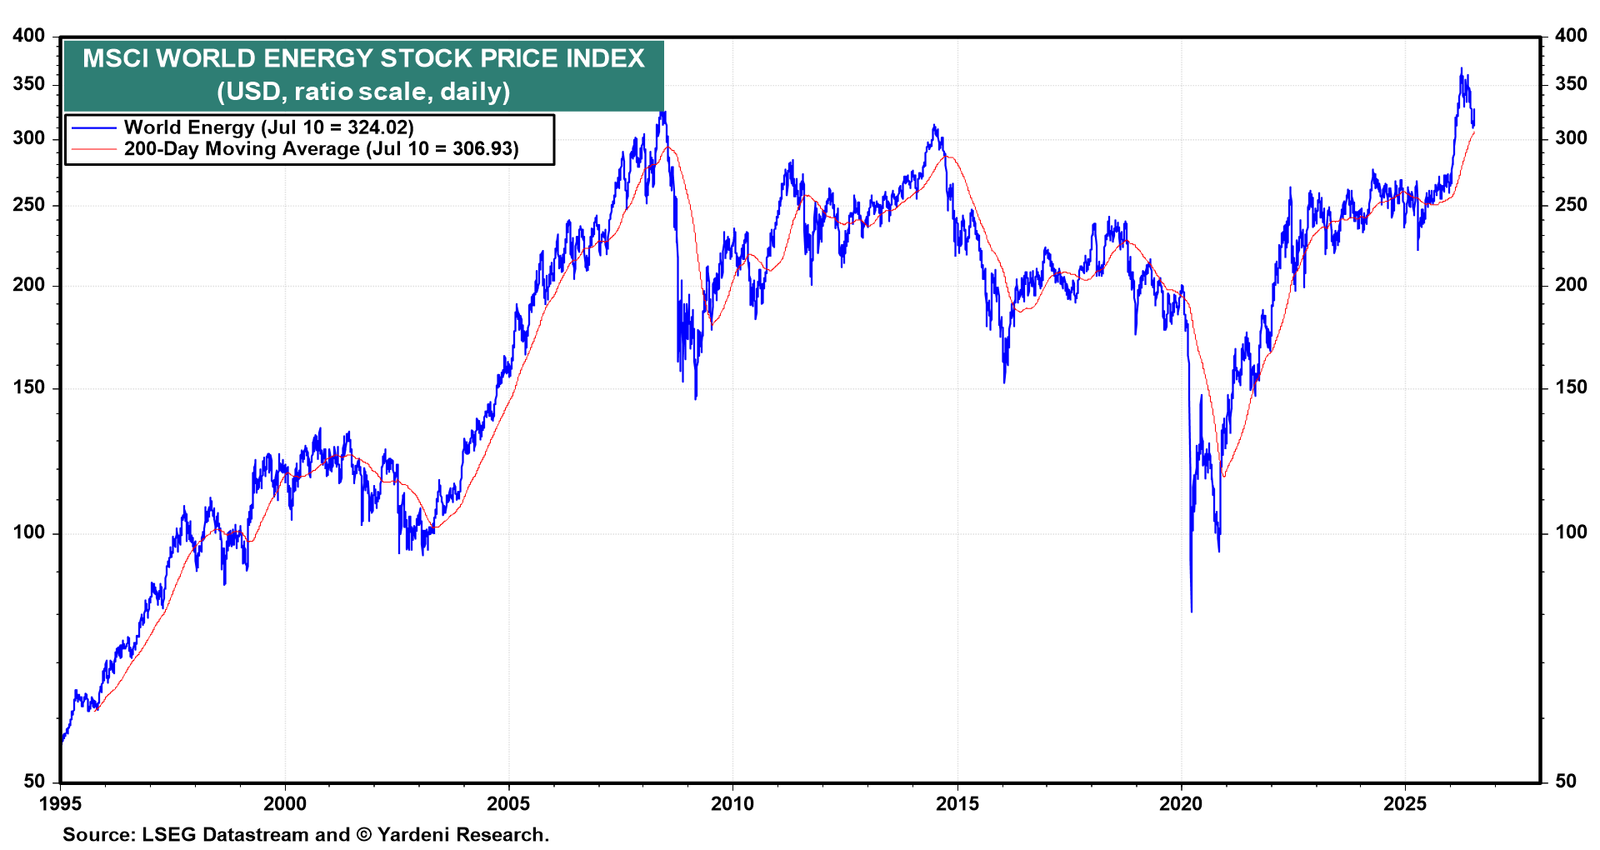
Energy is holding up above its 200-dma, helped by last week's rise in oil prices (chart).
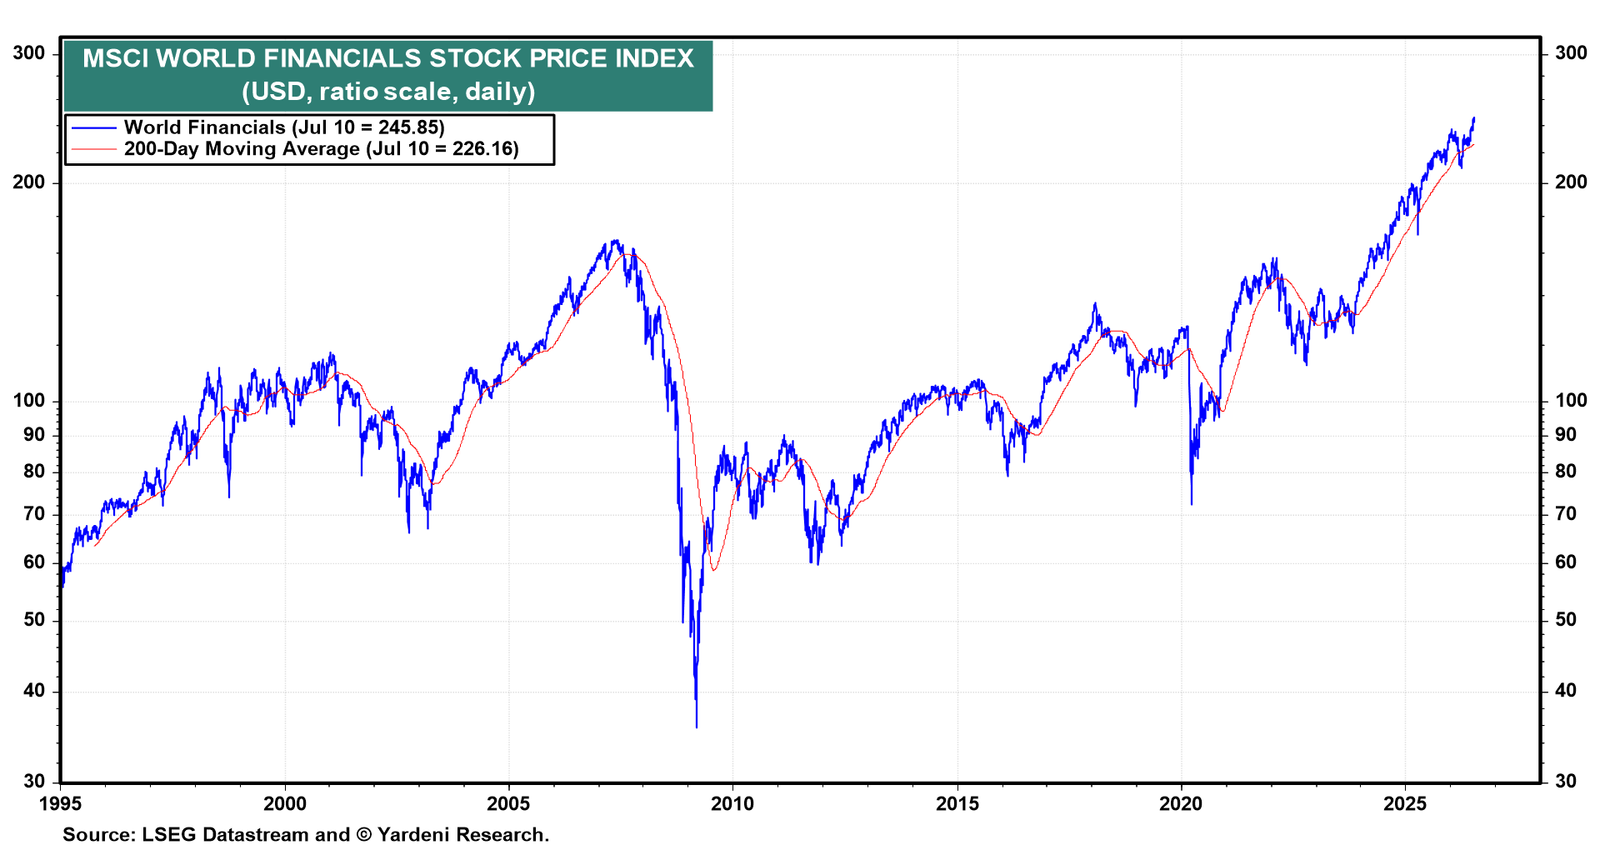
The Financials sector is at a record high (chart).
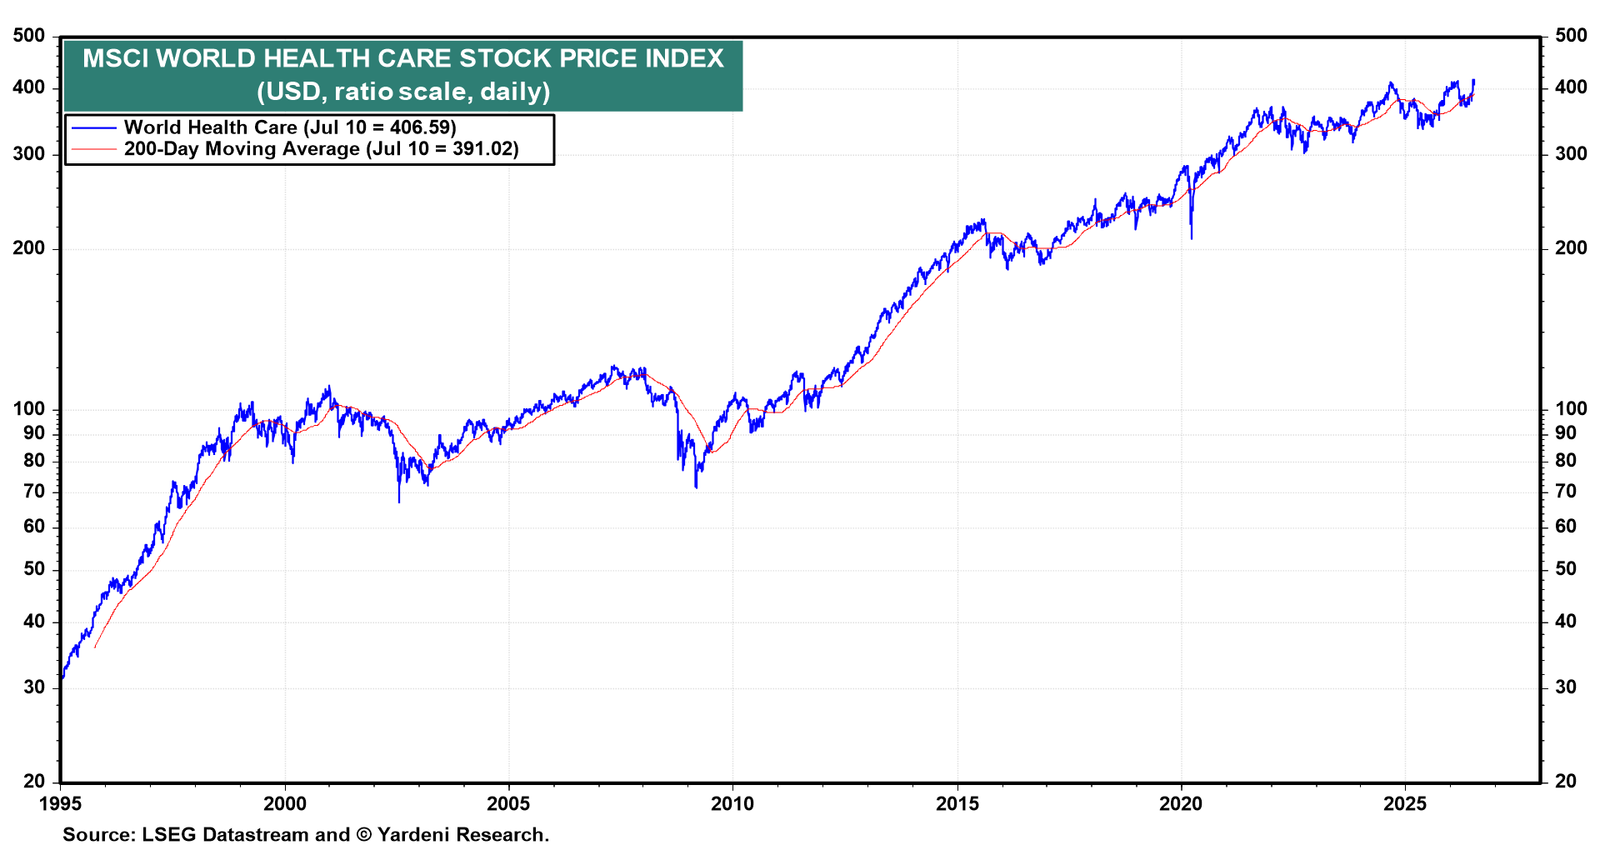
Health Care appears to be on the verge of breaking out, rising back above its 200-dma after a choppy first half of the year (chart).
The Industrials sector is at a record high and remains in a strong uptrend (chart).
Information Technology continues to lead the advance and is now 16% above its 200-dma (chart). As a result, it may be the most vulnerable to a pullback of all 11 sectors.
Materials has been on a choppy uptrend and is at its 200-dma (chart).
Utilities is also on a steep uptrend and just bounced off its 200-dma (chart).
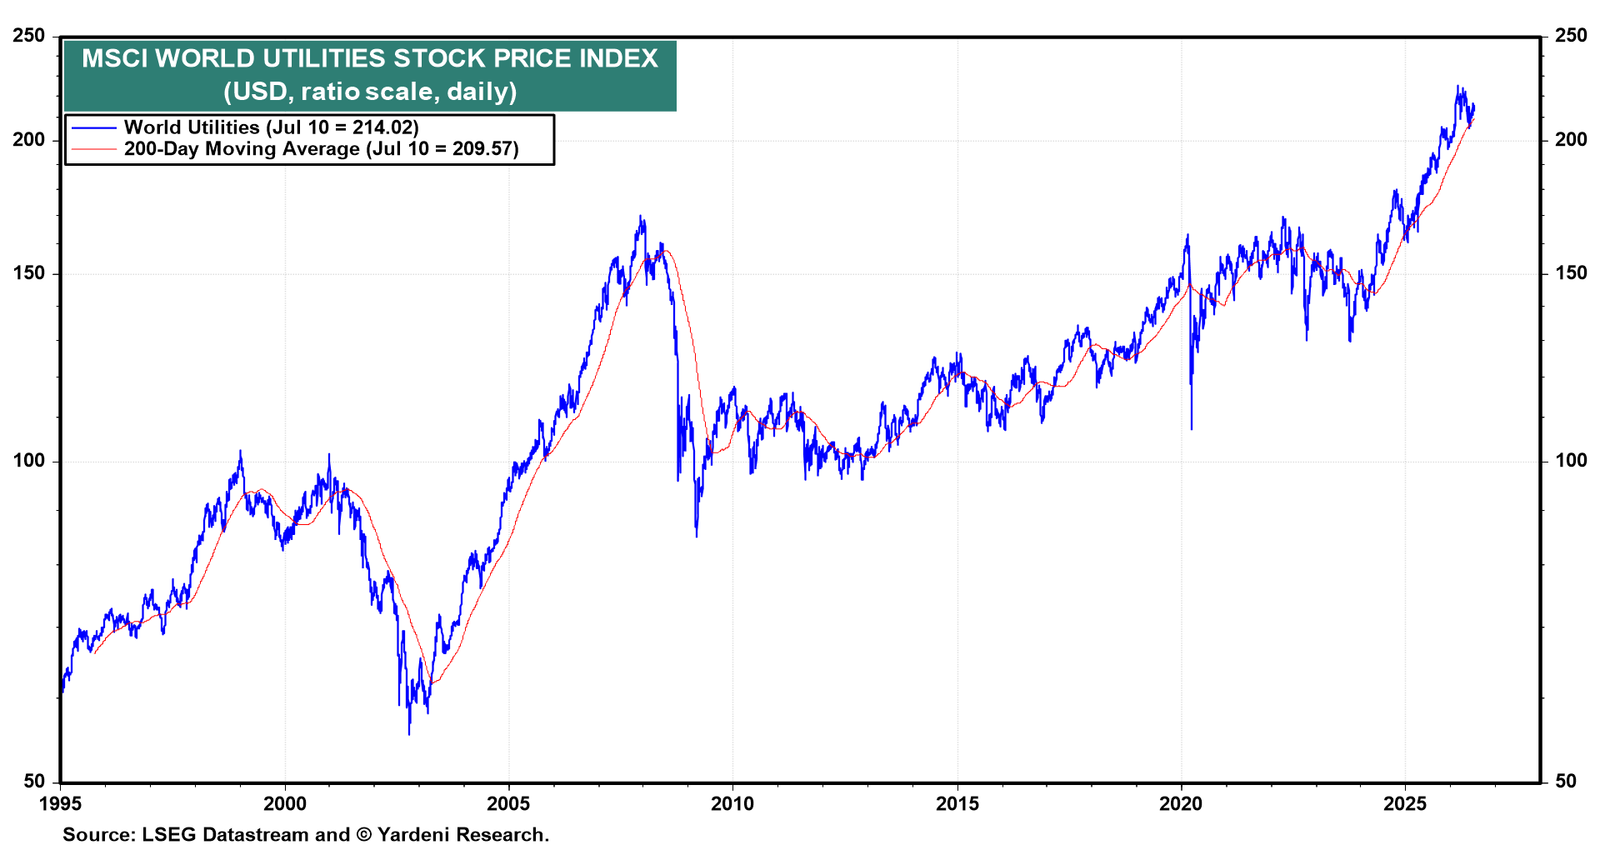
Overall, the global bull market is remarkably broad across the World MSCI sectors.