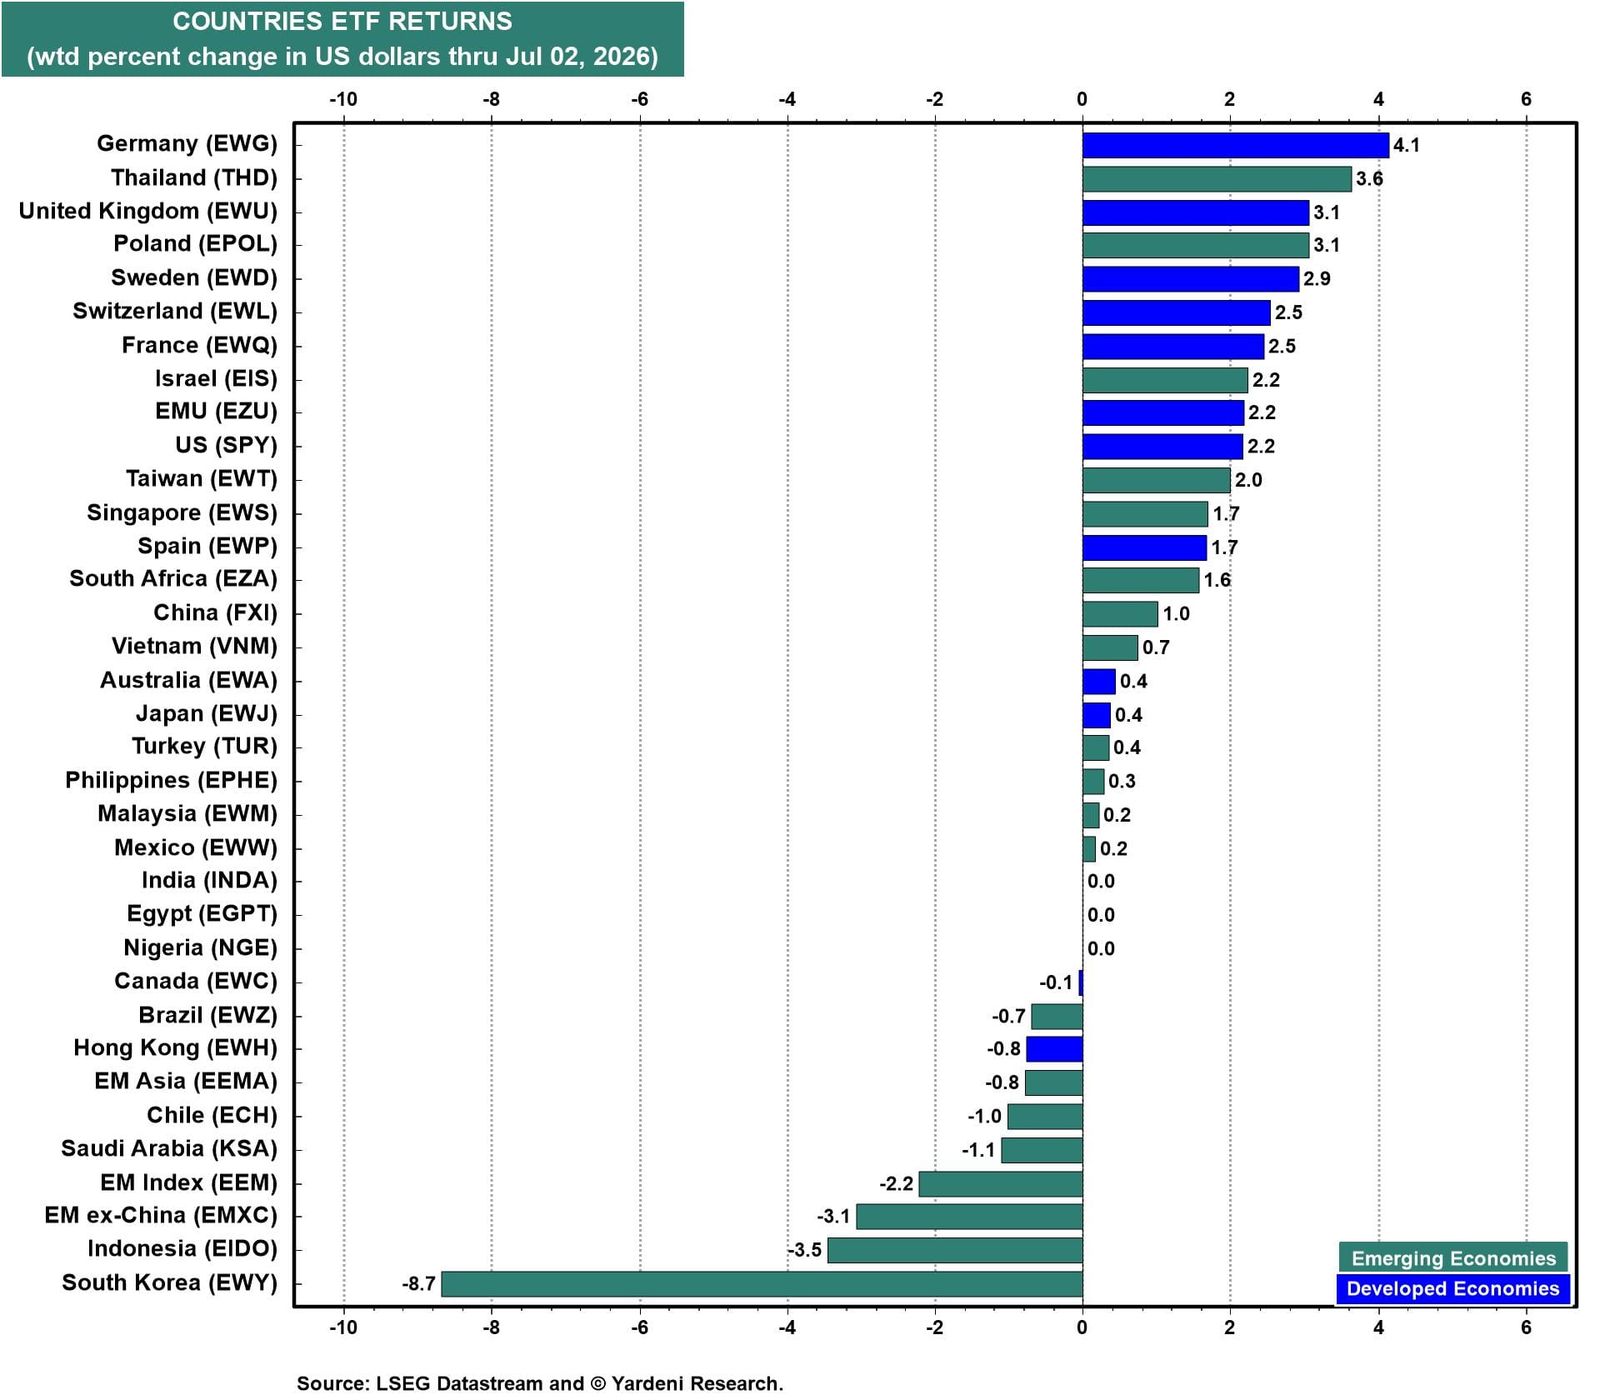
The Go Global trade we’ve recommended since late last year continues to perform well, but leadership among global stock markets rotated this week as Europe took the baton from Asia.
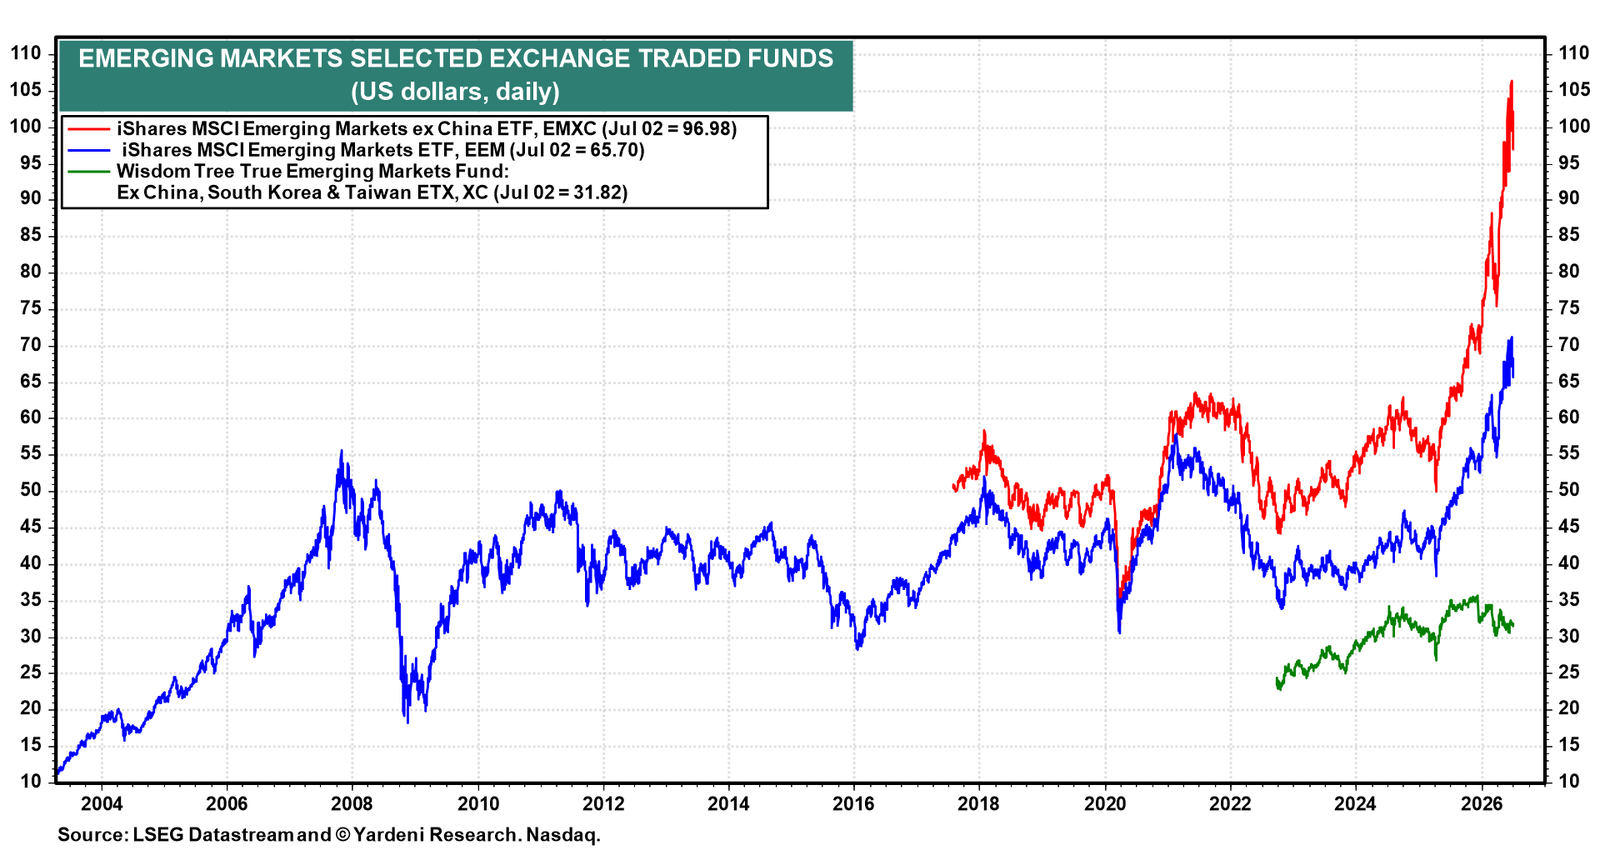
Germany, the UK, France, and Sweden led the European country ETF derby. South Korea gave back 8.7% in a sharp bout of profit-taking in semiconductor stocks. This is simply an overdue correction after Korea’s parabolic run, nothing worse. The AI capex boom that underpins the Korea and Taiwan bull markets remains intact.
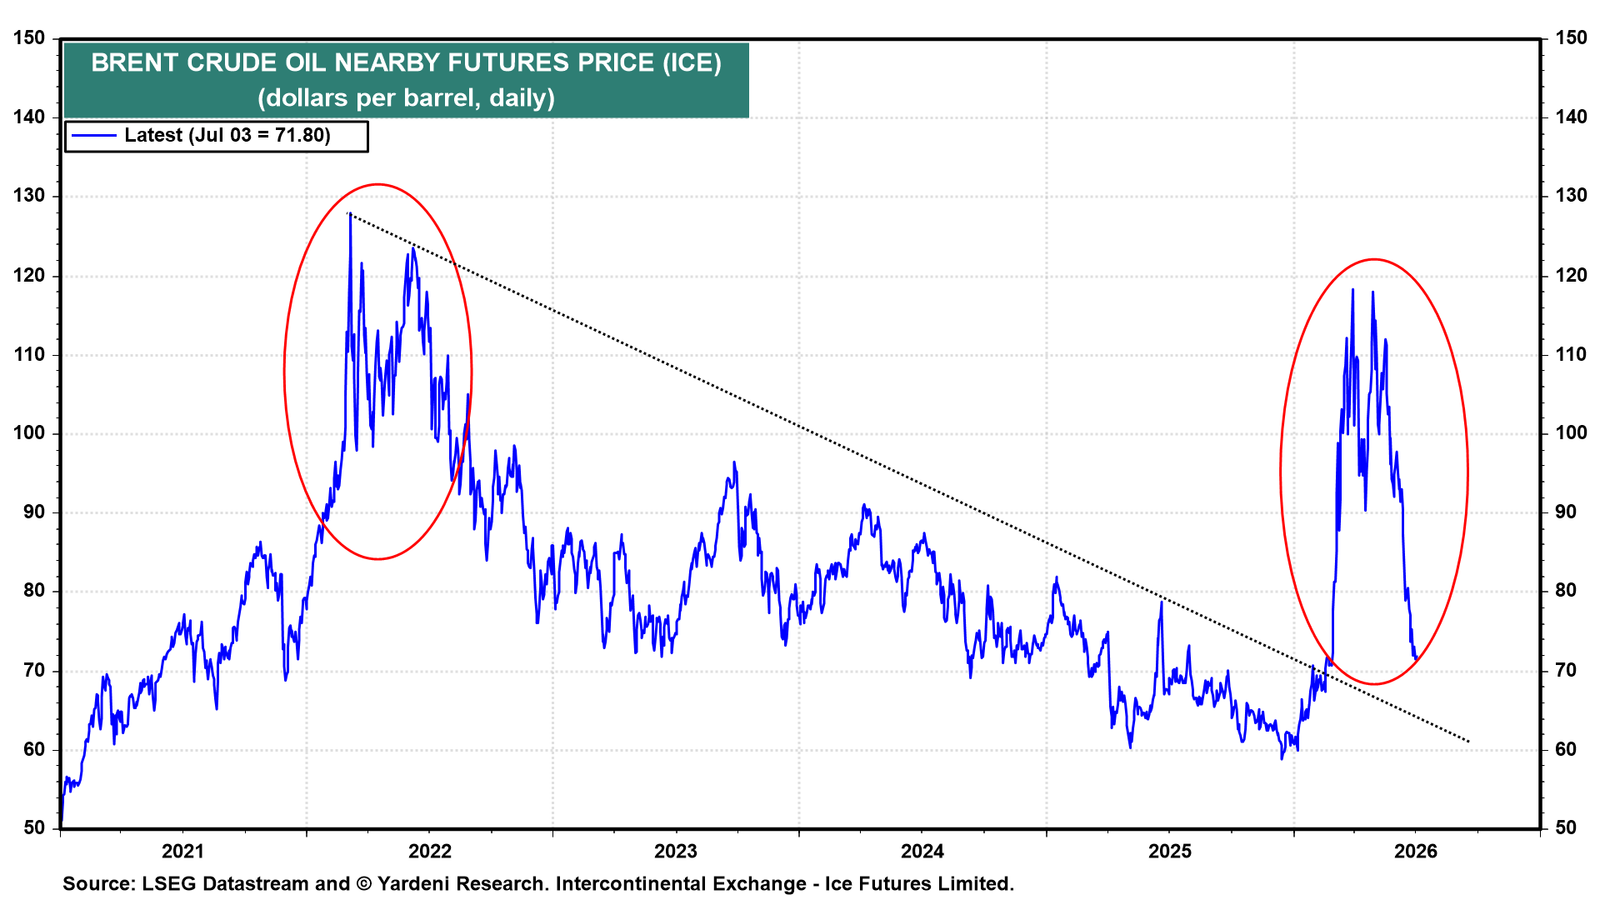
(1) Commodities. The peace dividend has materialized faster than widely expected, as the price of crude oil has plunged to its lowest level since the start of Gulf War III (chart). Before the war, there was a bear market in crude oil. It may be resuming because Chinese demand for oil has declined due to the widespread adoption of EVs in the country. China's economy is also weak.
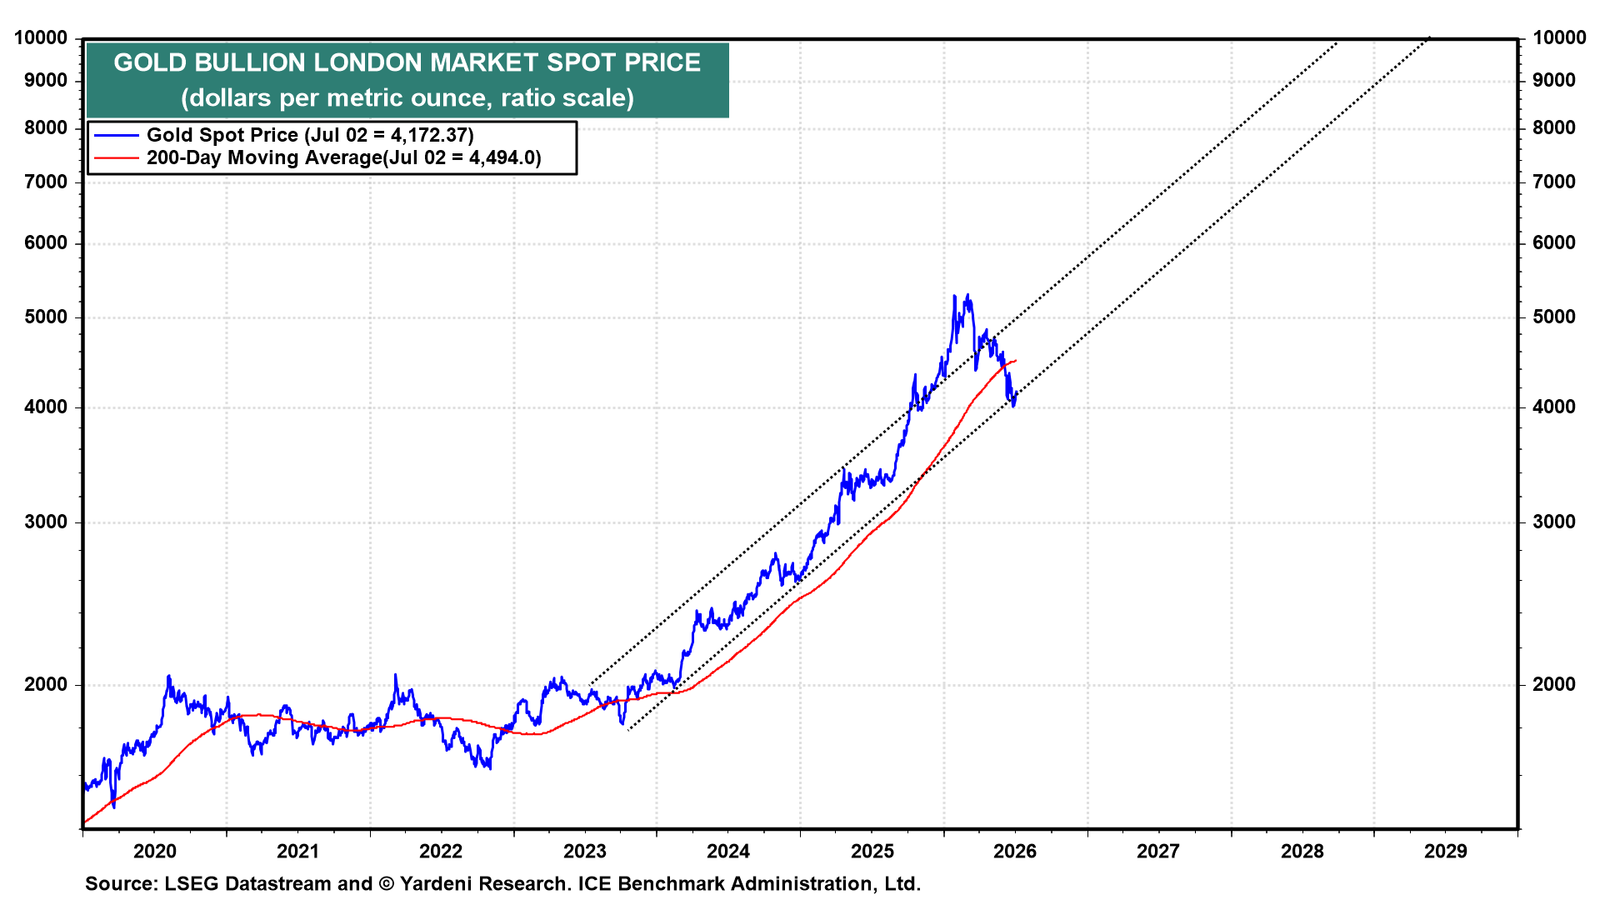
The price of gold is struggling to hold support around $4,000 per ounce (chart). The Fed's recent pivot to a more hawkish monetary policy stance strengthened the dollar and caused the price to fall below its 200-day moving average. We expect the $4,000 support level to hold and are still targeting $5,000 by the end of this year, but with less confidence.
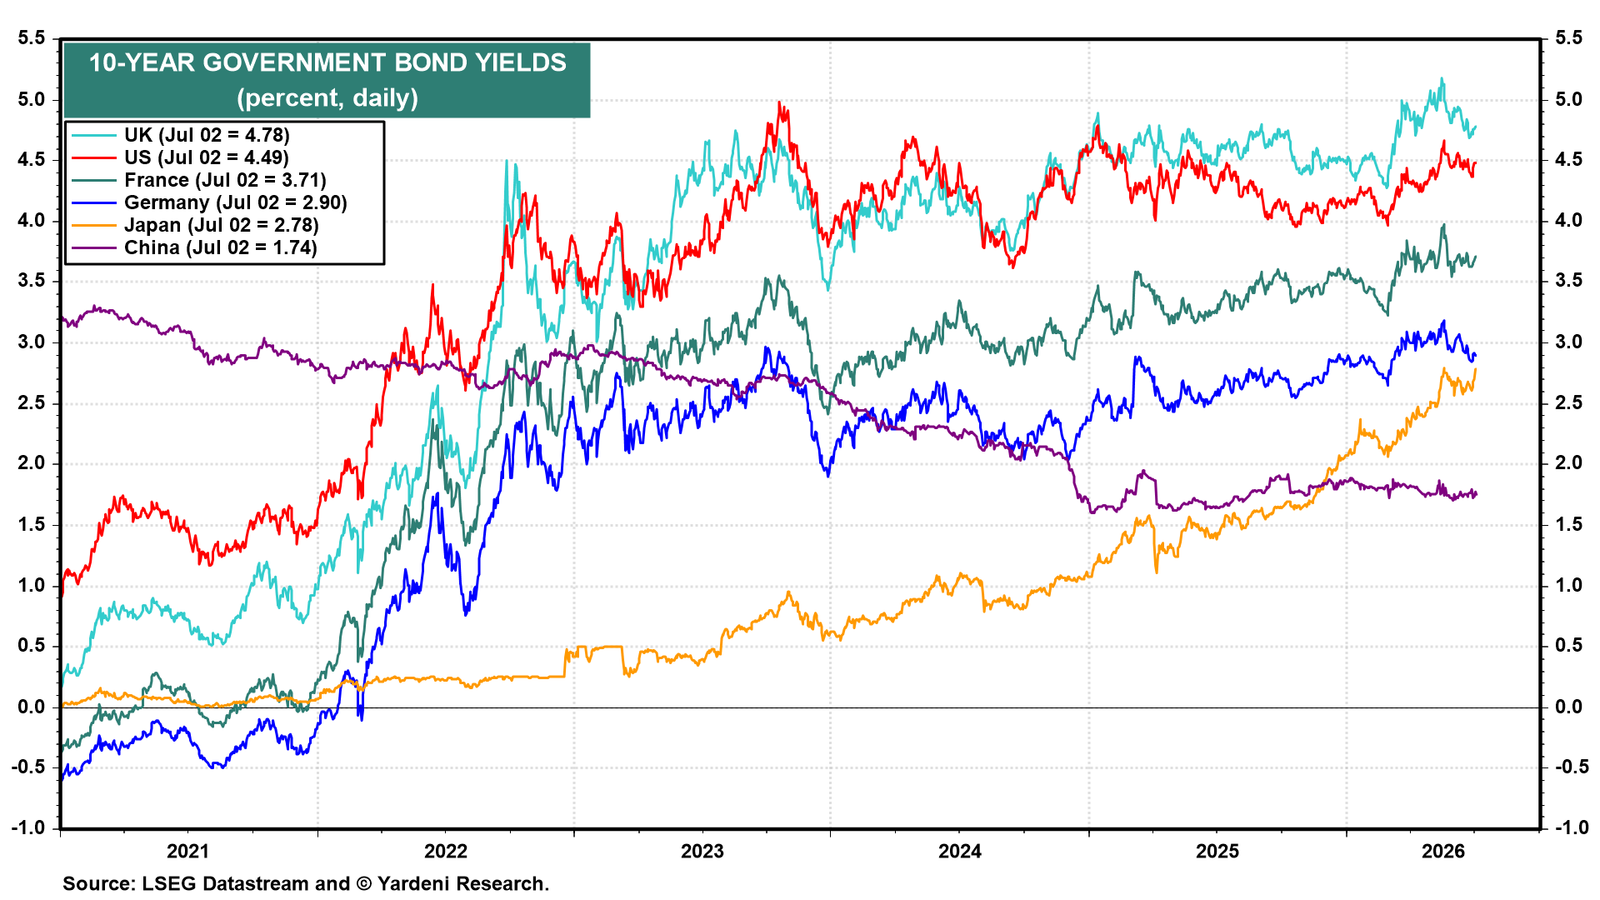
(2) Bond Yields. Sovereign 10-year bond yields drifted marginally higher on the week but remain well off their May peaks (chart). The JGB yield continues its steady march higher as the BOJ’s hiking cycle grinds on.
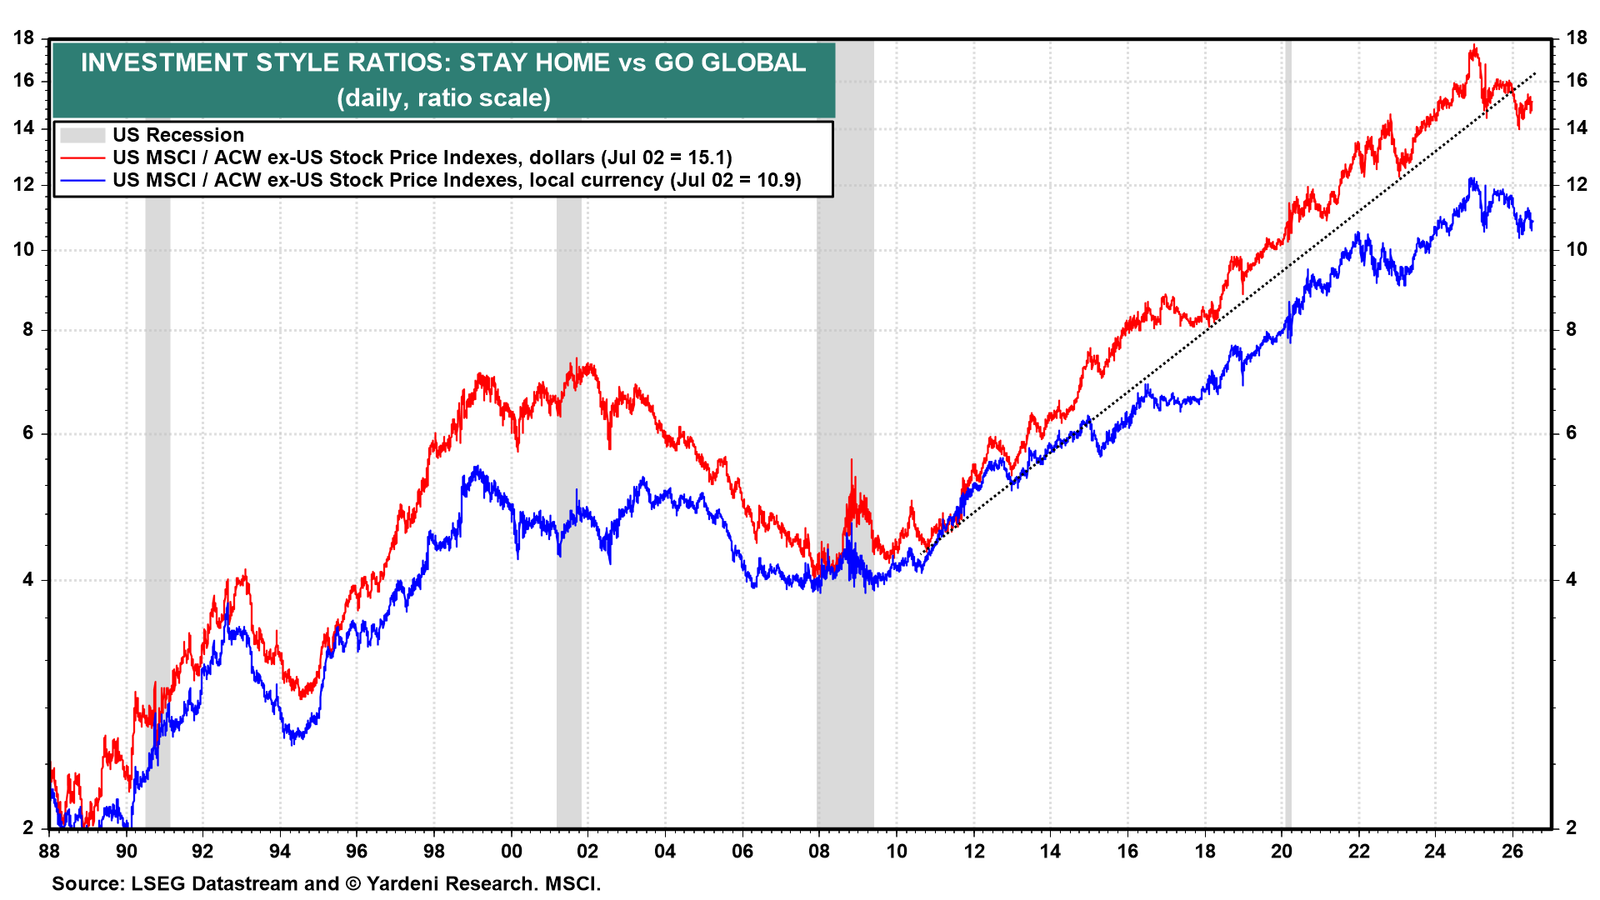
(3) Stocks. The Stay Home versus Go Global ratio broke below its long-term uptrend late last year (chart). Last week, the US stock market underperformed the major European stock markets, while outperforming several EMs (first chart).
The parabolic ascents of EEM and EMXC this year were led by South Korea and Taiwan (chart).
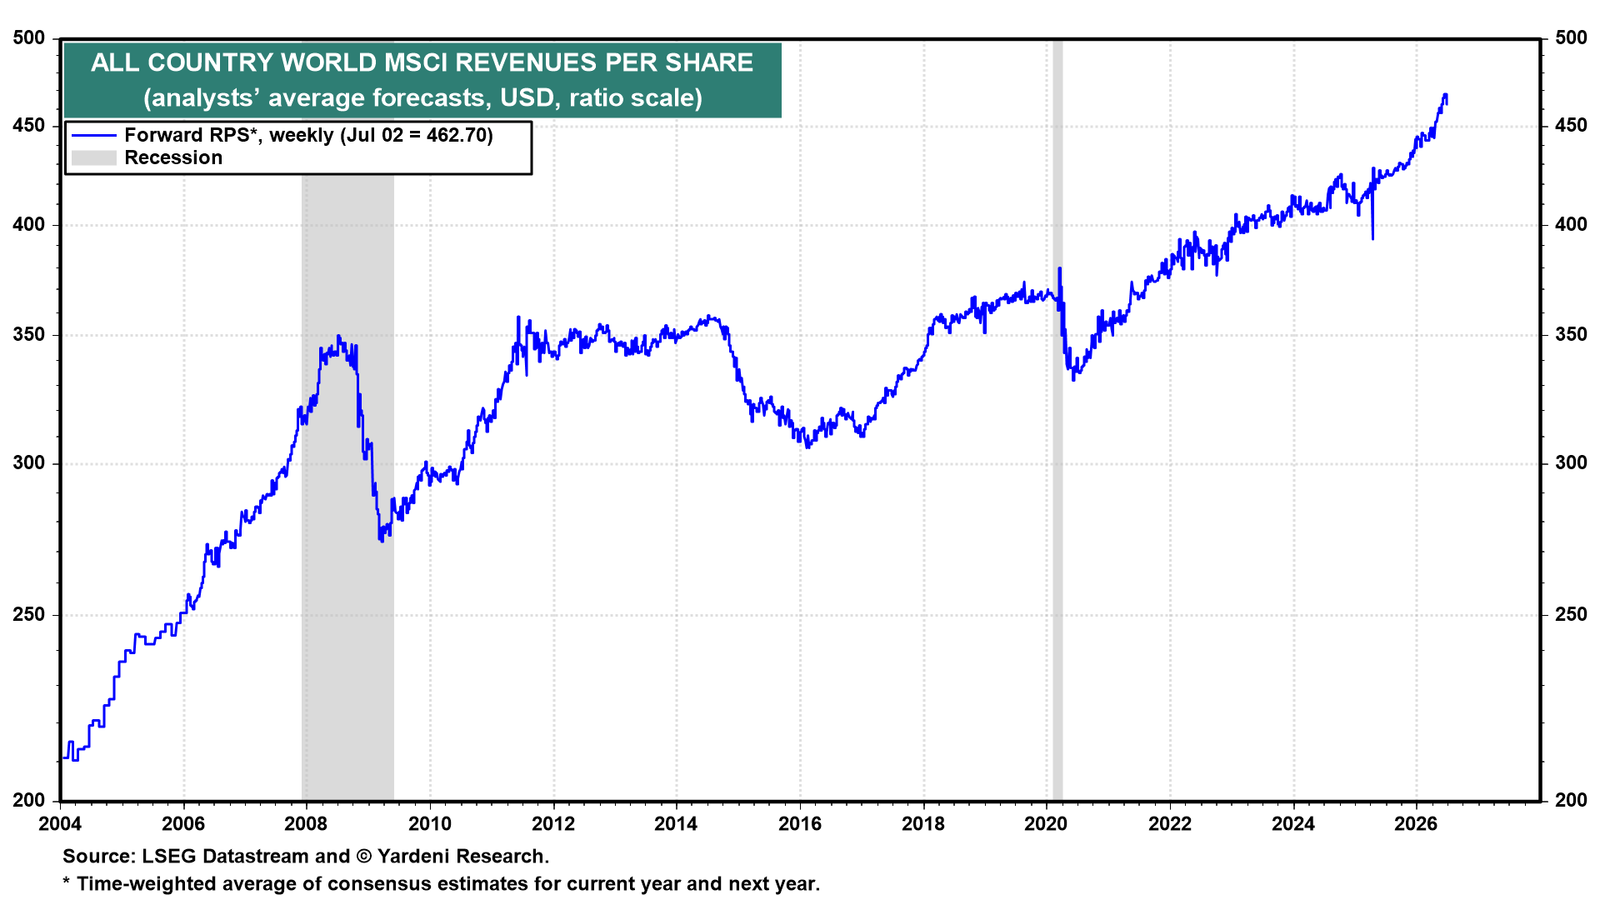
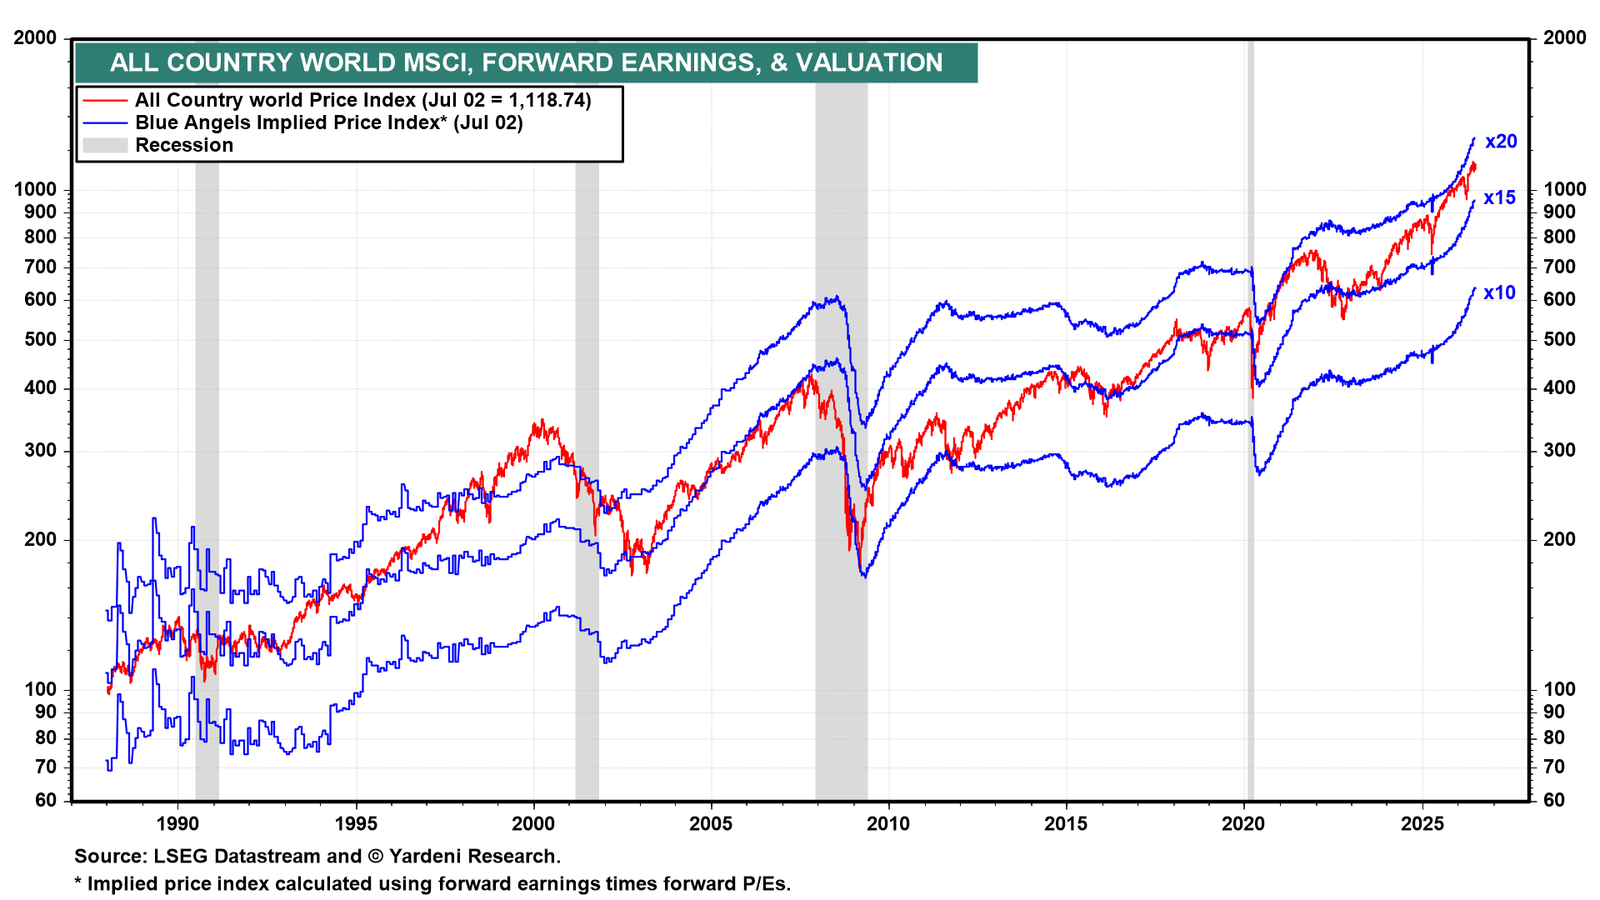
(4) Revenues & Earnings. The forward revenues of the All Country World MSCI remains in record-high territory, confirming that the global economy is doing surprisingly well despite the recent oil price shock (chart).
The forward earnings of the All Country World MSCI is also rising rapidly to new record highs (chart).
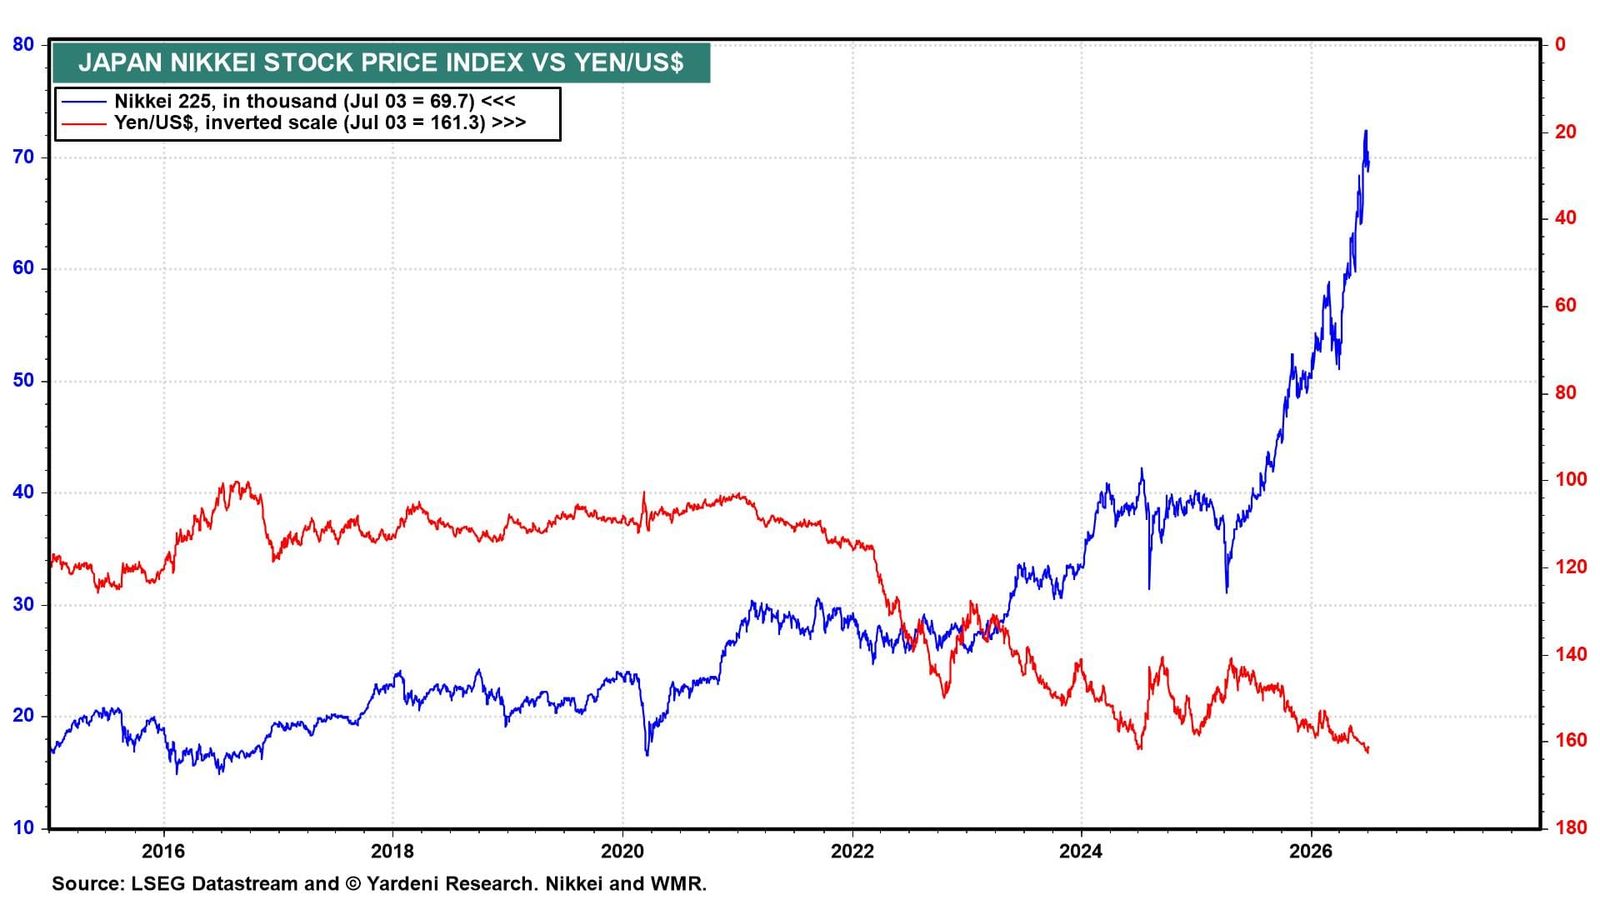
(5) Japan. The yen remains very weak because Japanese short-term interest rates remain well below comparable US interest rates (chart). A weaker yen is a positive for Japanese exporters.