We will miss Jerome Powell's chairmanship of the Fed. He is a nice guy. He did the best that he could as Fed chair from February 5, 2018, through May 15, 2026, when his term as chair expires. Nevertheless, he said he intends to remain a Fed governor for now. He can do so until his term on the Board of Governors expires on January 31, 2028.
President Donald Trump doesn't share our affection for Powell. He certainly wasn't nice to Powell. In any event, Trump focused more of his wrath on Iran today. The President posted a message on Truth Social expressing frustration with the stalled nuclear negotiations. He urged Iran to "get smart soon" and explicitly wrote, "NO MORE MR. NICE GUY!"
Reports from yesterday and today indicate that Trump has instructed his aides to prepare for an extended blockade of the Strait of Hormuz and Iranian ports. During a Situation Room meeting on Monday, he reportedly opted for this "prolonged squeeze" over more kinetic military options (like resuming bombing) or walking away from the conflict entirely. Secretary of State Marco Rubio noted earlier today that while the blockade is the current "safer" primary lever, the administration still has plans for "surgical" strikes in reserve should the deadlock continue.
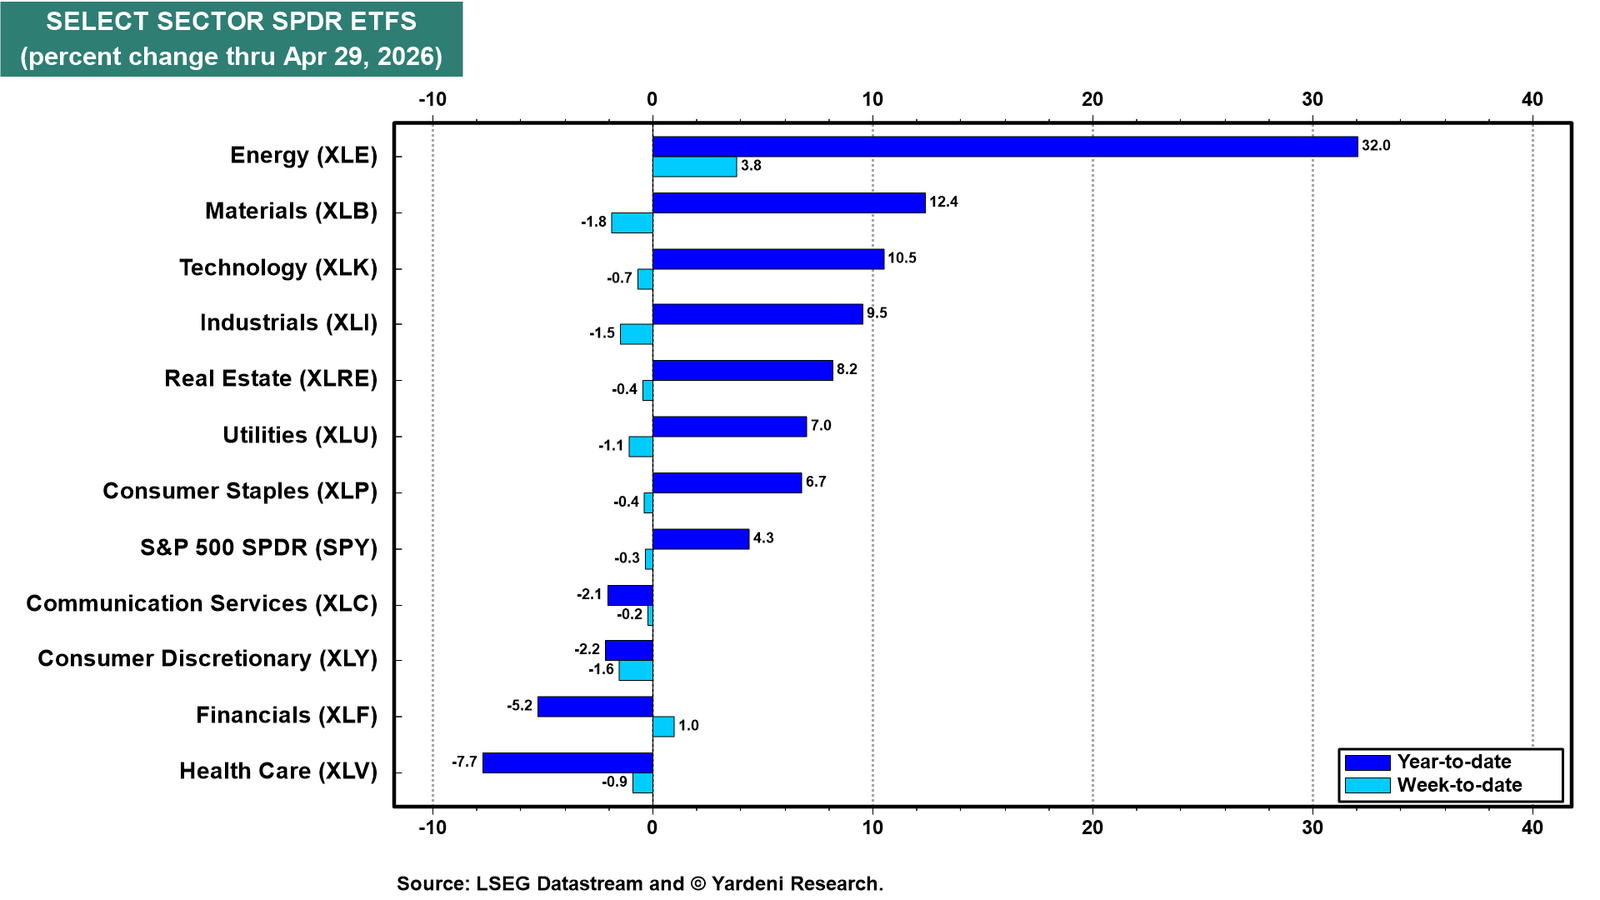
The prospect of a prolonged stalemate—albeit with a ceasefire and a possible resumption of the shooting war at any time—pushed oil prices higher to around $110 a barrel this evening. The stock market took it in stride with a 0.3% drop so far this week (chart). On April 21, we (belatedly) recommended overweighting the S&P 500 Energy sector as a hedge against a prolonged blockade of oil from the Arabian Gulf. XLE is up 5.7% since then.
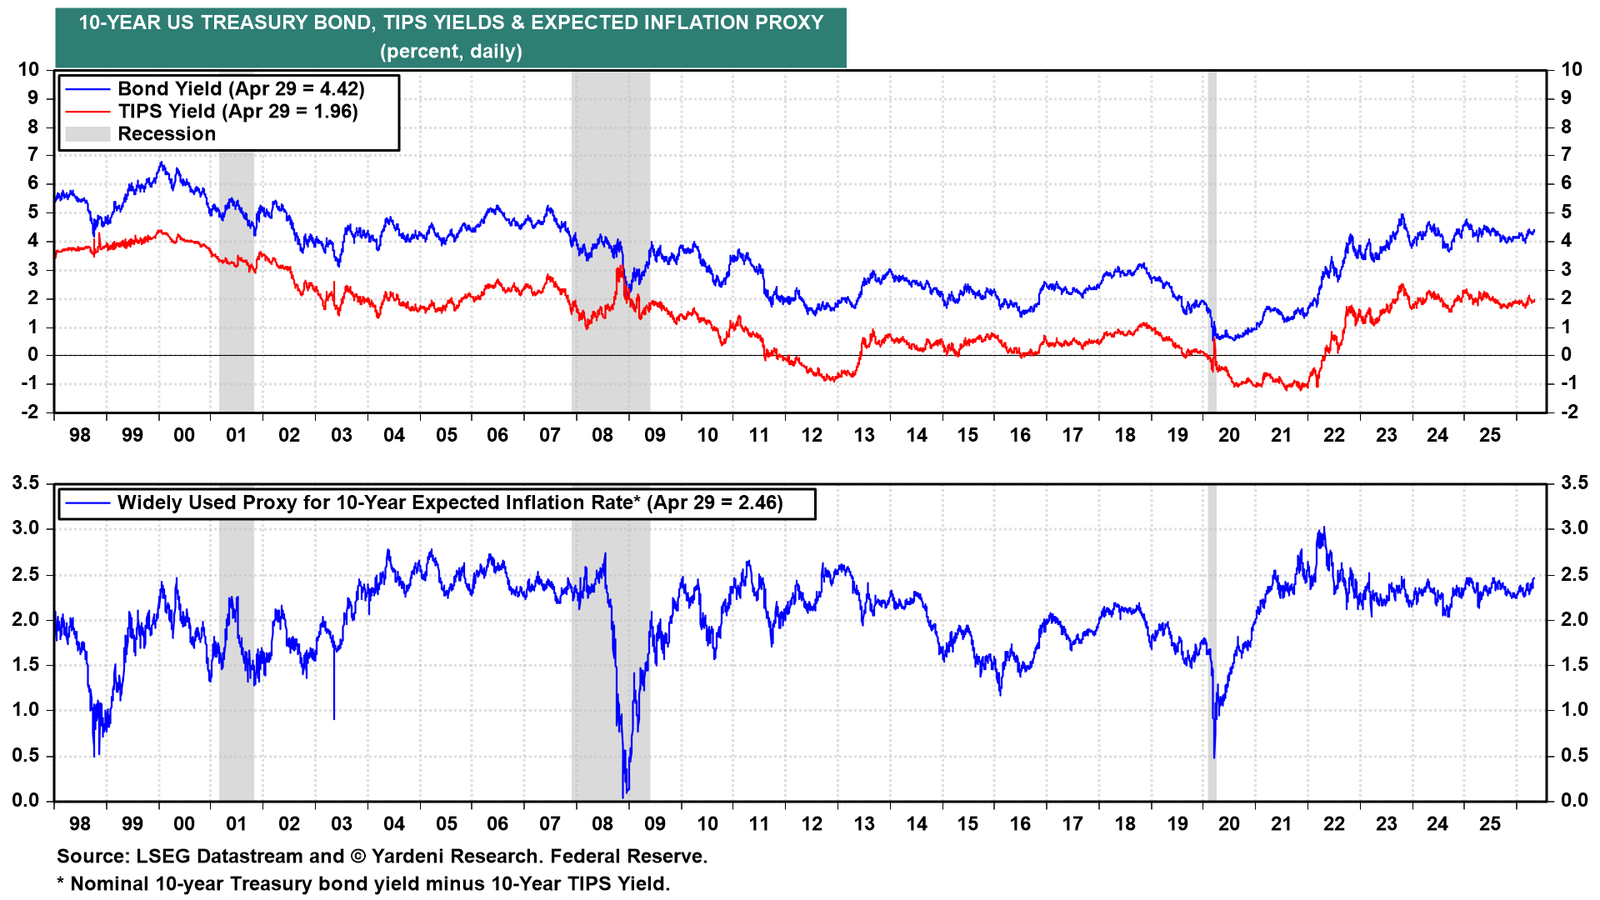
The bond market is starting to signal concerns that the energy shock might cause a more persistent, rather than transitory, inflation problem. The 10-year Treasury bond yield is up from 3.95% on February 27 (a day before the war started) to 4.25% this evening (chart). The widely used proxy for the 10-year expected inflation rate accounts for most of the increase. The Bond Vigilantes are starting to mutter: "No more Mr. Nice Guys."
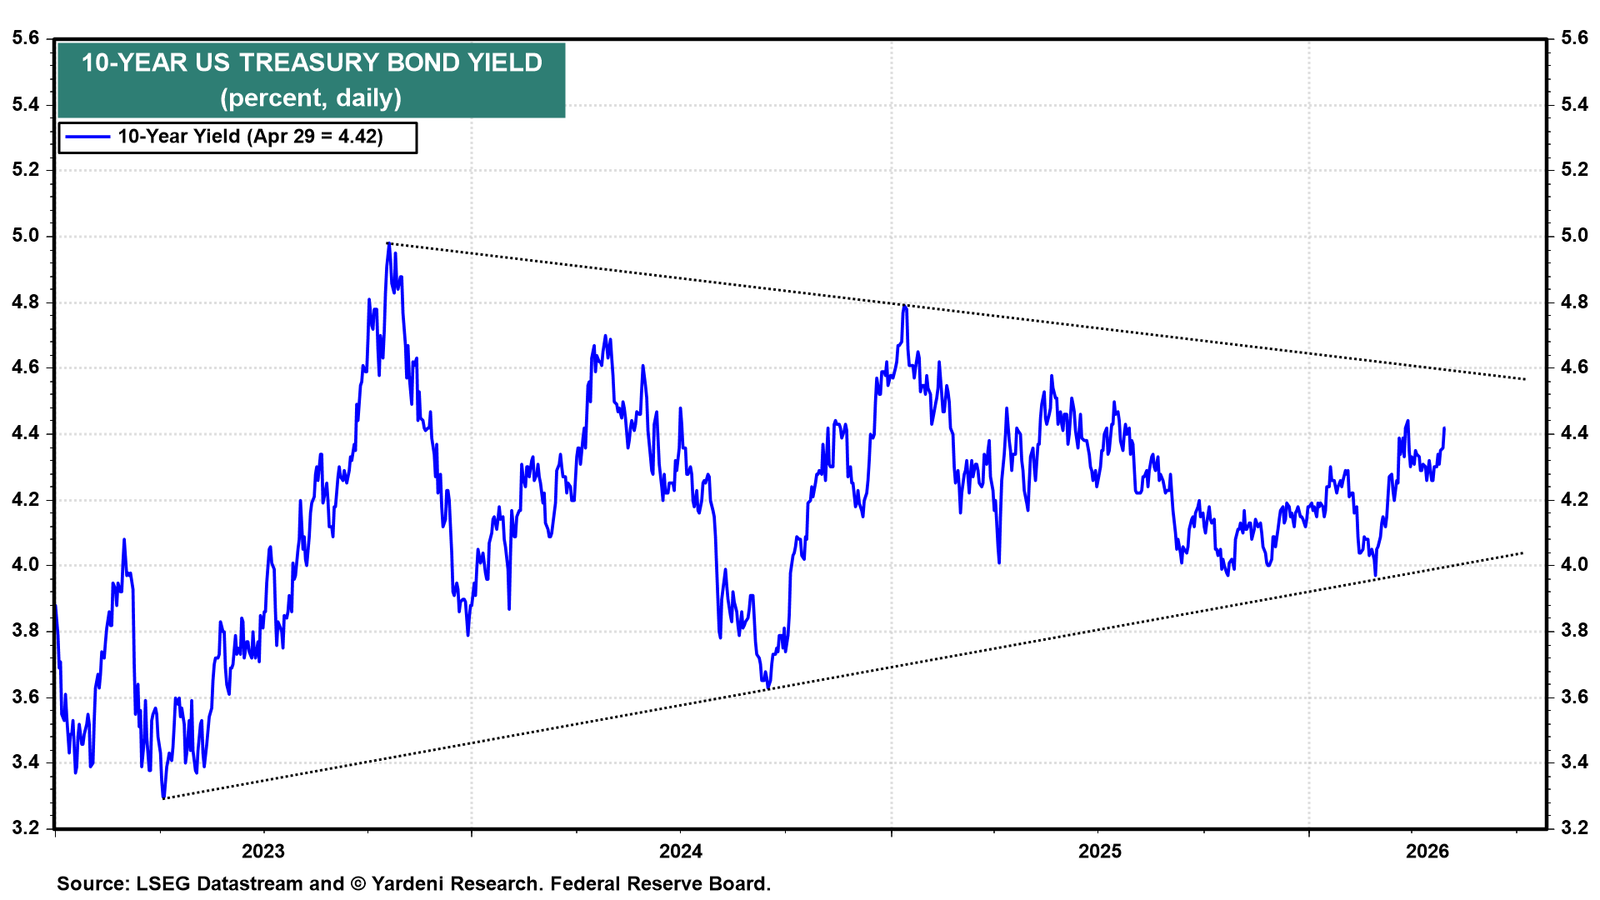
We've been predicting a 4.25%-4.75% range for the 10-year bond yield this year. The yield is likely to rise to 4.55% in the next few days (chart).
Contributing to the upward pressure on the bond yields is the Fed’s hawkish decision today to hold the federal funds rate where it is. It may be a preview of the divided institution Kevin Warsh is about to inherit. No more nice guys and gals on the FOMC.
Consider the following:
(1) A committee split down the middle. A supply shock is the hardest environment for a central bank to navigate. It pushes inflation up and growth down simultaneously, and different FOMC participants will naturally lean in different directions in response. Today's vote showed exactly that. The FOMC divided along the widest lines of dissent in decades. Governor Miran voted for a quarter-point cut. The other three dissenters (Kashkari, Logan, and Hammack) supported the hold but pushed to remove the easing bias in the statement entirely, arguing that the next move is as likely to be a hike as a cut. Warsh is walking into a divided committee, which will make it very difficult for him to advocate successfully for rate cuts.
Not surprisingly, the federal funds rate futures market turned slightly hawkish today on the outlook for the Fed's policy rate over the next 12 months (chart).
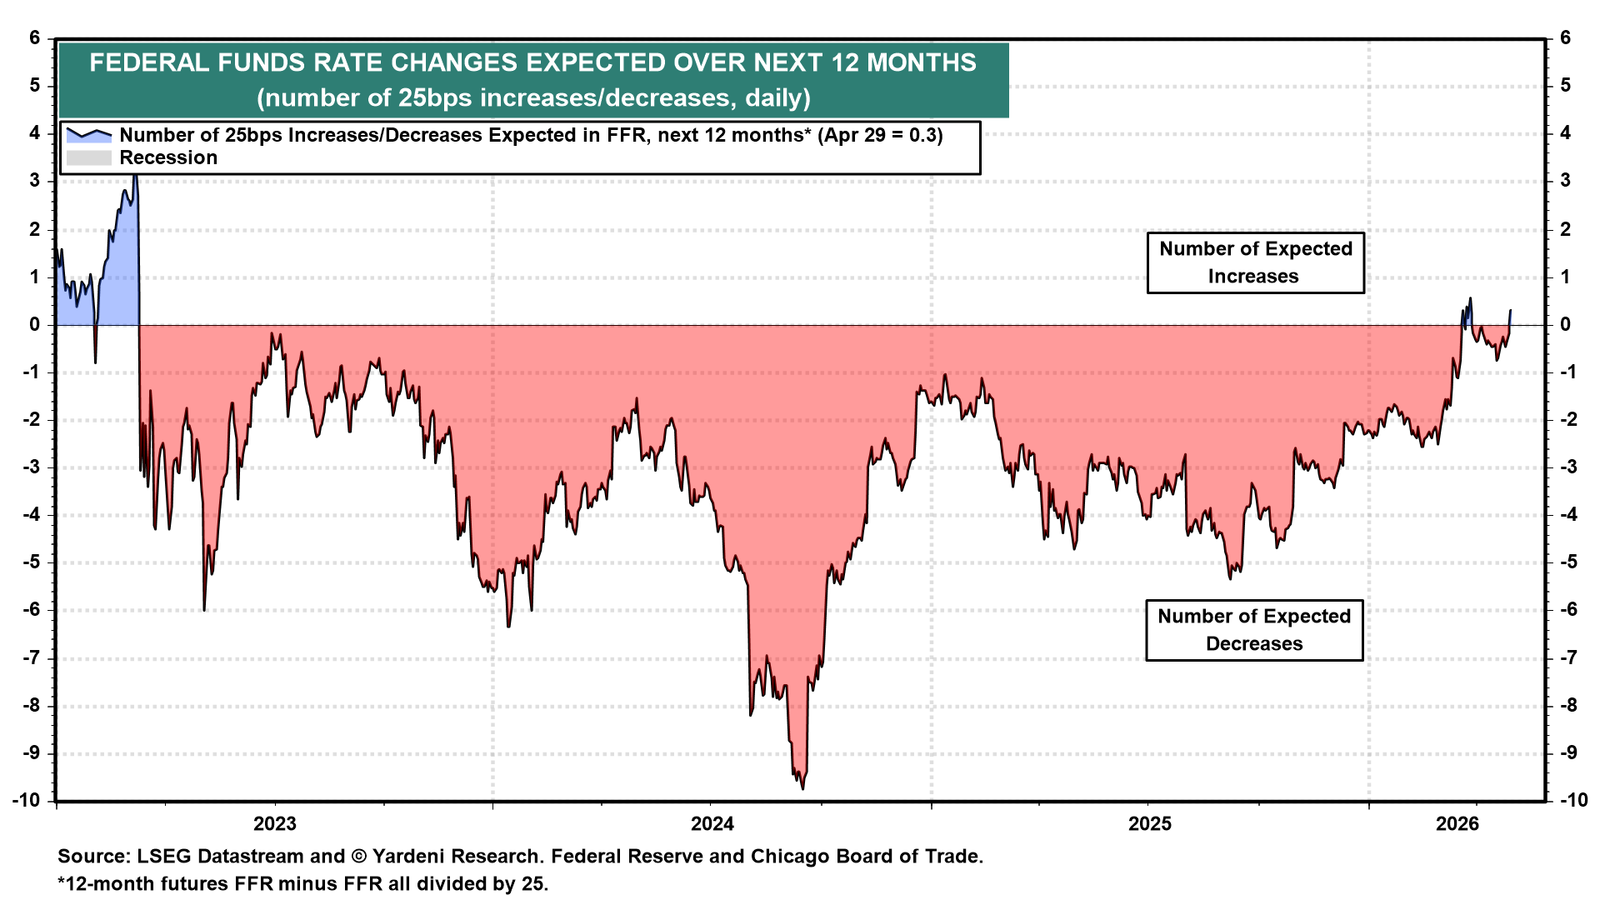
(2) Rates on hold through year-end. Today's decision reinforces our conviction that the federal funds rate won't move in either direction through year-end. Inflation risks have clearly increased. Powell noted that higher energy prices will push up overall inflation in the near term, a direct consequence of the closure of the Strait. At the same time, the US economy has shown considerably more resilience than most had anticipated, reducing the downside labor market risks that previously justified an easing bias.
Why not hike? Because rising energy prices have not yet seeped into underlying inflation. Long-term inflation expectations remain anchored, limiting the risk of a self-reinforcing price spiral. The economy does not need a cut; inflation does not yet demand a hike. The Fed is in a holding pattern, and we expect it to stay there.
(3) Powell is not going anywhere. Powell confirmed that he will remain on the Board after his chairmanship ends on May 15, until the now-dropped DOJ investigation is "well and truly over, with transparency and finality." He outlined the need for assurances that the case will not be reopened absent a criminal referral from the Fed's own Inspector General, and he made clear that his decisions will be guided "entirely by what I believe is in the best interest of the institution." He is a nice guy. Leave him be.