In the autumn of 1956, Egypt's Gamal Abdel Nasser nationalized the Suez Canal. Britain, France, and Israel invaded. The canal closed for five months. Two-thirds of Western Europe's oil moved through it, and the price of crude doubled in dollar terms before the year was out. The Dow Jones Industrial Average fell about 10% from its July high to its October low. Tankers were forced to reroute. By the following spring, with the canal reopened, the DJIA had recovered and reached a new high. With the exception of the 1970s, geopolitical oil supply shocks have tended to be buying opportunities for stocks.
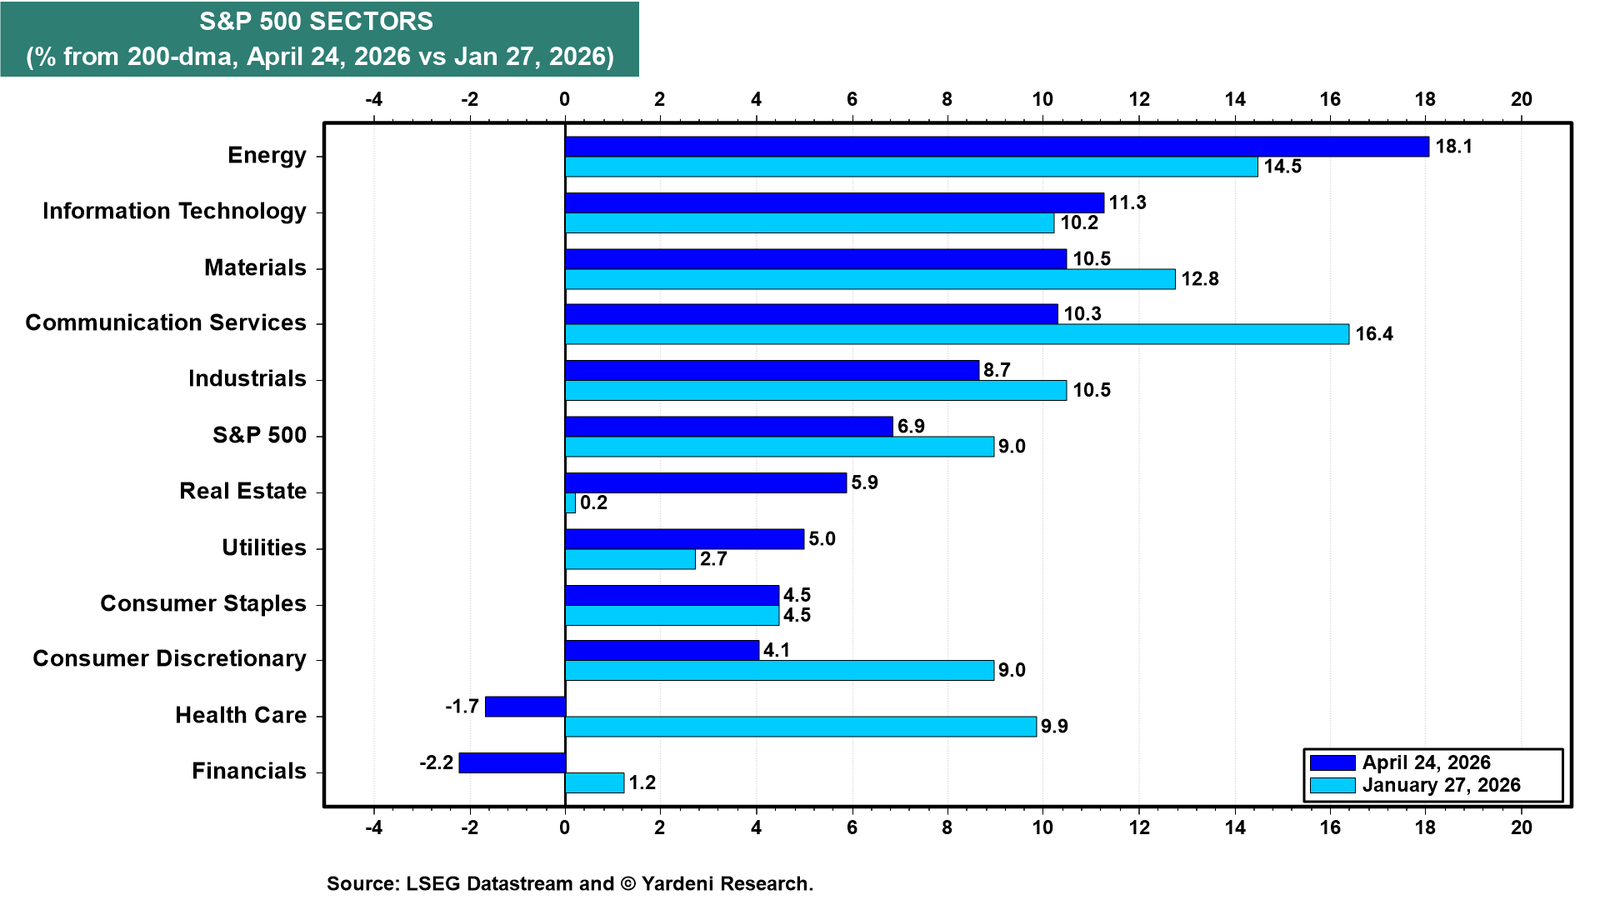
Investors reached the same conclusion again, this time on March 31. The fact that the Strait remains closed hasn't stopped the extraordinary stock market rally since then. Interestingly, the S&P 500 Energy and Information Technology sectors are now more overvalued relative to their 200-day moving averages than they were at the market's January 27 peak (chart). This suggests that many investors may have a barbell position across these two sectors, in case everything goes right (so IT wins) or wrong (so Energy wins). That makes sense to us since we are recommending a market weight in IT and an overweight in Energy.
This evening, the price of a barrel of Brent crude is up a couple of bucks because neither the US nor Iran showed up for another round of peace talks in Islamabad over the weekend. This morning, President Donald Trump said, "If they want to talk, they can come to us, or they can call us. You know, there is a telephone. We have nice, secure lines." For now, the ceasefire is holding, but so are the US blockade of Iranian ports and the Iranian blockade of the Strait of Hormuz. This could be the new status quo for a while.
Our base case from here is that the S&P 500 chops around 7,000 while the stalemate holds, then grinds higher in the second half of this year toward our 7,700 year-end target. That's assuming a deal by mid-year. Midterm elections drama might make the ride bumpy during the second half of this year. We think the March 30 low was the year's low.
There's no shortage of uncertainty, but it is quite certain that Kevin Warsh will be the next Fed chair, now that the Department of Justice has dropped its criminal investigation of Jerome Powell over the Fed headquarters renovation overrun. Polymarket puts the odds of Kevin Warsh’s confirmation by May 15 at roughly 87%.
Also relatively certain is that the economy and corporate earnings remain resilient:
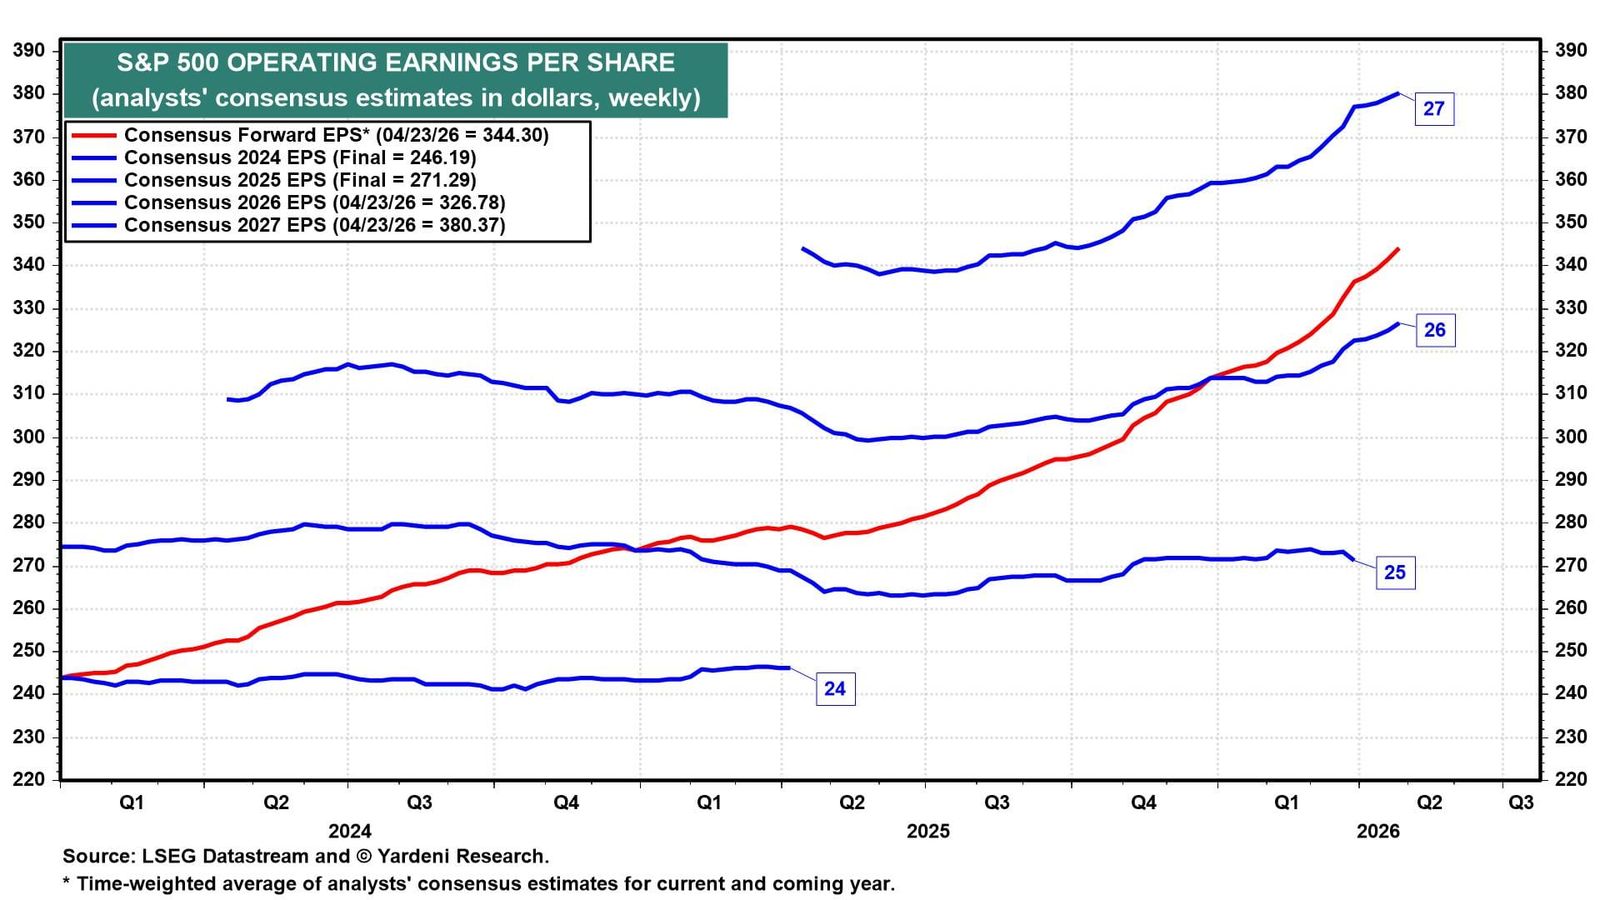
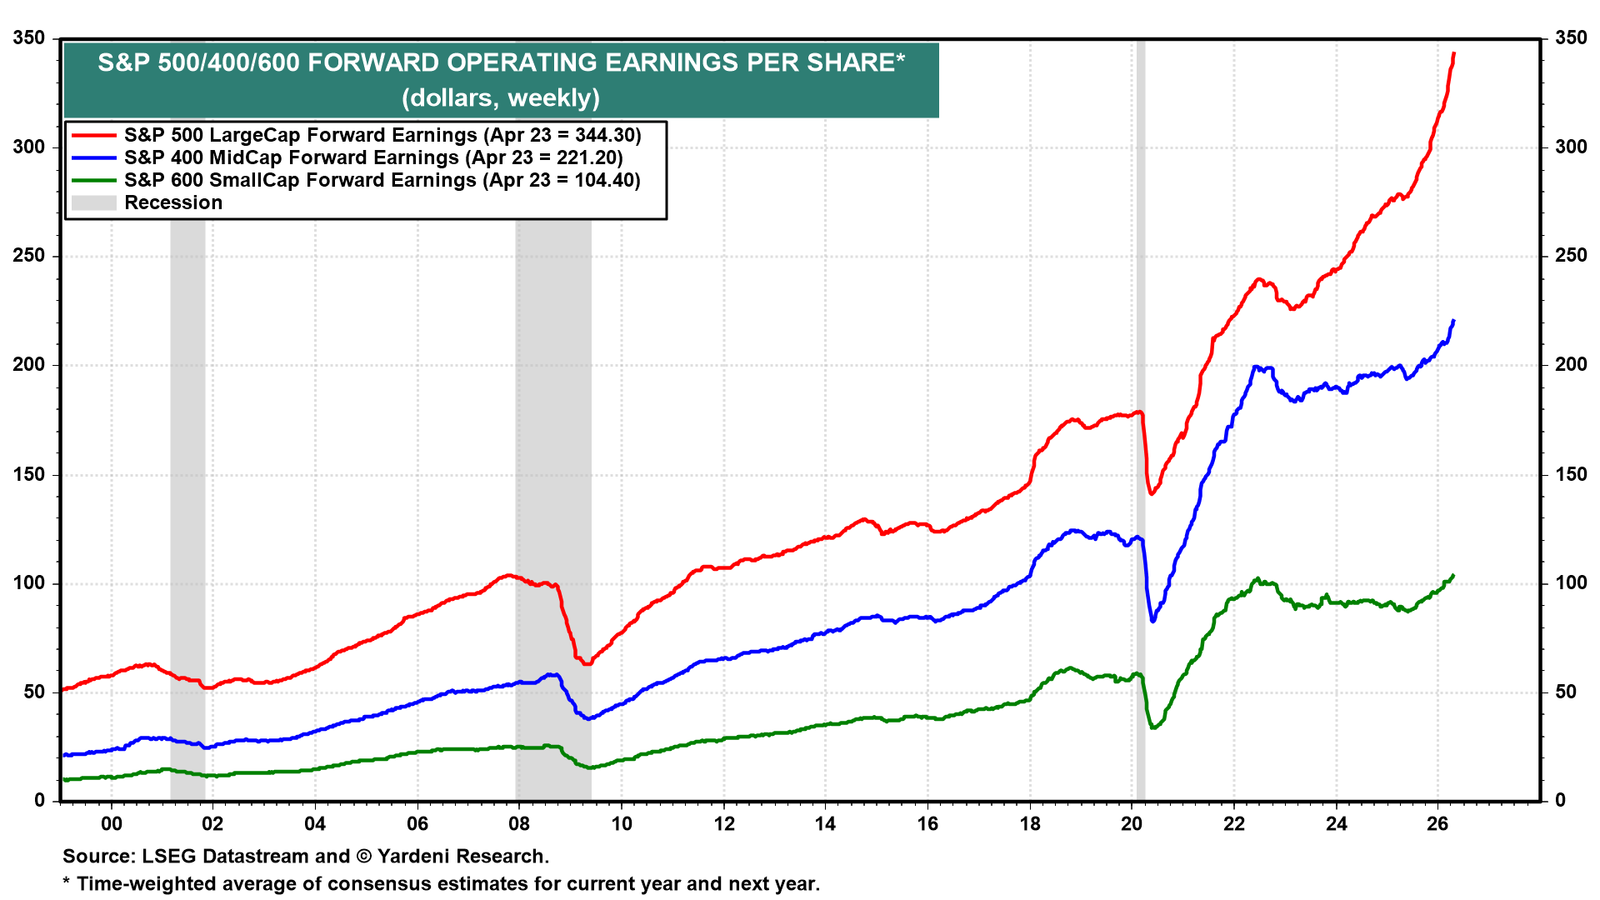
(1) S&P 500 earnings expectations. S&P 500 forward EPS hit another record high at $344.30 last week (chart). The analysts’ consensus estimates from which we derive forward EPS are $326.78 for 2026 and $380.37 for 2027. Both continue to be revised higher.
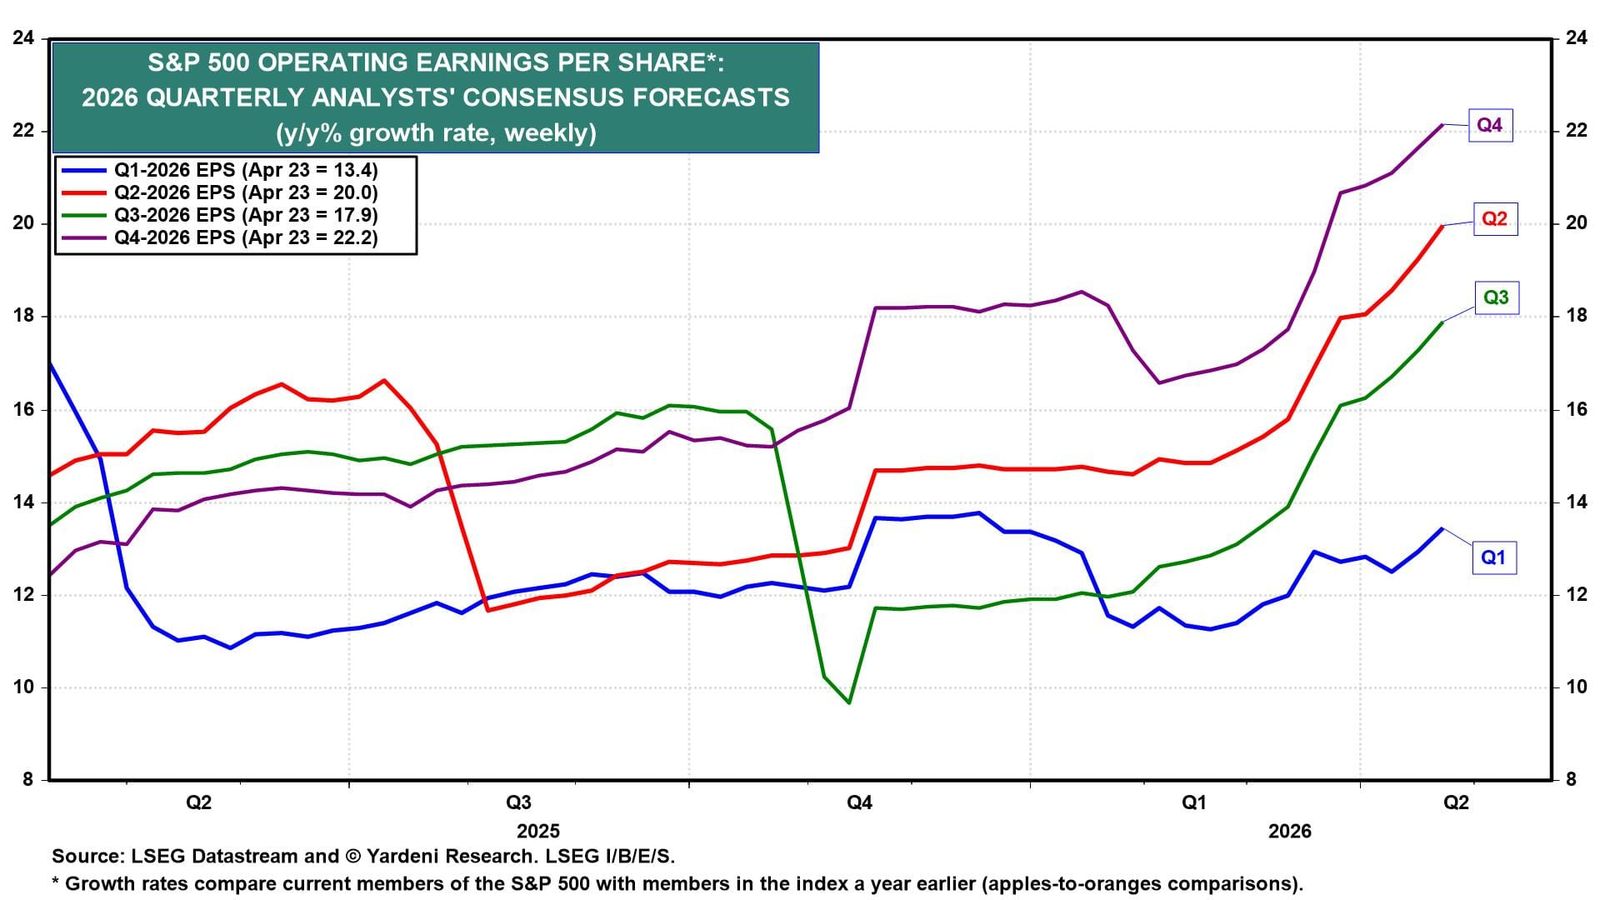
Also remarkable is that industry analysts continue to raise their consensus S&P 500 EPS growth rates for all four quarters of this year (chart). The gains are all in the double digits.
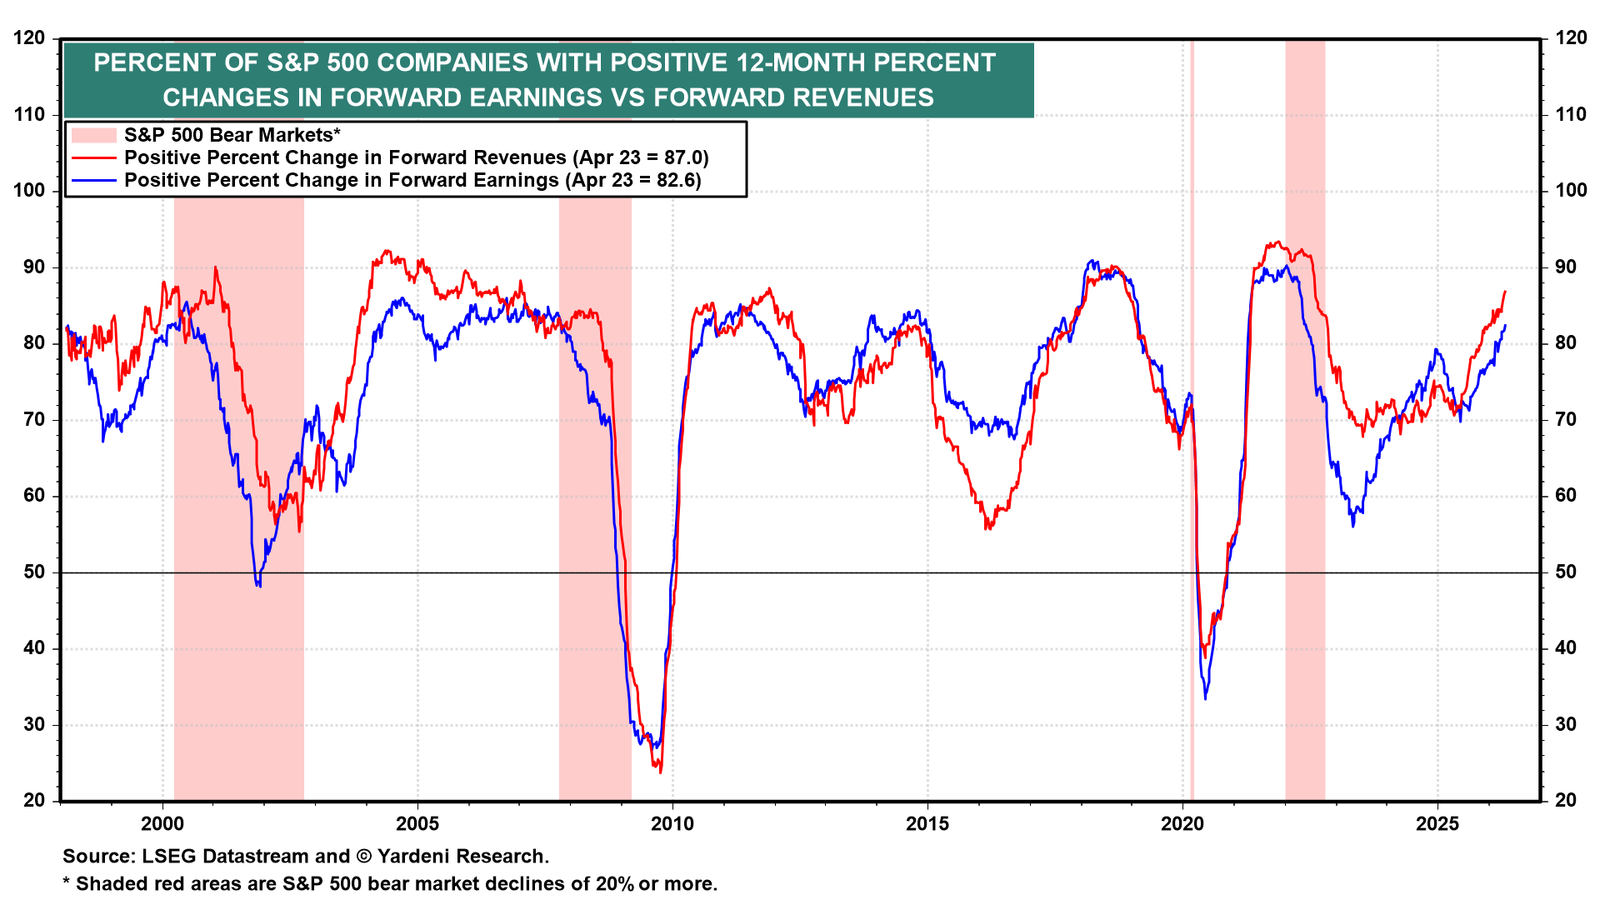
(2) S&P 500 earnings breadth. The share of S&P 500 companies with positive 12-month forward revenue growth is 87.0%, and the share with positive forward earnings growth is 82.6% (chart). Earnings breadth may be on track to reach 90% for both over the rest of this year. That's what it has done during previous bull markets.
Also showing improvement in earnings breadth are the forward earnings of the S&P 400 and S&P 600 (chart). Both have lagged the S&P 500's forward earnings, but they have now climbed into record-high territory.
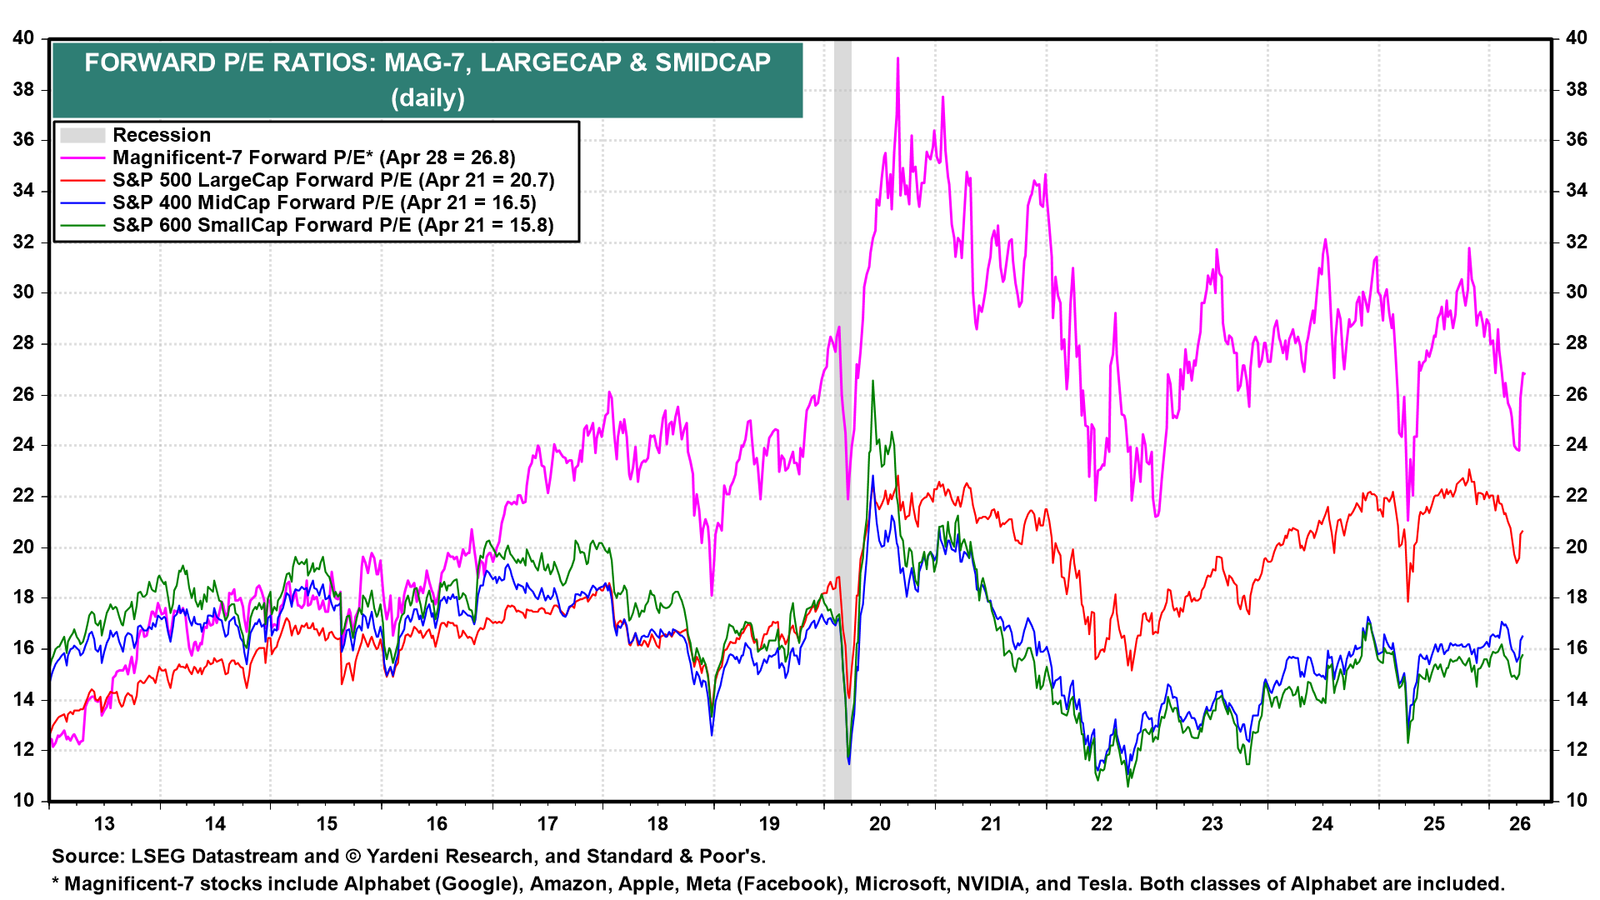
(3) Valuation. The valuation correction is probably over. Throughout the January 27 to March 30 pullback in the S&P 500, we observed that the drop in the forward P/E was partly attributable to rising forward earnings, which moderated the index's decline to 9.1%, just shy of the 10.0% drop that would indicate a correction (chart) . Investors bought this dip when they realized that stocks had gotten cheaper even as earnings were rising to new highs.
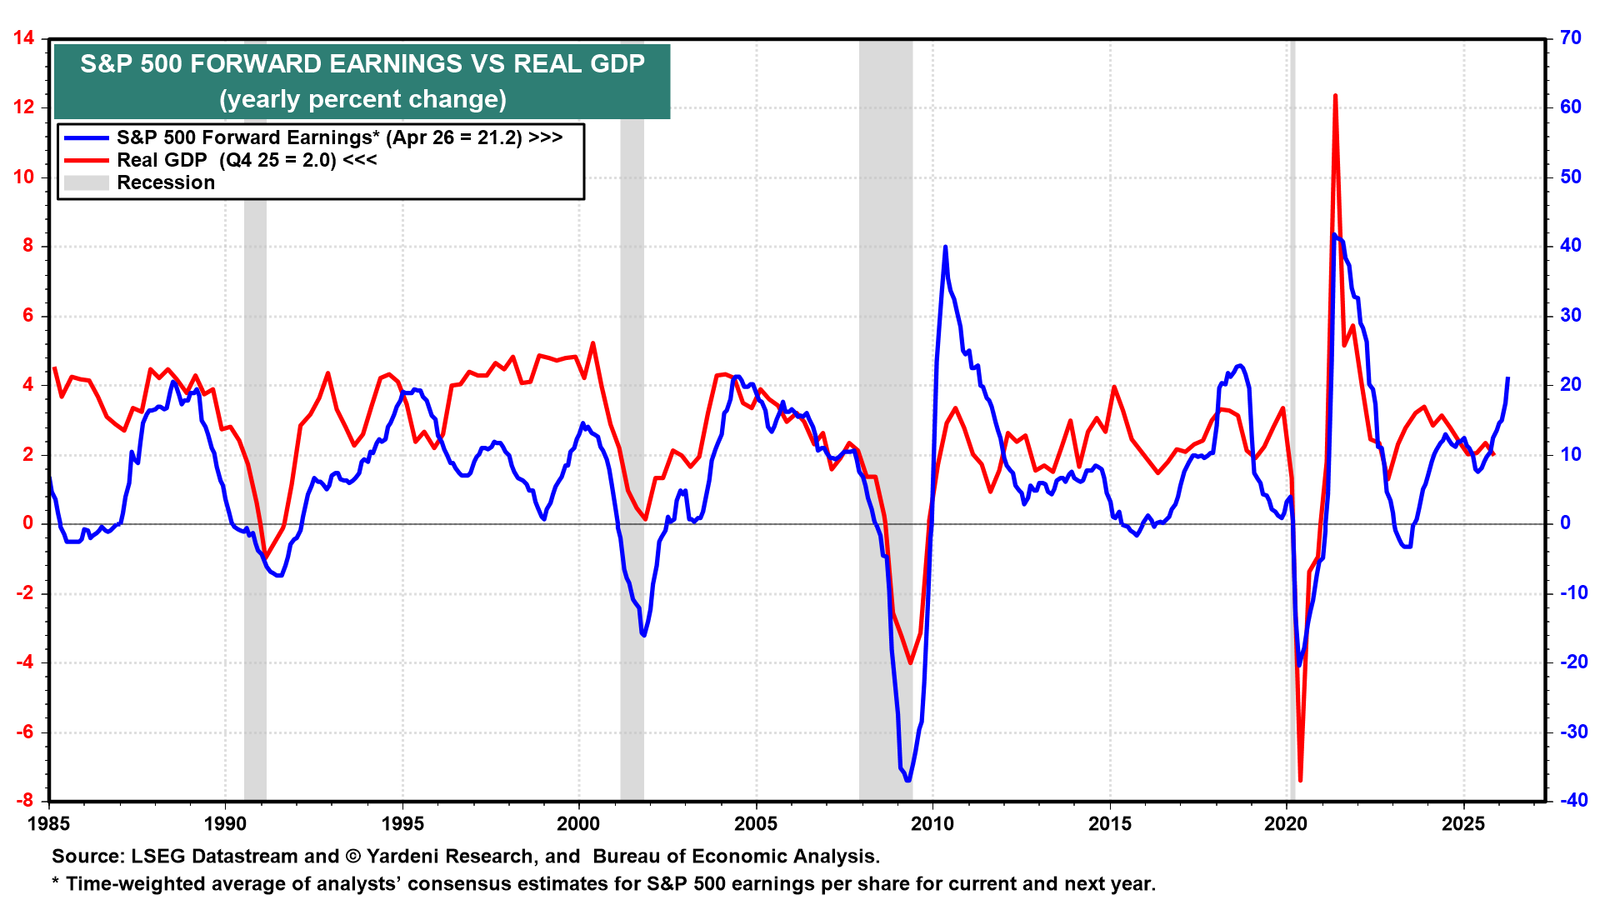
(4) GDP. S&P 500 forward earnings growth is a good leading indicator of real GDP growth (chart). The recent sharp upturn in the former suggests that economic growth could be surprisingly strong over the rest of this year, following a weak start during Q1, probably because the weather was worse than usual in January and February.
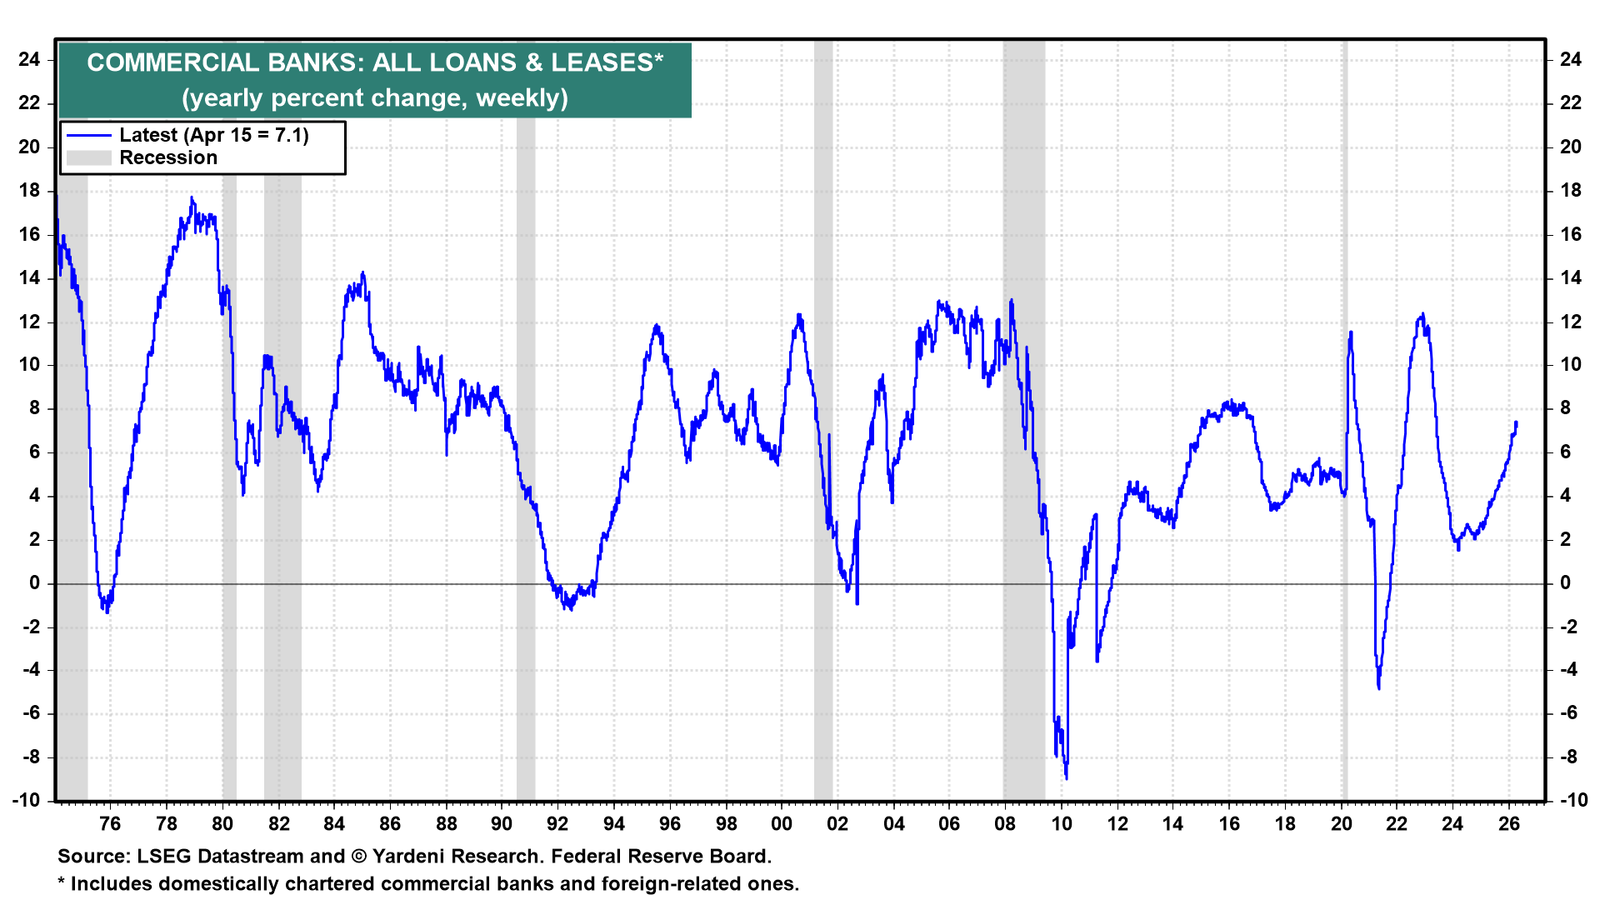
(5) Credit. Commercial bank loans and leases are up 7.1% y/y, the fastest pace in roughly three years (chart). This is the main reason we aren't concerned that the problems in the private credit market will cause an economy-wide credit crunch and a recession.